What Is Behind-the-Meter Power? On-Site Supply for AI Data Centres
Behind-the-meter power is on-site electricity on the customer's side of the utility meter. Leased megawatts do not pay until the hall is energised — and the queue is why that gap exists.
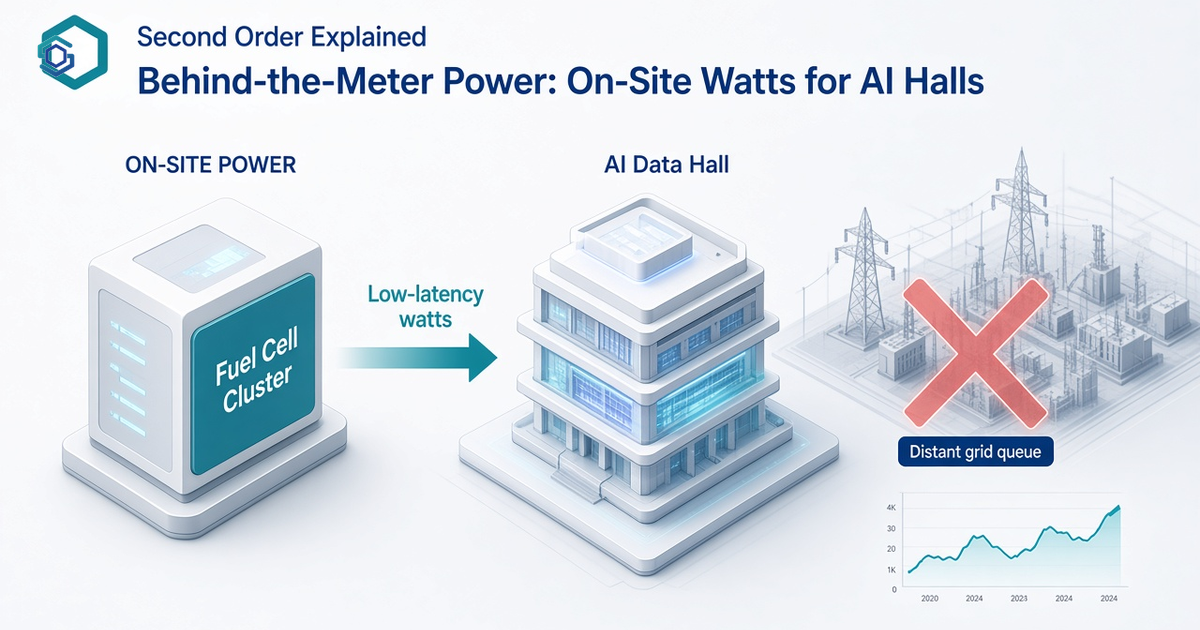
Behind-the-meter power is electricity generated on the customer's side of the utility meter — on-site gas, temporary generation, or a campus plant — instead of drawn from the grid.
This page sits in The Stack as reference — not a focus layer door.
For AI data centres it is a way to start earning before the grid connection arrives. The money question is simple: leased megawatts do not pay until the hall is energised, and behind-the-meter supply is one way to close that gap.
EXPLAINEDLast reviewed: 20 Sep 2026Next review: after the next LBNL queue report
In short: Behind the meter means generation or supply on the customer side of the utility meter. It is a different clock from a multi-year interconnect queue, with its own fuel, permit, and equipment risks. Leased megawatts stay dark until energised — that is where cash waits.
Education only. Not investment advice. Do your own research.
What does behind the meter mean?
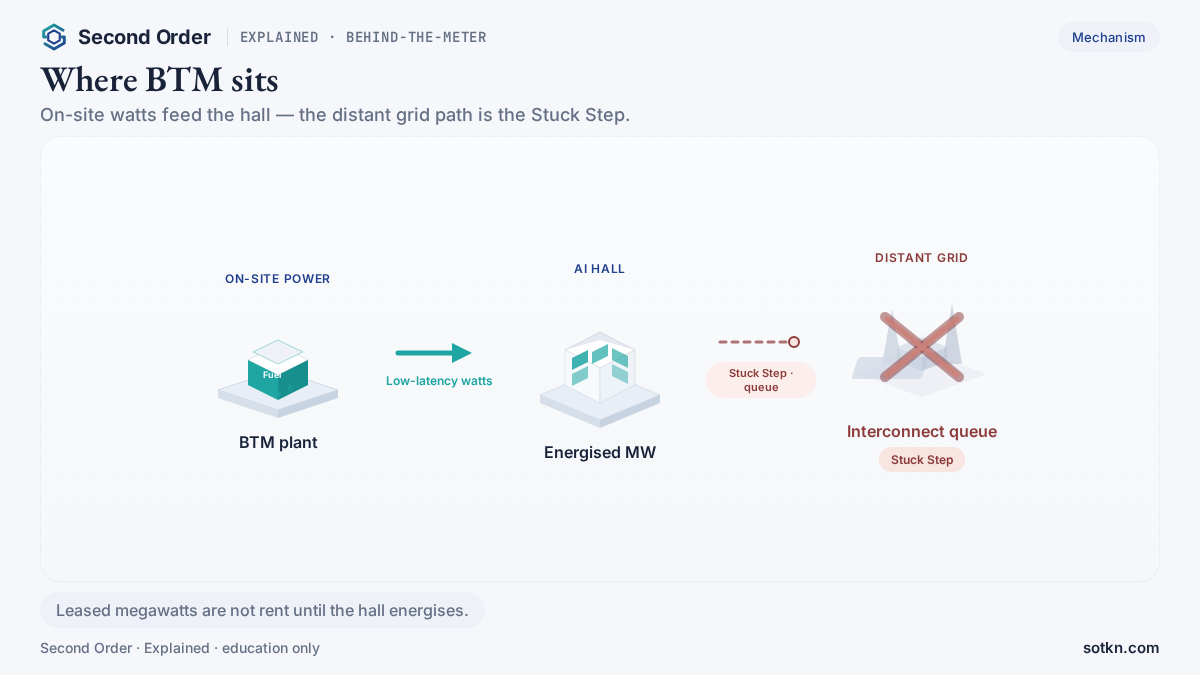
| Path | Role | What to read |
|---|---|---|
| Grid interconnect | Utility / ISO path | Queue position + network upgrades |
| Behind-the-meter plant | Customer-side supply | Fuel, permits, equipment lead times |
| Energised MW | Hall live | Where contracted capacity starts paying |
| Leased but dark MW | Contract only | Receivable waiting on power |
Behind-the-meter (BTM) is generation or supply on the customer's side of the utility meter rather than through a new grid connection. For hyperscalers and neoclouds, that usually means on-site gas, temporary generation, or a campus plant bridging a delayed interconnect. The term answers which side of the meter the watt comes from — not whether the project is cheap, permitted, or live.
Why does the distinction matter?
Because a lease is not cash. Energised megawatts are what start paying.
Landlord and operator disclosures increasingly separate leased megawatts from energised megawatts — that split is where the money sits. A signed lease on a dark hall is a receivable waiting on electrical gear; see speed-to-power explained.
Behind-the-meter contracts try to pull energisation forward when the queue outruns the lease. Ask which clock a press release moves: queue position, or live megawatts on site.
How long does a grid connection actually take?
For US generator projects that reached commercial operation in 2025, the median wait from interconnection request to commercial operations was 61 months — just over five years (LBNL Queued Up 2026 Edition, data through end-2025). Active capacity seeking interconnection was about 2,061 GW (1,312 GW generation; 749 GW storage) across roughly 8,200 projects — down 10% from 2,290 GW at end-2024. Only 13% of capacity entering queues from 2000–2020 had reached commercial operations by end-2025; 75% had withdrawn.
| Metric | Figure | As of / for | Source |
|---|---|---|---|
| Active capacity in US queues | 2,061 GW | End of 2025 | LBNL Queued Up 2026 |
| Median IR → commercial ops | 61 months | Projects completed in 2025 | LBNL Queued Up 2026 |
| Median IR → interconnection agreement | 45 months | 2025 | LBNL Queued Up 2026 |
| Prior-year IR → COD median | 55 months | Projects completed in 2024 | LBNL Queued Up 2025 |
| ERCOT active queue capacity | 408 GW | End of 2025 | LBNL Queued Up 2026 |
| PJM active queue capacity | 144 GW | End of 2025 | LBNL Queued Up 2026 |
| West (non-ISO aggregate) active | 567 GW | End of 2025 | LBNL Queued Up 2026 |
Queued Up covers generator (not load) interconnection — the standard public proxy for multi-year queue waits. Education only.
FERC Order No. 2023 (28 July 2023; effective 6 November 2023) requires first-ready, first-served cluster studies plus commercial-readiness and site-control rules (FERC Order 2023 explainer). Order 2023-A (21 March 2024) clarified the rule. LBNL still calls it too early to measure the full effect, even as 2025 withdrawals rose and active backlog eased 10%.
Regional colour: ERCOT held 408 GW active at end-2025 under connect-and-manage; PJM about 144 GW while working through older backlog. The market door is US markets.
How fast can behind-the-meter power be built?
Faster than a five-year interconnect — when turbines, fuel, and permits are actually available. That caveat is doing more work in 2025–2026 than the brochure implies.
| Option | Typical unit / scale | Indicative lead time | Source / as at |
|---|---|---|---|
| Large frame gas turbines (major OEMs) | Utility-scale GT / CCGT | 5+ years quoted for most major OEMs; smaller frames ~3–4 years | EPRI (Bobby Noble) via Reuters, 21 Jul 2025 |
| OEM quotes (Platts) | Heavy-duty gas turbines | 5–7 years reported | S&P Global / Platts, 20 May 2025 |
| Aeroderivative (LM2500XPRESS) | ~35 MW/unit; ~95% factory-assembled | Faster install than heavy-duty; still gated by order slot + site | GE Vernova / Crusoe PR, 22 Jul 2025 |
| Temporary / mobile gas | Bridge MW | Months when fuel + permits clear | Named campus practice |
Lead times are reported ranges from named coverage, not project quotes. Permitting and gas lateral work sit on top of OEM delivery.
Behind-the-meter is a different clock, not a free clock. Aeroderivative and temporary packages buy years back from the queue; heavy-duty order books can push a “fast” plant toward the same decade as a slow interconnect.
What does it cost?
Speed is bought, not saved. Capex per megawatt is only the first line.
For US generators installed in 2024, EIA reports capacity-weighted construction costs of US$841/kW for combustion turbines and US$1,522/kW for natural-gas internal combustion engines (EIA, 2024 installs) — about US$0.84m–US$1.5m per MW nameplate before fuel, ops, emissions controls, and balance-of-plant.
Fuel exposure is the ongoing cost a utility tariff mostly hides. A behind-the-meter gas plant makes it a direct operating risk. Operators pay vendors and fuel suppliers to pull energisation forward; landlords still wait on live megawatts before contracted capacity pays.
Who is actually doing this?
Three dated examples show the range — modular on-site turbines, nuclear co-location, and temporary bridge generation.
- Crusoe × GE Vernova (22 Jul 2025). 29 LM2500XPRESS units (~35 MW each) for AI data centres — 10 booked Dec 2024, 19 in Jun 2025 — expected near 1 GW. Source: GE Vernova PR.
- Talen × Amazon at Susquehanna (1 Nov 2024). Existing 300 MW behind-the-meter ISA; FERC rejected an amended ISA seeking 480 MW (path toward 960 MW). Source: Utility Dive.
- xAI Memphis (permits 3 Jul 2025). Shelby County permitted 15 Solar SMT-130 gas generators (up to 247 MW); reporting cited earlier operation of as many as 35 units (~421 MW). Source: TechCrunch.
Reported project facts, not recommendations. Stuck steps differ: equipment orders, co-location rules, or air permits.
Behind-the-meter versus the grid queue
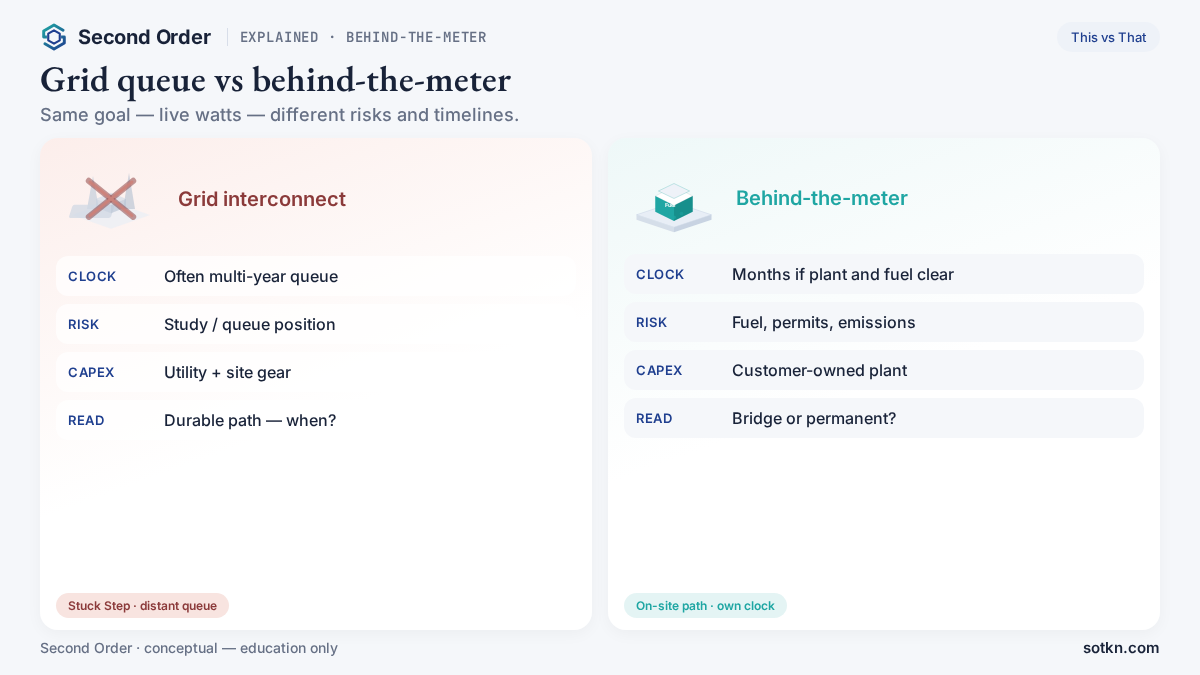
| Axis | Grid interconnect | Behind the meter |
|---|---|---|
| Clock | Median ~5 years IR→COD for generators completed in 2025 (LBNL) | Months to multi-year — kit + permits + fuel |
| Main risk | Queue position, network upgrades, withdrawals | Fuel, air/site permits, turbine lead times |
| Who owns the plant path | Utility / ISO process | Customer or campus developer |
| Cash question | When is the hall energised from the grid? | Bridge only, or base supply? |
Neither path is a recommendation, and both can fail. The job is to work out which clock a press release actually moves.
Where does the cash sit?
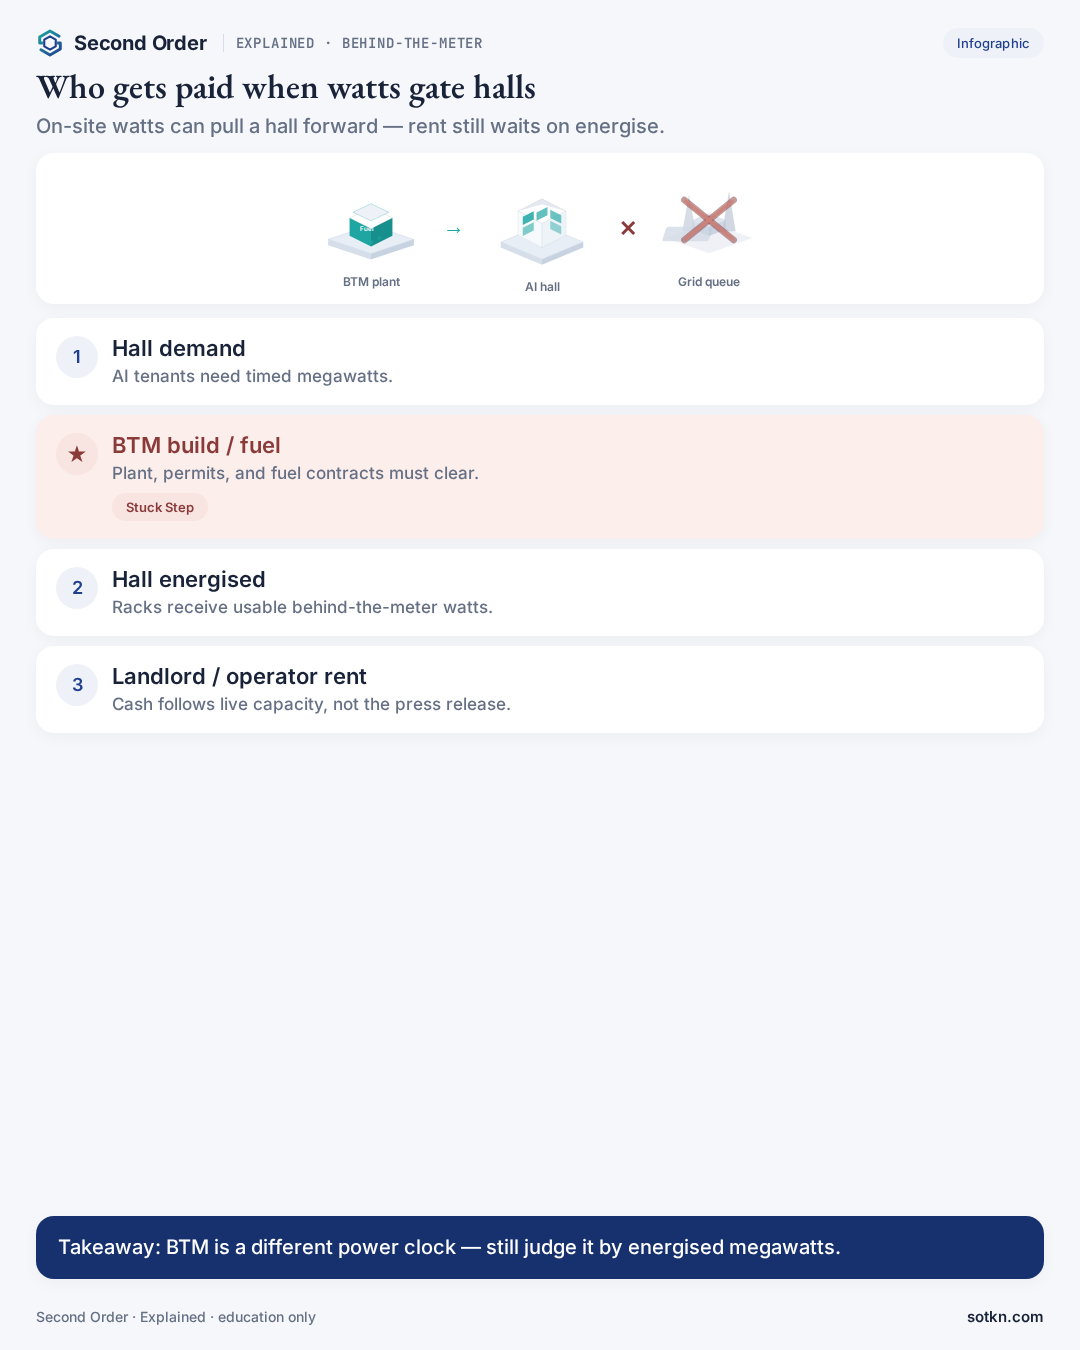
- Landlords with signed leases still wait on power before contracted capacity pays.
- Operators pay for bridging generation or on-site plants — capex plus fuel.
- Fuel and equipment suppliers capture spend when behind-the-meter builds.
- Tenants need energised megawatts before they can run GPUs at full clock.
Cash sits in leased-but-dark halls when interconnect lags. Behind-the-meter is one response. Landlords carry delivery risk; operators carry plant and fuel; tenants carry time-to-GPU.
Common misconceptions
- People assume it avoids permitting. Actually it swaps an interconnect queue for air, fuel, and site permits — sometimes under sharper local scrutiny.
- People assume it is cheaper. Actually EIA 2024 install costs put CT and gas ICE construction near US$0.84m–US$1.5m per MW before fuel. Speed is what is bought.
- People assume it equals backup diesel. Actually prime or bridge plants are sized to run halls, not only cover outages.
- People assume leased megawatts equal revenue. Actually leased megawatts are contracted; energised megawatts are live. Cash follows the second.
What still caps the hall after power arrives?
Cooling. Energised megawatts still need cooling capacity and rack design before GPUs run at full clock — see liquid cooling explained. Do not treat a hall as done on power alone.
What should you watch?
- Disclosures that split leased versus energised megawatts — the single most useful line.
- Behind-the-meter permit and fuel milestones, not only turbine order headlines.
- OEM lead-time commentary (5+ years for large frames as of mid-2025 coverage).
- Whether a hall claimed as ready has cooling as well as power.
- The next LBNL Queued Up edition — our next-review trigger.
Practical takeaways
- A lease is not cash — energised megawatts are what start paying.
- Behind-the-meter has its own fuel, permit, and equipment clock — not a free pass.
- Ask which megawatts are live, not which are signed.
- Power without cooling still leaves racks throttled.
FAQ
What does behind the meter mean?
Behind the meter means electricity is generated or supplied on the customer's side of the utility meter, not drawn through a new grid interconnection. In practice that is on-site gas, temporary generation, or a campus plant.
What is behind-the-meter power for data centres?
It is on-site supply used to energise halls when a grid connection is too slow or incomplete. It is a delivery path for live megawatts, not a free pass on permits or fuel.
How long does a grid interconnection take?
For US generator projects that reached commercial operation in 2025, the median wait from interconnection request to commercial operations was 61 months (LBNL Queued Up 2026 Edition). The median request-to-agreement time was 45 months.
Is behind-the-meter power cheaper than the grid?
Not necessarily. EIA figures for 2024 installs put combustion turbines near US$841/kW and natural-gas internal combustion engines near US$1,522/kW, before fuel. The usual trade is speed, not a lower lifetime bill.
What is the difference between leased and energised megawatts?
Leased megawatts are contracted capacity. Energised megawatts are actually live and drawing power. Cash from a hall generally follows the second, not the first.
Does behind-the-meter avoid permitting?
No. On-site generation has its own air, fuel, and site permits. Temporary units can still draw local scrutiny, as Memphis coverage in July 2025 showed.
Who is building behind-the-meter power for AI halls?
Named examples include Crusoe's 29 GE Vernova LM2500XPRESS units (nearly 1 GW, announced 22 Jul 2025), Talen–Amazon co-location at Susquehanna (300 MW ISA; FERC rejected a 480 MW amendment on 1 Nov 2024), and temporary gas generation at xAI Memphis.
Related terms
- Speed-to-power — the path from plan to energised megawatts.
- Liquid cooling — what still binds the rack after power arrives.
- Explained hub — the full glossary cluster.
Where this sits in the stack
Behind-the-meter power sits under the hall layer that hyperscalers and neoclouds pay to energise. The market door where US queue and co-location fights show up is US markets (also Markets).
Further reading
For the investment-shaped argument that the AI trade's real bottleneck is a 2028-facing grid queue, see Speed-to-power: the AI trade's real bottleneck is a 2028 grid queue.
How we check this
Figures come from company filings and government releases, each dated in the list below. Capacity and timing from press reports are labelled as reported, not guided. Where we work something out ourselves, the arithmetic is shown in full.
Last reviewed: 20 Sep 2026 · Next review: after the next LBNL queue report
Spot an error? Tell us and we will correct it and note the change here.
Sources
- LBNL Queued Up: 2026 Edition (June 2026) — PDF
- LBNL EMP news on 2025 interconnection backlog
- LBNL Queued Up: 2025 Edition (December 2025) — PDF
- FERC explainer — Order No. 2023
- EIA — construction costs, generators installed 2024
- GE Vernova / Crusoe PR, 22 Jul 2025 — 29× LM2500XPRESS
- Utility Dive — FERC rejects Talen–Amazon Susquehanna ISA amendment (Nov 2024)
- TechCrunch — xAI Memphis gas-generator permits, 3 Jul 2025
- Reuters — US gas-plant costs and lead times, 21 Jul 2025
Get the Wire — short notes when the power clock moves.
Hub for LBNL queue data: emp.lbl.gov/queues.