Applied Digital brings 75 MW online for CoreWeave
Applied Digital (2 Oct): +75 MW RFS at Polaris Forge 1 → 250 MW operational, CoreWeave-leased. MW online is not settled rent.
WIRE · NEOCLOUDS · US · Data as at 2 Oct 2026
Applied Digital said on 2 October 2026 it reached Ready for Service on another 75 MW of critical IT load at Polaris Forge 1, lifting the campus to 250 MW operational against a 400 MW contracted full buildout — a campus The Latent and Applied Digital’s FY2026 filing describe as fully leased to CoreWeave. On the neoclouds layer, megawatts marked operational are ready halls. They are not settled landlord rent — or settled GPU invoices — until lease recognition clears and the tenant bills utilization. Ready is not paid.
What happened
On 2 October 2026, Applied Digital (NASDAQ: APLD) announced Ready for Service for the second phase of Building 2 at Polaris Forge 1 in Ellendale, North Dakota: an additional 75 MW across three 25 MW data halls. That completes Building 2’s full 150 MW and brings fully operational critical IT load at the campus to 250 MW. The campus is contracted to deliver 400 MW at full buildout.
Print as reported:
Event
Applied Digital RFS — +75 MW critical IT load at Polaris Forge 1 (Building 2 phase 2)
Applied Digital IR, 2 Oct 2026 08:00 EDT — three 25 MW halls
Campus operational load
250 MW fully operational (from 175 MW after the prior Building 2 phase)
IR — completes Building 2 at 150 MW; first building was 100 MW
Contracted buildout
400 MW critical IT load contracted at full buildout — 150 MW still outside the operational total
Applied Digital IR 2 Oct; btw.media framing 2 Oct
Tenant
Fully leased to CoreWeave (existing framework — Oct 2 is not a new lease print)
The Latent 2 Oct; FY2026 filing via btw.media — 400 MW under CoreWeave leases
Remaining MW (context)
~150 MW still to deliver; VanEck’s Matthew Sigel: remaining 150 MW slated H1 2027
The Latent 2 Oct — schedule colour, not Oct 2 IR dollars
Stuck step named
RFS → tenant control / rent conversion → utilization + billing
250 MW operational ≠ disclosed base-rent figure for this phase
Do not treat 75 MW Ready for Service, 250 MW operational, or 400 MW contracted as cash already collected. The October release gives no incremental rent, fit-out, or contract-value dollar for this phase.
Why cash cares
On the neoclouds layer, landlord cash clears when delivered halls meet the lease recognition tests and base rent (and related lines) recognize — while the neocloud tenant’s cash clears when GPU hours or contracted clusters bill — see Neocloud explained, Who finances GPU clusters?, and What Is a Take-or-Pay GPU Contract?. A Ready for Service print is ready capacity. It is not yet paid. That gap is the whole Wire: Applied Digital can date 75 MW online on 2 October, and still be waiting on rent conversion and tenant utilization when the halls sit on the operational total.
Two cash clocks:
- MW online vs rent recognized. Applied Digital’s 10-K (via btw.media, 2 Oct) says rental revenue begins when a property is ready for the tenant’s intended use and the tenant takes possession or controls its physical use. RFS is an important milestone. The October announcement does not quantify the date or amount of rent recognized for this phase. Fiscal Q4 ended 31 May — before both reported 75 MW Building 2 phases — showed HPC Hosting $203.0 million, of which base rent was $44.1 million, tenant fit-out services $152.4 million, and recoveries $6.5 million. The largest line was fit-out, not rent. Do not invent a rent-per-megawatt run rate from that quarter divided by 100, 175, or 250 MW.
- Landlord RFS vs tenant GPU cash. CoreWeave is the named lessee on the campus framework. MW ready for the tenant is not proof CoreWeave has already collected GPU-hour or megawatt-contract invoices on those halls. Who gets paid on the landlord side is Applied Digital if base rent converts. Who gets paid on the neocloud side is CoreWeave if utilization and contracts on that capacity perform.
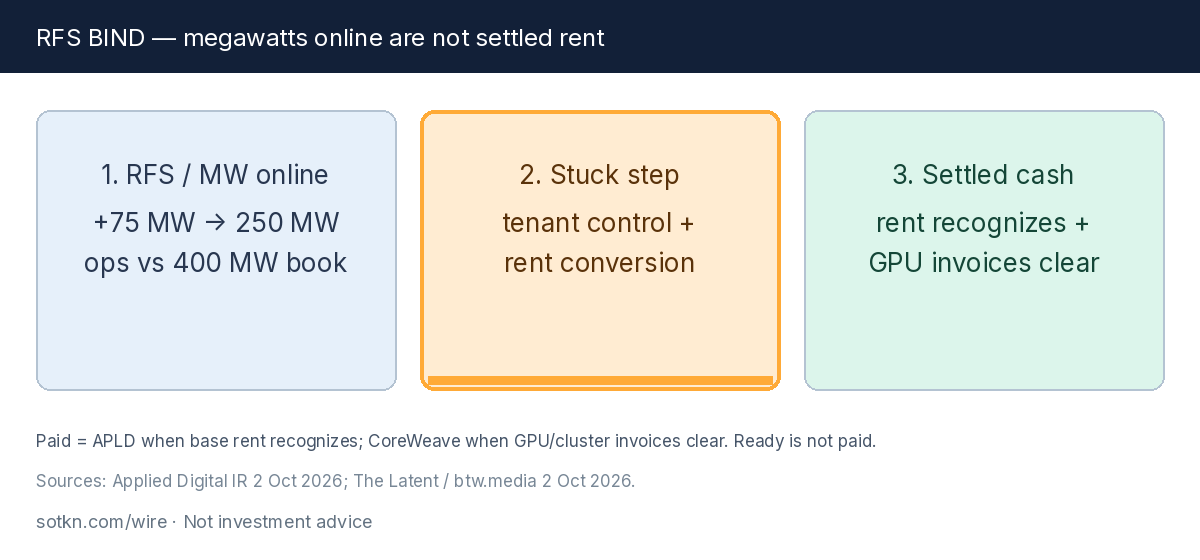
Figure — RFS bind. Ready for Service / MW online → tenant control + rent conversion → utilization + billing. Amber on the bind. Paid = Applied Digital when base rent recognizes; CoreWeave when GPU/cluster invoices clear.
Context: not a new lease, remaining buildout, and the mix
Context, not a new contract print. btw.media (2 Oct) stresses the October update is a delivery step under an existing commercial framework — Applied Digital’s FY2026 filing already described 400 MW under CoreWeave leases at Ellendale, including a separate 150 MW Building 4 expected service-ready in 2027 on the filing’s then-current schedule. The October 2 release does not update that schedule or disclose incremental contract value.
Wes Cummins’s line that securing power is only the starting point, and that the real work is designing, building, commissioning, and operating infrastructure that turns megawatts into usable capacity, is the company’s own framing of the stuck step — not a revenue number. The Latent’s +10% share move on the day and Sigel’s H1 2027 colour on the remaining 150 MW are market and schedule context only.
The second-order read
Who gets paid. Applied Digital — when base rent (and related lease lines) recognize on the delivered halls. CoreWeave — when GPU hours or contracted capacity on those halls bill and perform. Fit-out services, when they run, are a different recognition clock (costs incurred + markup), not proof the 75 MW already cleared as recurring rent.
Who waits. Narratives that treat 250 MW operational or 400 MW contracted as cash already in the bank, that invent rent-per-MW from the May-quarter mix, or that collapse landlord RFS into CoreWeave’s already-collected GPU ASPs. Anyone reading “fully leased” as “fully paid this quarter.”
By clock. RFS print = Applied Digital IR, 2 Oct 2026. Prior operational step = 175 MW after June/July Building 2 phase 1. May-quarter mix = period ended 31 May (pre-dates both 75 MW adds). Settled landlord cash = tenant control + rent recognition. Settled neocloud cash = utilization + billing. Collapse them and MW online looks like paid rent. It clears an RFS bind toward cash. Ready is not paid.
Stuck step. Ready for Service → tenant control / rent conversion → utilization + billing. How cleanly each tranche produces durable lease revenue after handover — while fit-out and construction costs stay contained — is the cash read, not the megawatt headline alone.
Two cautions
75 MW RFS and 250 MW operational are critical-IT-load milestones. Do not invent a disclosed base-rent dollar, fit-out dollar, or incremental TCV for this phase from the October release — it gives none.
Do not treat The Latent’s share move, Sigel’s H1 2027 remaining-MW note, or the May-quarter $44.1M / $152.4M rent/fit-out split as this phase’s settled cash. Label them context. Drop any line that turns “fully leased to CoreWeave” into an invoice already cleared on the new halls.
What would change the view
- A dated earnings or 8-K print that separates base rent vs fit-out for the newer halls — and shows conversion, delay, or slippage.
- Evidence tenant control / possession timing for Building 2 phase 2 lags RFS, or rent recognition stays stuck.
- CoreWeave follow-through: utilization, short-book, or contracted-power prints that do or do not clear on Ellendale capacity.
- Remaining 150 MW delivery hits, slips, or reprices versus the H1 2027 colour.
What to watch
- Applied Digital next earnings — base rent vs fit-out vs recoveries; operating dates behind any change.
- RFS → rent lag — whether later filings name recognition timing for Building 2 phase 2.
- Remaining 150 MW — Building 4 / H1 2027 schedule vs actual RFS.
- CoreWeave IR / capacity — whether Ellendale MW shows up as performing contracted power or billed clusters.
- Lease vs fit-out mix — whether rent becomes the durable line after handover.
Read: Neoclouds, Neocloud explained, Who finances GPU clusters?, and What Is a Take-or-Pay GPU Contract?.
Get the Wire. A free brief every day, here and in your inbox. Subscribe free →
Sources: Applied Digital IR, 2 Oct 2026 — RFS Building 2 phase 2; +75 MW (three 25 MW halls); Building 2 complete at 150 MW; campus operational 250 MW; contracted 400 MW full buildout; Ellendale, ND; Cummins power-to-usable-capacity quote; The Latent (Kyle Baird), 2 Oct 2026 — CoreWeave-leased campus; +10% share move; Sigel remaining 150 MW H1 2027 colour; btw.media (Mara Voss), 2 Oct 2026 — RFS ≠ disclosed revenue; May-quarter HPC Hosting $203.0M = base rent $44.1M + fit-out $152.4M + recoveries $6.5M; 10-K rent recognition tests; FY2026 400 MW CoreWeave leases / Building 4 2027 schedule context; not a new lease. Not investment advice. Do your own research.