CoreWeave's $132.5B backlog waits on 2.9 GW of power
CoreWeave lifted its backlog to $132.5 billion and raised 2026 guidance, but only about 1.7 GW of its 4.6 GW of contracted power is live. Interest was four times operating income, and customers are prepaying about $9 billion to fund the build.

WIRE · NEOCLOUDS · UNITED STATES · Reported 10 Nov 2026 (Livingston, New Jersey)
CoreWeave reported third-quarter revenue of $3.66 billion on Tuesday 10 November, up 168% from a year earlier, and lifted its revenue backlog to about $132.5 billion from about $104 billion in June. It raised its full-year revenue guidance to $13.0 to $13.3 billion. The number that decides when that backlog turns into cash sits further down the release: CoreWeave has more than 4.6 GW of power under contract but just over 1.7 GW switched on. On the Neoclouds layer, roughly 2.9 GW of signed power that is not yet live is the step between a record backlog and paid invoices.
What happened
The quarter
Revenue $3.66bn, operating income $207m, net loss $709m
Net interest expense of $846m was about four times operating income
The backlog
About $132.5bn, up from about $104bn at 30 June
Counted subject to CoreWeave delivering the capacity it promised
The power
Over 1.7 GW live against over 4.6 GW contracted
About 200 MW was added in the quarter; the year-end target stays at more than 1.85 GW
The funding
About $9bn of customer prepayments and deposits due within three months
2026 capex guidance now $37bn to $39bn; Q4 interest guided at $1.05bn to $1.15bn
Why cash cares
A neocloud gets paid when a rack is powered, handed over and running a customer's job. A signed contract only books the promise. CoreWeave's own footnote says as much: the backlog counts revenue "subject to the satisfaction of delivery and availability of service requirements." So the useful question about a $132.5 billion backlog is how fast the power behind it comes on.
The release answers it in two lines. CoreWeave added more than 200 MW of active power in the quarter to reach over 1.7 GW, and grew contracted power by more than 900 MW to over 4.6 GW. That leaves roughly 2.9 GW signed but not live, and only about 37% of contracted power switched on, on our arithmetic. At the third-quarter pace of 200 MW a quarter, the gap would take about 14.5 quarters, or more than three and a half years, to close. CoreWeave expects to do better than that pace over time, and its year-end target of more than 1.85 GW implies only about 150 MW more in the fourth quarter.
Meanwhile the cost of carrying the build is already in the numbers. Net interest expense was $846 million in the quarter, about 4.1 times the $207 million operating income, which is why a quarter with 168% revenue growth still ended in a $709 million net loss. Total debt was about $46.9 billion at 30 September, on our sum of the recourse and non-recourse lines on the balance sheet, and the company guided fourth-quarter interest to $1.05 to $1.15 billion, about 30% above the third quarter at the midpoint.
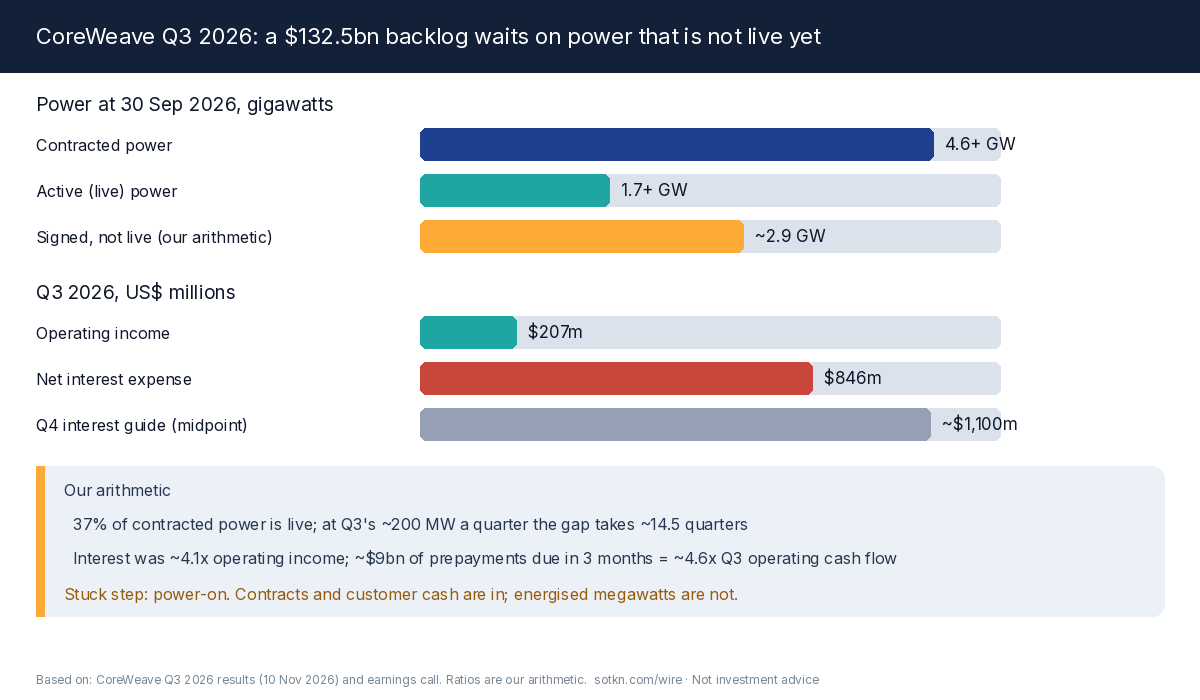
Figure: signed against switched on. Power, revenue, interest and backlog figures are from CoreWeave's 10 November 2026 release. The 2.9 GW gap, the 37% live share, the 14.5-quarter pace and the interest multiple are our arithmetic.
The step that is still open
The stuck step is power-on: turning contracted megawatts into energised halls with racks installed and accepted by the customer. Every step before it, the land, the lease and the GPU order, costs money. Only that last one starts the invoice. CoreWeave said it raised the low end of its 2026 capex range to $37 to $39 billion because it now expects to deploy infrastructure and deliver it to customers sooner than planned. Reuters reported third-quarter capital spending of $14.5 billion, up from $9.4 billion in the prior quarter.
The balance sheet shows how much of that power is rented rather than owned. Operating lease liabilities rose to about $18.7 billion at 30 September from about $8.2 billion at the end of 2025, on our sum of the current and non-current lines. Those are commitments to data centre landlords that run whether or not a hall is energised on time. We looked at what the share price assumes about this step in CoreWeave's power-on problem, and at what high borrowing costs do to neocloud cash in If neocloud debt stays near 1,000 bp.
The second-order read
Who gets paid. Lenders first, and on a rising schedule: $846 million this quarter and about $1.1 billion guided for the next. Data centre landlords next, through leases that more than doubled in nine months. Then the suppliers paid as equipment arrives, with Nvidia's Vera Rubin racks now in production at CoreWeave and a new multi-year SSD supply deal with Solidigm.
Who funds the wait. Increasingly, the customers. On the earnings call, management said it collected prepayments on 70% of its deals this year, in some cases up to the full contract value up front, and expects about $9 billion of prepayments and deposits from signed contracts in the next three months. That is about 4.6 times the $1.98 billion of operating cash flow CoreWeave generated in the third quarter, on our arithmetic. Deferred revenue, the cash customers have paid for service not yet delivered, already stood at about $10.0 billion. If you want the mechanics, our explainer on deferred revenue walks through it.
Who waits. Shareholders, who carry a $709 million quarterly loss while interest rises faster than operating income, and who now face a new at-the-market program for up to 35 million shares. The backlog is about 10 times the midpoint of 2026 revenue guidance, on our arithmetic, so most of it lands years out.
Stuck step. Power-on. CoreWeave has the contracts and, increasingly, the customers' cash. What it is short of is energised megawatts, at about 200 a quarter against a 2.9 GW queue.
Three cautions
The backlog includes estimates of future revenue under committed contracts, not only remaining performance obligations, and it depends on CoreWeave delivering capacity on time. Contract terms, customer concentration and cancellation rights are in the 10-Q, not the release.
The 2.9 GW, 37%, 14.5-quarter, 4.1x, 30%, 4.6x and 10x figures, and the debt, lease and deferred revenue totals, are our arithmetic on reported figures. CoreWeave reports power as "more than" or "over" each number, so the gap is approximate. Power additions are lumpy, and one quarter's pace is not a forecast.
Prepayments are collected on signed contracts, but CoreWeave said it weighs them against the pricing it gives up. Cheaper funding can mean thinner margins later. The share price reaction is not covered here.
What to watch
- Fourth-quarter power adds: whether CoreWeave clears 1.85 GW active by year-end, and by how much.
- The $9 billion: whether prepayments and deposits arrive in the three months as guided.
- Interest against operating income: the Q4 interest bill of about $1.1 billion against adjusted operating income guidance.
- 2027 capex: the CFO said capex would stay in line with 2026 if CoreWeave focused only on committed backlog.
- Nebius on Thursday 12 November: the next neocloud to report, and a check on whether power-on is the shared bottleneck.
Read: the Neoclouds layer, What does CoreWeave do? and Who are the neoclouds?
Get the Wire. A free brief every day, here and in your inbox. Subscribe free →
If this Wire saved you a search, tip Second Order → sotkn.com/support
Not investment advice. Do your own research. The power gap, live share, quarters to close it, interest multiple, prepayment multiple, backlog multiple and the debt, lease and deferred revenue totals are our arithmetic on reported figures.
References
- CoreWeave, "CoreWeave Reports Strong Third Quarter 2026 Results", 10 Nov 2026. Revenue, interest, backlog, active and contracted power, guidance, balance sheet and cash flow.
- Benzinga, "CoreWeave Q3 2026 Earnings Call Transcript", 10 Nov 2026. Prepayments on 70% of deals and the $9 billion due in three months.
- Reuters via Investing.com, "CoreWeave raises revenue forecast as AI demand defies growing doubts", 10 Nov 2026. Quarterly capex of $14.5 billion and total debt.
- CNBC, "CoreWeave Q3 earnings report 2026", 10 Nov 2026. Consensus comparison and CFO comment on 2027 capex.
- Nebius Group, "Nebius Group announces date of third quarter 2026 results and conference call", 30 Oct 2026. Results date of 12 November.