What Does CoreWeave Do? The Neocloud Business Model in Plain English
CoreWeave buys accelerators, funds them with debt, and sells AI compute on multi-year contracts — why the model loses money while growing.
CoreWeave buys AI accelerators, puts them in data centres, and hires out the compute on long contracts. That is the whole business in one sentence — and everything else follows from that model being capital-hungry and front-loaded.
NEOCLOUDS · Data as at 20 Sep 2026 · Next update: after Q3 2026 results
Affects: Neoclouds · Semiconductors · US
It is the largest of the neoclouds: specialist operators who do nothing but supply AI compute, as opposed to a hyperscaler that supplies everything. For the side-by-side, see neocloud vs hyperscaler.
Education only, not advice to buy or sell any security. Figures are from company filings dated as shown.
Numbers that matter
Q2 2026 revenue
$2.58bn
+112% YoY · quarter ended 30 Jun 2026
GrowingContracted revenue backlog
~$104bn
Work sold, not yet delivered · 30 Jun 2026
WatchTotal debt
~$35.1bn
Interest expense $640m in Q2 (~42% of adj. EBITDA)
WatchEquipment spend vs revenue (Q2)
~2.5×
$6.42bn capex vs $2.58bn revenue in the same quarter
Front-loadedActive vs contracted power
1.5 → 3.7 GW
~2.5× headroom contracted, not yet energised
StuckAdj. EBITDA vs net loss (Q2)
$1.51bn / $(626)m
59% adj. EBITDA margin; interest + depreciation close the gap
Gap openSources: CoreWeave Second Quarter 2026 Results (SEC filing), 11 Aug 2026. Status chips are Second Order's read.
Contents: What does CoreWeave actually do? · How does it make money? · Why does it lose money while growing? · What limits growth? · Who else does this? · What would change this view · Practical takeaways · FAQ
What does CoreWeave actually do?
Three steps, in order.
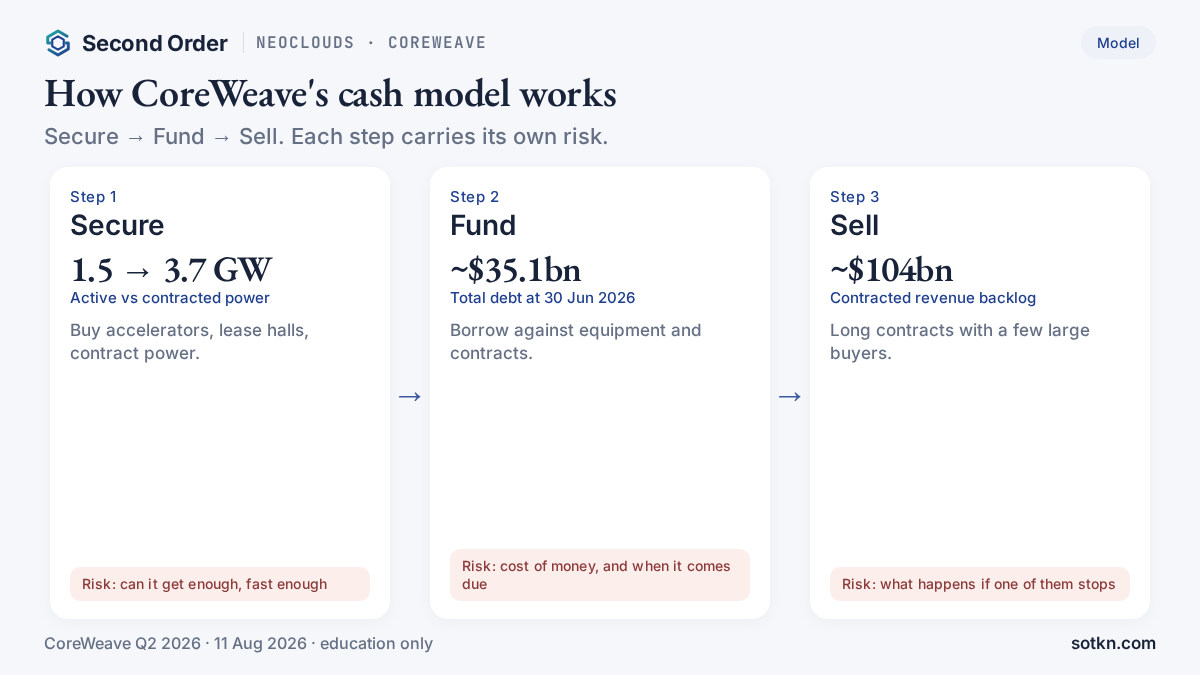
1. It secures scarce things. Accelerators, which are in short supply. Data-centre space. And power — CoreWeave reported roughly 1.5 GW of active power and about 3.7 GW contracted as at 30 June 2026. A later company print put contracted power around 4.2 GW as of 11 August 2026. Power is the constraint that decides how fast it can grow, not demand.
2. It funds them. Accelerators are bought up front and paid for over years. CoreWeave finances that with debt — approximately $35.1bn in total at 30 June 2026, split between recourse borrowing and debt secured against specific contracts.
3. It sells the compute on contracts. Not by the hour to whoever turns up, but on multi-year commitments to large customers. That is what produces the backlog figure: approximately $104bn of contracted revenue at 30 June 2026, with more than $25bn of further commitments reported in early Q3.
| Step | What it means | Where the risk sits |
|---|---|---|
| Secure | Buy accelerators, lease space, contract power | Can it get enough, fast enough |
| Fund | Borrow against the equipment and the contracts | Cost of that money, and when it comes due |
| Sell | Long contracts with a small number of large buyers | What happens if one of them stops |
How does CoreWeave make money?
It gets paid for compute delivered. The margin depends on three things and only three things:
- Utilisation — an idle accelerator costs the same as a busy one, and earns nothing
- Contract length — the longer the contract, the more of the machine's life is paid for before it is obsolete
- The spread between what customers pay and what the power, space and borrowing cost
On the surface the economics look strong. Adjusted EBITDA was $1.51bn in the quarter, a 59% margin.
Underneath, the company still reported a net loss of $626m for the same quarter. That gap is the whole story, and it is worth doing the arithmetic in full.
Our arithmetic. Two things sit between that 59% margin and the bottom line:
| Q2 2026 | As a share of adjusted EBITDA | |
|---|---|---|
| Adjusted EBITDA | $1,510m | — |
| Interest expense | $640m | 42% |
| Reported net loss | $(626)m | — |
Interest alone takes roughly 42% of adjusted EBITDA. The rest of the gap is depreciation — writing down the cost of the accelerators over their assumed useful life. Adjusted EBITDA is stated before both. (Our calculation, from figures in the company's Q2 2026 results, 11 Aug 2026.)
Why does it lose money while growing so fast?
Because it is paying for the machines now and getting paid for them later.
In the quarter ended 30 June 2026, CoreWeave booked $2.58bn of revenue and spent $6.42bn on property, equipment and capitalised software. It spent roughly two and a half times its quarterly revenue on equipment in the same three months.
That is not unusual for this model — it is the model. A company buying assets that earn over five years, while growing at over 100%, will report losses for as long as the growth continues. The backlog is the counterweight: $104bn of contracted work against $35.1bn of debt.
The honest uncertainty. Whether that works depends on something nobody outside the company can see precisely: how long an accelerator keeps earning before it is displaced by a better one. If the useful life assumed in the accounts is right, the contracts repay the debt comfortably. If accelerators are displaced faster than assumed, depreciation is understated and so are the losses. This is the single most argued-over number in the sector, and we are not going to pretend to settle it.
What limits how fast CoreWeave can grow?
Power, not demand — and the company's own numbers show it.
CoreWeave reported roughly 1.5 GW of active power at 30 June 2026, having added nearly 500 MW to get there, against approximately 3.7 GW contracted. A later print, as of 11 August 2026, put contracted power around 4.2 GW.
Our arithmetic. Contracted power is about 2.5 times what is live today. Put another way, the company has already secured the electricity for roughly two and a half times its current operating footprint, and the job now is turning contracts into energised halls.
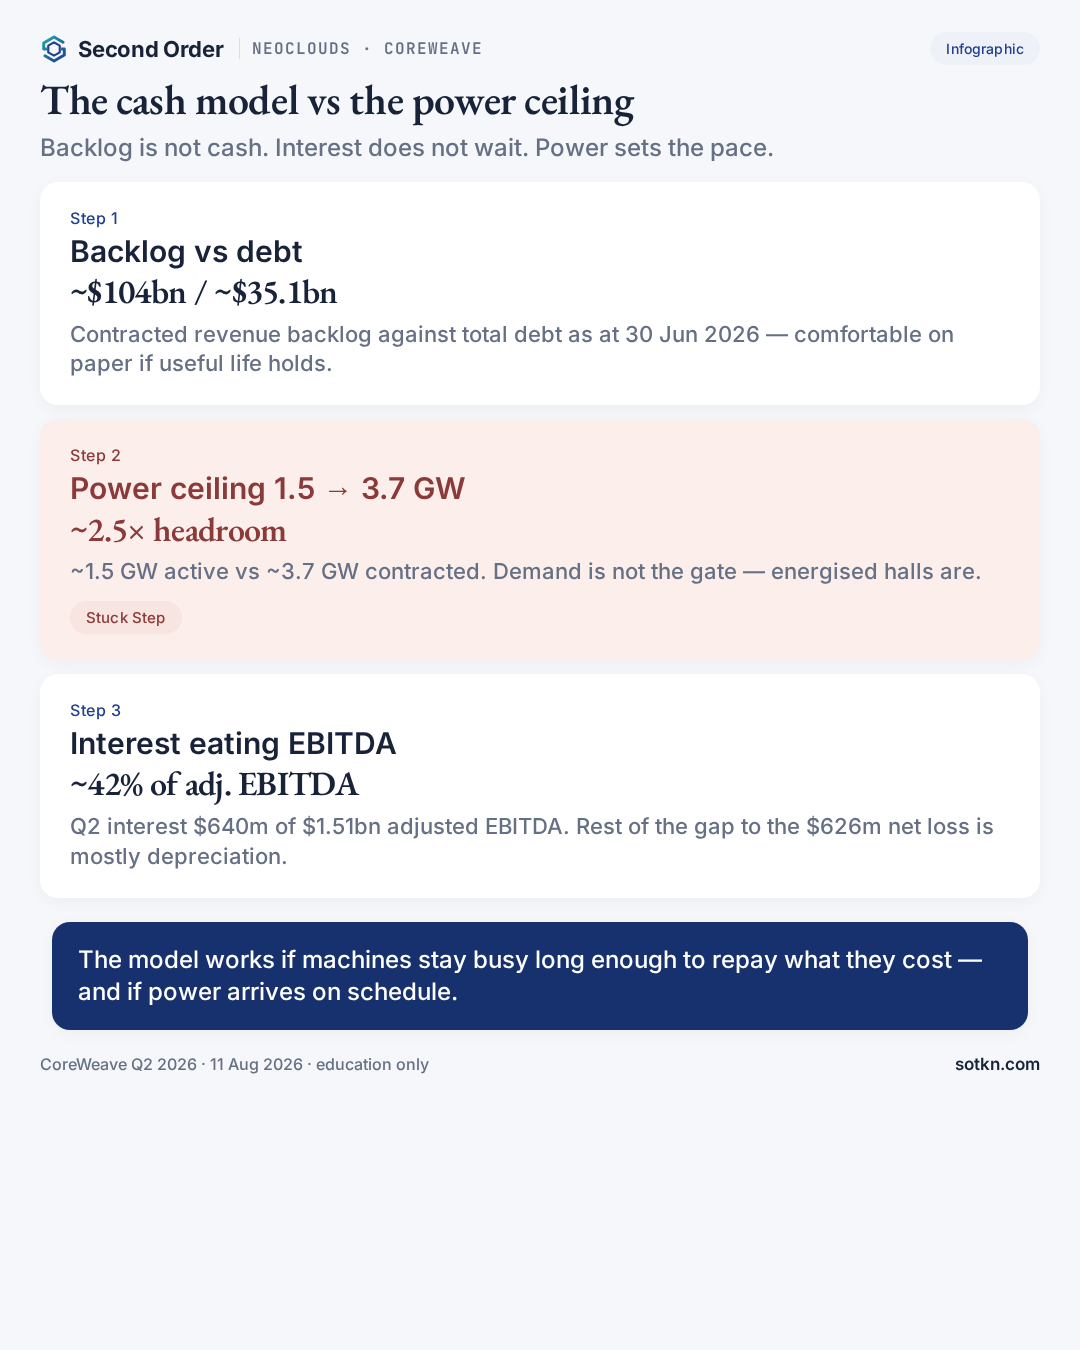
That is the real growth ceiling, and it is the reason the backlog figure and the revenue figure move at different speeds. A contract signed today cannot be served until there is a hall with power in it. Accelerators can be bought in quarters; a data hall with grid power behind it usually cannot.
It also explains why a neocloud looks capital-hungry in a way a software business never does. The spending happens when the site is built and the machines are installed. The revenue starts when the hall is switched on. Between those two dates the company carries the cost and earns nothing on it — and at this rate of growth, there is always a large tranche of capacity sitting in that gap.
Who else does this?
Roles, not a league table.
| Company | What it does | What makes it different |
|---|---|---|
| CoreWeave | Largest specialist AI compute supplier | Scale, and the largest contracted backlog |
| Nebius | Specialist AI compute, European roots | Different geography and funding history |
| Applied Digital | Builds and operates the sites | Closer to the landlord end than the compute end |
| Hyperscalers | Supply compute among everything else | Own balance sheets, own chips, not dependent on this one product |
The question that separates them is not who has the most accelerators. It is who has the longest contracts, the cheapest money, and the most power already connected.
What would change this view?
The read on the model weakens if:
- Contract prices falling as more capacity arrives, compressing the spread
- A large customer not renewing, or reducing a commitment — concentration cuts both ways
- Borrowing getting more expensive, or debt coming due faster than contracts pay
- Accelerators being displaced faster than the assumed useful life, which would understate depreciation
- Hyperscalers taking the overflow demand back in-house, which is where it came from
- Power arriving faster than expected, which would be the one that helps
It stays intact while backlog covers debt on paper, interest eats a large share of adjusted EBITDA, and energised power lags contracted power.
Practical takeaways
- CoreWeave's whole model is Secure → Fund → Sell: buy scarce machines, borrow against them, sell multi-year compute
- Q2 2026: $2.58bn revenue (+112%), ~$104bn backlog, ~$35.1bn debt — growth is real and capital-hungry
- Interest alone takes ~42% of adjusted EBITDA; the net loss is mostly interest plus depreciation
- Power, not demand, is the growth ceiling — ~1.5 GW live vs ~3.7 GW contracted
- The open question is useful life: whether contracts repay the machines before they are displaced
FAQ
What does CoreWeave do?
CoreWeave buys AI accelerators, houses them in data centres, and sells the compute to customers on multi-year contracts. It is a specialist supplier of AI computing capacity and does not sell general software or consumer services.
What does CoreWeave do in simple terms?
It owns the expensive machines that train and run AI models, and charges other companies to use them.
Is CoreWeave profitable?
Not on a reported basis. It posted a net loss of $626m in the quarter ended 30 June 2026 while reporting $1.51bn of adjusted EBITDA on $2.58bn of revenue. The difference is mostly interest and depreciation.
How is CoreWeave different from a hyperscaler?
A hyperscaler sells storage, databases, software and compute, funds it from its own cash, and increasingly designs its own chips. CoreWeave sells AI compute only and funds it with debt. See hyperscaler, explained.
What is CoreWeave's backlog?
Approximately $104bn of contracted revenue as at 30 June 2026 — work customers have committed to but that has not yet been delivered or recognised as revenue.
Should I buy CoreWeave shares?
We do not make buy or sell calls, and nothing here is a recommendation. What we can tell you is what the company does, how it gets paid, and which figures would change the picture. The decision is yours.
Keep reading on the map
- The layer: Neoclouds — how this part of the build chain works
- The term: Neocloud, explained
- What they buy: Semiconductors — why accelerators are hard to get
- Where it happens: the US — power is the constraint on growth
Members' Analysis: can the contracts repay the debt before the machines are obsolete?
The free part: $104bn of contracted backlog against $35.1bn of debt is a comfortable ratio on paper — but only if the assumed useful life of an accelerator holds.
The free half stays here. The members cut on the power clock is already live: Where does the stuck step move?. This page stays the free Stack read of the CoreWeave model.
Get the Wire
Free daily brief on what changed in the AI chip map. Subscribe free →
Sean
Writes Second Order by TKN — a plain-English map of AI infrastructure and semiconductors for non-specialist investors. Focus: who gets paid, where money sticks, and which step is stuck. Not investment advice.
Covers AI infrastructure, semiconductors, and second-order stack reads.
Author page → · Editorial standards →
How we check this
Figures come from company filings and government releases, each dated in the list below. Capacity and timing from press reports are labelled as reported, not guided. Where we work something out ourselves, the arithmetic is shown in full.
Last reviewed: 23 Sep 2026 · Next review: after Q3 2026 results
Spot an error? Tell us and we will correct it and note the change here.
Our editorial standards →
Sources
- CoreWeave, Second Quarter 2026 Results (SEC filing), 11 Aug 2026 — revenue, backlog, net loss, adjusted EBITDA, capital expenditure, debt, interest expense, active and contracted power
- CoreWeave / Business Wire, CoreWeave Continues to Contract New Compute at Higher Prices (17 Sep 2026) — ~$40m/MW short-dated Q3 contracts; contracted power around 4.2 GW as of 11 August 2026
All external links rel="nofollow noopener".