
SK hynix drops a $15B Solidigm IPO but keeps the US NAND fab plan
SK hynix ended Solidigm's IPO review on 23 October. The reported $15 billion raise is off, the US fab for data center SSDs is still needed, and no site or size has been named.
WIRE · SEMICONDUCTORS · SK HYNIX · Data as at 24 Oct 2026
SK hynix has stopped looking for outside money to build Solidigm a new factory. On 23 October 2026 it said Solidigm, its US-based maker of data center SSDs, has dropped its review of a pre-IPO round and a US listing, citing market volatility and the fall in chip shares. People familiar with the plan had told Reuters the listing could have raised about $15 billion at a value of up to $150 billion. The fab itself is still on: SK hynix says Solidigm's current plants cannot keep up with AI storage demand and that it still needs a new US fab. On the semiconductors layer, the bill for new data center flash capacity now sits with the parent.
What happened
23 October 2026 · SK hynix newsroom
Pre-IPO and IPO review discontinued
SK hynix said the decision "does not reflect any change in Solidigm's growth prospects or investment needs". It will keep reviewing the timing, size and financing of the investment
The money that is not coming
About $15 billion for roughly a tenth of Solidigm
Reported, not confirmed by the company. SK hynix said the cash would have eased the fab bill and left more room for buybacks and dividends
The pressure
Shares down 31% since the listing talk began
Against a 20% fall in the KOSPI over the same stretch. Korea's Financial Supervisory Service had also said it was checking whether the listing needed review under dual-listing rules tightened in July
The fab
Still needed, still unsized
No site, capacity, cost or start date has been given. In September, Korean and US reports named the US East Coast, possibly upstate New York, as the area under review
Why cash cares
Solidigm sells the very large QLC drives that cloud buyers now put behind AI servers to hold data and offload memory. TrendForce put the top five enterprise SSD makers' revenue at $37.59 billion in the second quarter, up 103.6% in one quarter, with SK hynix and Solidigm together second at more than $8.63 billion. That is about $34.5 billion a year at the second-quarter pace (our arithmetic). In September TrendForce said US cloud companies had raised their SSD forecasts again and that fourth-quarter orders could top the third quarter's.
The catch is where Solidigm makes its flash. Its chips come from the former Intel plant in Dalian, China, on an older 192-layer design. US export rules make it hard to bring the newest tools into that plant, so the extra capacity has to be built somewhere else. A modern NAND fab costs tens of billions of dollars, so the $15 billion would have covered a large part of one.
Now SK hynix pays for it from its own cash and debt, or waits. It can afford to: brokerages expect its cash to reach about 456 trillion won, or $344 billion, by the end of 2027, according to Korea's Corporate Governance Forum. On that estimate, the lost IPO money is about 4% of the cash pile (our arithmetic). The open question is how fast it chooses to spend.
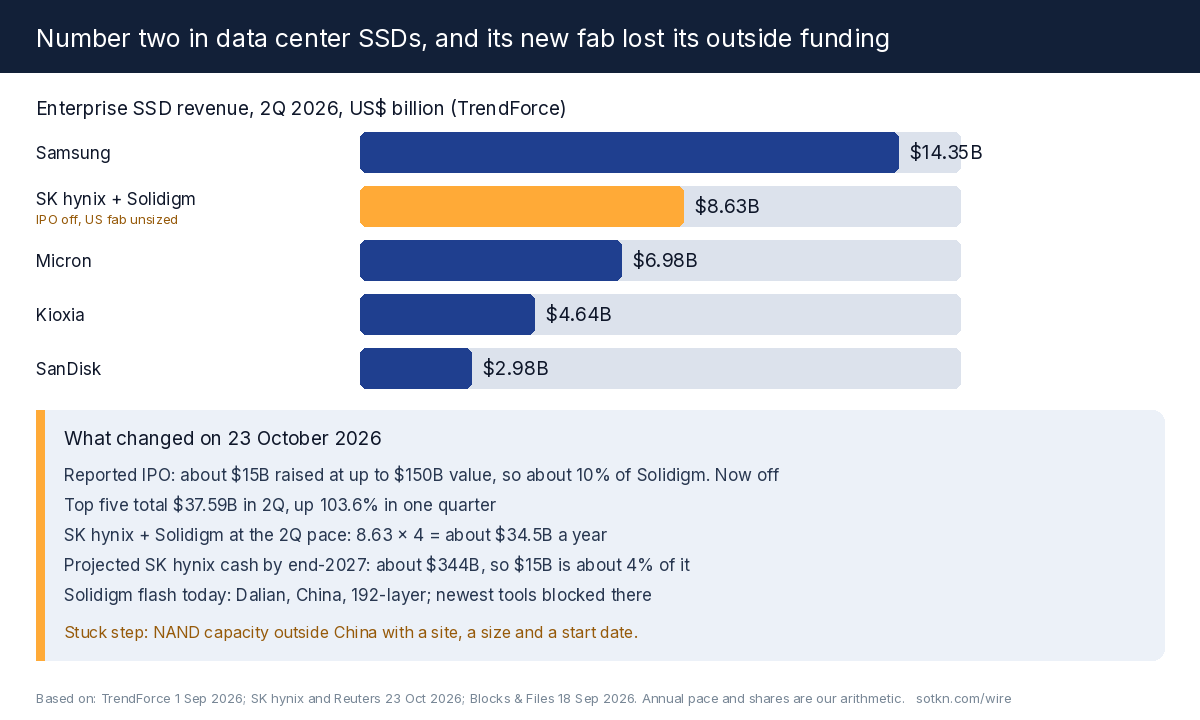
Figure: SK hynix and Solidigm are the number two seller of data center SSDs, and their new capacity now has no outside funding. Revenue from TrendForce for the second quarter of 2026; IPO figures as reported by Reuters on 23 October 2026.
The second-order read
Who gets paid. SK hynix shareholders first, in the narrow sense: they keep all of a business selling into a market that doubled in a quarter, and avoid a sale at a price SK hynix itself says was too low. Then the rivals with flash capacity already running outside China, Samsung, Micron, Kioxia and SanDisk, because every month the Solidigm fab is not built is a month they set prices with less competition for QLC drives.
Who waits. The toolmakers and builders behind a new US NAND fab. Etch, deposition and cleanroom orders come only once a site and a budget are fixed, and neither is. The state that wins the plant waits too.
Who pays more. Cloud buyers of large SSDs. Rising orders with no new outside-China QLC capacity on a fixed date keeps contract prices firm.
Stuck step. New NAND capacity outside China for Solidigm's drives. Demand is not the problem, and neither is SK hynix's cash. The step that is stuck is a fab with a site, a size and a start date. We covered the same Dalian limit when SK hynix weighed upgrading the plant.
Two cautions
The $15 billion and $150 billion figures came from people familiar with the plans, not from SK hynix, and no price was ever set.
SK hynix may still build on time. Dropping the IPO changes who pays, not whether the fab is needed, and the company says the investment need is unchanged. The risk is a slower start, not no start.
What would change the view
- SK hynix naming a US site, a capacity and a budget for the Solidigm fab, which would turn a plan into orders.
- A different outside funding route, such as a private stake sale or project financing, which would show the market price for Solidigm without a listing.
- Enterprise SSD prices turning down, which would weaken the case for any new NAND fab, funded or not.
What to watch
- SK hynix third-quarter results on 28 October, for capex plans, NAND spending and any detail on Solidigm.
- Samsung's full third-quarter results, due later this month, for its own enterprise SSD capacity and pricing.
- US–Korea chip talks, since reports say SK hynix has tied a US fab to approval for more tools at its China plants.
Read: the semiconductors layer and the hyperscalers layer
Get the Wire. A free brief every day, here and in your inbox. Subscribe free →
Not investment advice. Do your own research. The $34.5 billion and 4% figures are our arithmetic from TrendForce's second-quarter revenue and the reported cash estimate.
References
- SK hynix Newsroom, "Solidigm to Discontinue Review of Potential IPO, Reaffirming Commitment to Long-Term Growth and Shareholder Value", 23 Oct 2026
- Reuters via Yahoo Finance, "SK Hynix puts US IPO of chip unit Solidigm on hold after Seoul authorities raise concerns", 23 Oct 2026
- Tom's Hardware, "Solidigm confirms plans to build a fab in the US, abandons IPO plans", 23 Oct 2026
- TrendForce, "Top Five Enterprise SSD Vendors' Revenue to Nearly US$37.59 Billion in 2Q26", 1 Sep 2026
- TrendForce, "Stronger North American Demand to Keep Enterprise SSD Prices on an Upward Trend in 4Q26", 21 Sep 2026
- Blocks & Files, "SK Hynix considering US Solidigm fab", 18 Sep 2026


