Broadcom’s banks start raising $60B for AI chips
Bloomberg (2 Oct): banks assembling ~$60B AI chip financing ($42B senior, $18B Blackstone junior) for Anthropic and others. Raise talk is not settled cash.
WIRE · HYPERSCALERS · US · Data as at 2 Oct 2026
Bloomberg reported on 2 October 2026 that Broadcom’s bank syndicate is starting to gather about $60 billion of fresh AI-chip financing to benefit Anthropic and other companies — a $42 billion Class A senior-secured tranche with syndication letters imminent, plus an $18 billion Class B junior led by Blackstone. On the hyperscalers layer, a financing package being assembled is ready talk. It is not cleared chip revenue or settled lease cash until syndication closes, racks ship, and lease payments clear. Ready is not paid.
What happened
On 2 October 2026, Bloomberg (via Economic Times, Company Chronicle, and Bloomberg Law) reported that banks working with Broadcom — including Bank of America, Citigroup, and Morgan Stanley per Bloomberg Law — are beginning to assemble roughly $60 billion of new AI-chip financing that would benefit Anthropic and other companies. The package has not been announced. Broadcom declined to comment to Bloomberg.
Structure as reported:
Event
Banks start gathering ~$60B AI chip financing (reported)
Bloomberg, 2 Oct 2026 — deal not announced; Broadcom declined comment
Class A (senior)
$42B senior-secured — syndication letters imminent
Bloomberg / Bloomberg Law — BofA, Citi, Morgan Stanley among banks named
Class B (junior)
$18B junior led by Blackstone; ~$9B from own funds, rest syndicated
Bloomberg, 2 Oct 2026
Reported backstop (senior)
Broadcom residual-value support / backstop on senior portion
Bloomberg Law — reported structure, not a closed syndication print
Beneficiaries (reported)
Anthropic and other companies — chip / AI infrastructure access
Bloomberg — not a named closed offtake schedule
Separate instrument (1 Oct)
Broadcom may lend Anthropic up to $42B (convertible notes) — prospectus / Reuters
Reuters 1 Oct — NOT the same as the $42B Class A senior tranche
Lease context (filing / Reuters)
Facility could cover ~1/3 of Anthropic’s $125.2B five-year TPU lease commitment
Reuters on Anthropic IPO prospectus — notes not expected sold before IPO
Stuck step named
Syndication close → rack deployment → lease performance
Opening financing talk ≠ settled invoice
Do not treat ~$60 billion as Broadcom borrowing on its own balance sheet, as a closed syndication, or as cleared chip revenue. The $42 billion Class A senior tranche (outside lenders) is a different instrument from the up-to-$42 billion convertible-note facility disclosed in Anthropic’s prospectus and mirrored (unnamed customer) in Broadcom’s 10-Q. Same figure, two seats.
Why cash cares
On the hyperscalers layer, cash for financed AI racks clears when hardware ships, leases are drawn, and lease payments perform — see Who finances GPU clusters? and Hyperscaler explained. A bank package “starting to gather” is ready capital talk. It is not yet paid. That gap is the whole Wire: Bloomberg can date the raise on 2 October, and Broadcom can still be waiting on syndication close, deployment, and customer draw when the letters go out.
Two cash clocks:
- Raise vs clear. ~$60B ($42B senior + $18B junior) is the reported package size. Cash for Broadcom’s chip seat moves when financed racks ship and customers draw — not when syndication letters are drafted. Lenders get paid if lease payments clear; they wait if the junior or senior slice fails to place, or if deployment slips.
- Two $42B instruments. Reuters (1 Oct) tied a Broadcom convertible-note facility of up to $42B to Anthropic’s IPO prospectus — enough, on Reuters’ read, to finance about one-third of a $125.2 billion five-year TPU lease commitment. Broadcom’s Form 10-Q (quarter ended 2 August) already described an unnamed customer that may issue up to $42B of convertible notes for lease obligations; none issued as of 2 August. Bloomberg’s $42B Class A is a senior-secured tranche sold to outside lenders. Collapse the two and the headline looks like one settled $42B loan. It is not.
Company Chronicle’s 10-Q read is useful context, not confirmation that today’s ~$60B sits inside Broadcom’s AI XPV platform: June launch with an initial ~$35 billion financial-partner tranche, aim >20 GW through 2028, and a first-deployment backstop of about $29 billion undiscounted — nothing paid as of the filing. Bloomberg did not say the new package is inside XPV; treat the shape as matching, not confirmed. Ready is not paid.
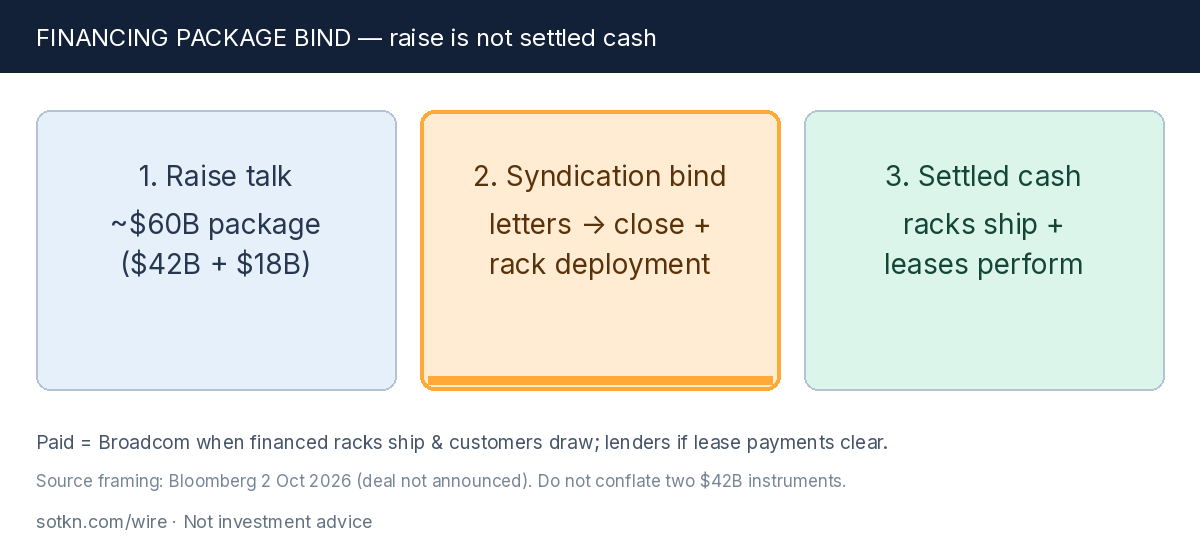
Figure — Financing package bind. Syndication letters / raise talk → close + rack deployment → lease performance. Amber only on the raise / syndication bind. Paid = Broadcom when financed racks ship and customers draw; lenders if lease payments clear.
Context: XPV, backstop, and the convertible seat
Broadcom’s Form 10-Q for the quarter ended 2 August 2026 (Company Chronicle summary of the SEC filing) puts two exposures next to each other for an unnamed customer: the convertible-note ceiling, and a lease backstop on the AI XPV platform’s first deployment. The partner buys racks on Broadcom-designed custom accelerators and leases them for five years; Broadcom backstops lease payments. Maximum potential liability once those racks deploy: about $29 billion undiscounted. Paid under the backstop as of the filing: nothing.
Even when the debt is not Broadcom’s own borrow, chip revenue can print when financed capacity ships while contingent lease risk sits in the backstop — and in any residual-value support Bloomberg Law attributes to the new senior tranche. Whether Broadcom guarantees any part of the new ~$60B is open; do not invent it from the $29B first-deployment figure. Prior disclosure still frames a separate compute clock: Anthropic–Broadcom–Google roughly 3.5 GW of next-gen TPU capacity from 2027. Capacity commitments and financing packages are different clocks.
The second-order read
Who gets paid. Broadcom — if financed racks ship and customers draw. Outside senior lenders — if Class A places and lease cash clears ahead of junior. Blackstone and Class B — if the junior places and holds its seat. Anthropic and other beneficiaries get access when capacity deploys; that is not Broadcom’s invoice clearing.
Who waits. Narratives that treat ~$60B as Broadcom’s own borrow, a closed syndication, or settled chip revenue — or that merge Bloomberg’s $42B Class A with Reuters’ $42B convertible-note facility. Anyone treating residual-value support or the XPV $29B backstop as cash already paid (filing: nothing paid on the disclosed backstop).
By clock. Raise talk = Bloomberg, 2 Oct. Convertible facility = Reuters / prospectus, 1 Oct (10-Q as of 2 Aug: notes not issued). Syndication letters = imminent, not closed. Settled cash = racks ship + leases perform. Collapse them and financing talk looks like a settled invoice. It clears a syndication bind toward cash. Ready is not paid.
Stuck step. Syndication close → rack deployment → lease performance. How cleanly the remaining ~$9B junior and the $42B senior place is the credit market’s near-term read — not Broadcom’s already-booked revenue.
Two cautions
The ~$60 billion package is reported by Bloomberg from people with knowledge of a deal that has not been announced. Broadcom declined comment. Do not invent a closed syndication, a named offtake schedule, or Broadcom borrowing $60B on its own balance sheet.
Do not conflate the $42 billion Class A senior-secured tranche (outside lenders, Bloomberg 2 Oct) with the up-to-$42 billion convertible-note facility (Anthropic prospectus / Reuters 1 Oct; Broadcom 10-Q unnamed customer, none issued as of 2 Aug). Same number, different instruments. Drop any secondhand line that merges them into one settled loan.
What would change the view
- A dated announcement that the ~$60B package closed — tranche sizes, pricing, and whether Broadcom residual-value support is confirmed in a filing.
- Evidence the senior or junior syndication slips, reprices, or fails to place.
- A 10-Q / 8-K that states whether the new package sits inside AI XPV and what backstop, if any, attaches to the new money.
- Convertible notes issued (or a dated statement they will not be) against the Anthropic lease commitment.
- Deployment prints: financed racks shipped, GW online, or lease-payment stress that hits the backstop.
What to watch
- Syndication letters and close through October 2026 — any dated “closed” or “upsized / downsized” language on Class A or Class B.
- Blackstone junior placement — whether the remaining ~$9B syndicates cleanly (appetite read for AI hardware debt).
- Broadcom next 10-Q / earnings — AI XPV, backstop balances, convertible-note issuance, residual-value support language.
- Anthropic IPO / prospectus follow-through — lease commitment, Broadcom dual-role conflict language, note-sale expectations.
- Deployment clock — 2027 ~3.5 GW Anthropic–Broadcom–Google capacity vs whether financed racks actually ship into that window.
Read: Hyperscalers, Who finances GPU clusters?, and Hyperscaler explained.
Get the Wire. A free brief every day, here and in your inbox. Subscribe free →
Sources: Bloomberg Law, 2 Oct 2026 — ~$60B package; $42B Class A syndication letters; banks named; residual-value support on senior; Economic Times carrying Bloomberg, 2 Oct 2026 — $18B Class B / Blackstone $9B commit; deal not announced; Company Chronicle, 2 Oct 2026 — off-balance read; XPV / $35B first tranche context; two $42B instruments distinguished; Reuters, 1 Oct 2026 — Anthropic prospectus: Broadcom up-to-$42B convertible facility; ~1/3 of $125.2B five-year TPU lease; Company Chronicle, 1 Oct 2026 — Broadcom 10-Q (qtr ended 2 Aug): convertible ceiling unused; XPV backstop ~$29B undiscounted, nothing paid. Not investment advice. Do your own research.