Micron locks over 75% of 2027 memory output
Micron (1 Oct outlook): >75% of FY2027 output committed; memory stays tighter through 2028. Locked SCA / RPO volume is not settled cash.
WIRE · SEMICONDUCTORS · US · Data as at 1 Oct 2026
Micron reported record fiscal fourth-quarter results and said memory supply-demand will stay much tighter in calendar 2027 and 2028 than in 2026, with more than 75 percent of fiscal 2027 output already committed and the vast majority of calendar 2027 HBM bit supply sold at prices much higher than 2026. On the semiconductors layer, committed volume and rising RPOs are ready book. They are not settled cash until wafers ship and invoices clear. Ready is not paid.
What happened
On 30 September 2026, Micron reported fiscal fourth-quarter and full-year 2026 results (quarter ended 3 September 2026). Korea Herald and Aju Press carried the outlook on 1 October 2026: shortage deepens through 2027–2028, lock-ins accelerate, and calendar 2027 HBM is largely spoken for at higher prices.
Print as reported:
FQ4 revenue
$54.23B — record; nearly 5× YoY from $11.32B; +31% QoQ
Micron IR 30 Sep 2026; Aju Press 1 Oct 2026
Non-GAAP operating income
$44.64B — operating margin 82.3%
Micron IR / Aju Press — Non-GAAP
Current-quarter guide
Revenue $61.5B ± $1.5B; adj GM ~86.25%; adj EPS $38.15 ± $1
Micron FQ1-27 outlook — IR / Aju
Outlook (Mehrotra)
Supply-demand much tighter in calendar 2027 and 2028 than 2026; no line of sight to balance
Aju Press / Korea Herald, 1 Oct 2026 — demand exceeds supply both years
Fiscal 2027 commitment
>75% of total fiscal 2027 output already committed; talks shifting to 2028
Korea Herald / Aju Press, 1 Oct 2026
Strategic customer agreements
26 SCAs (from 16 in June); expected >35% of revenue through 2030; related commitments $32B (from $22B)
Korea Herald / Aju — some agreements extend through 2031
Remaining performance obligations
~ $150B RPO (from ~$100B prior quarter)
Aju Press, 1 Oct 2026 — contracted revenue yet to be recognized
2027 HBM
Vast majority of calendar 2027 HBM bit supply completed at prices much higher than 2026
Mehrotra via Aju — large part of 2027 HBM volume already sold out
Stuck step named
Commitment → fab ramp + shipment → invoice performance
75% locked / $32B commitments / $150B RPO ≠ settled cash
Do not treat >75% committed output, $32 billion SCA commitments, or ~$150 billion RPO as cash already in the bank. Contracted and “sold” HBM volume still has to ship and clear invoice.
Why cash cares
On the semiconductors layer, memory cash clears when wafers leave the fab, bits ship, and customers pay — see What Is HBM? and Who Makes HBM?. A Strategic Customer Agreement and a rising RPO balance are ready book. They are not yet paid. That gap is the whole Wire: Micron can date a record quarter and a sold-out 2027 HBM book, and cash still waits on fab ramp, shipment, and invoice.
Two cash clocks:
- Committed vs settled. More than 75 percent of fiscal 2027 output is already committed; talks are moving into 2028. SCAs rose to 26 from 16 in June; related commitments sit at $32 billion (from $22 billion). RPO is about $150 billion (from about $100 billion). Those figures are contracted and recognized later — not this quarter’s invoice for 2027–2028 bits.
- HBM sold vs HBM paid. Mehrotra said a large part of calendar 2027 HBM volume is already sold out at prices much higher than 2026. Higher contracted ASP is not cash until bits ship and the invoice clears. TrendForce’s 29 September read that 2027 HBM blended ASP rises +121% YoY is context on the pricing path — not Micron’s settled cash for 2027.
Idaho’s first expansion wafer output around mid-2027 is also context: new cleanrooms ease shortage only as wafers ramp, not when the commitment is signed. Ready is not paid.
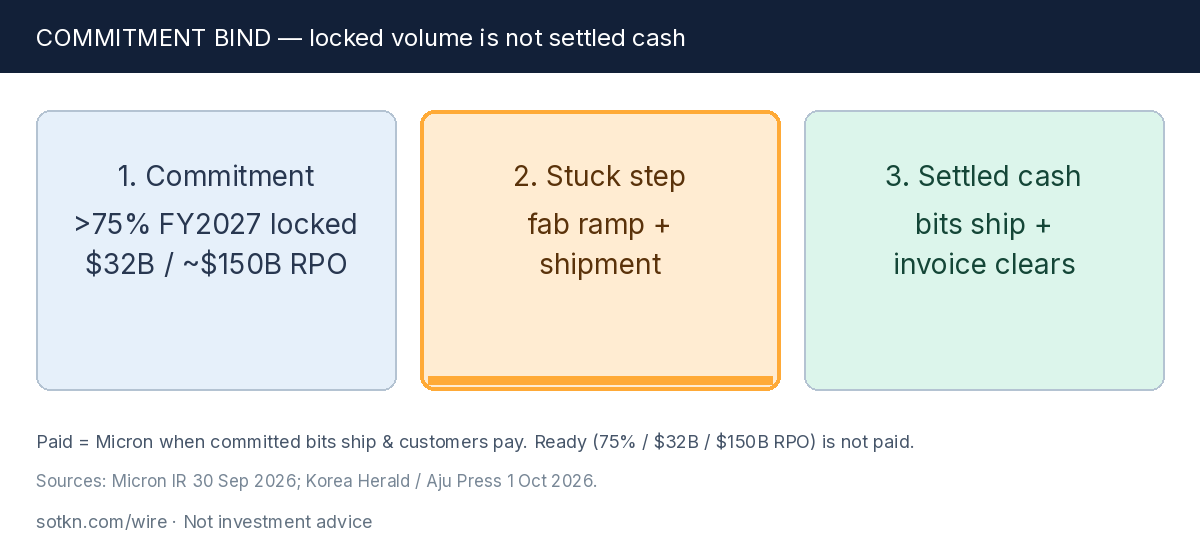
Figure — Commitment bind. SCA / RPO / sold HBM → fab ramp + shipment → invoice. Amber on the bind. Paid = Micron when bits ship and customers pay.
Context: peers, ASP path, and fab timing
Context, not today’s Micron print. Samsung said in July the shortage could persist through 2028, with LTAs signed with five major data-center customers and talks near completion with another five — potentially 60–70 percent of medium- to long-term memory capacity if completed (Korea Herald). SK hynix said the same month it had completed talks with about 10 customers on contracts generally around five years. TrendForce on 29 September raised its 2027 HBM blended ASP forecast to +121% YoY. Micron’s Idaho first-expansion wafer output is expected around mid-2027, with output rising only gradually after cleanrooms start (Aju). Peer LTAs and the ASP path frame the same shortage clock; they do not turn Micron’s >75% commitment into settled cash.
The second-order read
Who gets paid. Micron — when committed fiscal-2027 bits ship and invoices clear. Peers on the same shortage clock — when their LTA / HBM shipments perform. Customers get allocation when wafers ship; that is not Micron’s cash clearing early.
Who waits. Narratives that treat >75% committed, $32B SCA commitments, ~$150B RPO, or “sold out” 2027 HBM as cash already booked for 2027–2028. Anyone collapsing contracted ASP into this quarter’s settled invoice.
By clock. FQ4 print = Micron IR, 30 Sep (ended 3 Sep). Outlook = earnings call / Korea Herald / Aju, 1 Oct. Settled cash for 2027–2028 committed volume = fab ramp + shipment + invoice. Collapse them and a locked book looks like paid cash. It clears a commitment bind toward cash. Ready is not paid.
Stuck step. Commitment → fab ramp + shipment → invoice performance. How cleanly ramps hit wafer output — and invoices clear — is the cash read, not the commitment percentage alone.
Two cautions
>75 percent committed fiscal-2027 output, $32 billion SCA-related commitments, and ~$150 billion RPO are contracted figures. Do not invent closed ASPs for every 2027–2028 bit or treat RPO as cash already collected.
Do not treat TrendForce’s +121% 2027 HBM ASP path, Samsung’s July LTA path, or SK hynix’s ~10 five-year LTAs as Micron’s settled cash. Label them context. Drop any line that turns “sold out” HBM into a cleared invoice.
What would change the view
- A dated shipment or revenue print that shows fiscal-2027 committed volume converting to recognized sales — or slipping.
- Evidence SCA / RPO balances reprice, cancel, or stretch past the stated window.
- Idaho mid-2027 wafer start hits, delays, or ramps slower than gradual.
- Peer LTA / HBM prints that loosen or tighten the shared shortage clock into 2028.
What to watch
- Micron next quarter — guide and commitment language on tighter 2027–2028.
- SCA / RPO trajectory — commitment dollars vs recognition into revenue.
- 2027 HBM shipments — sold volume converting at higher contracted prices.
- Peer earnings — Samsung / SK hynix LTA coverage vs TrendForce’s +121% ASP path.
- Idaho fab ramp — mid-2027 wafer start and gradual output, not the commitment headline alone.
Read: Semiconductors, What Is HBM?, Who Makes HBM?, and Memory process tools for HBM.
Get the Wire. A free brief every day, here and in your inbox. Subscribe free →
Sources: Micron IR, 30 Sep 2026 — FQ4 revenue $54.23B; Non-GAAP OI $44.64B / 82.3% OM; FQ1-27 guide $61.5B ± $1.5B, adj GM ~86.25%, adj EPS $38.15 ± $1; Korea Herald, 1 Oct 2026 — much tighter 2027–2028; >75% FY2027 output committed; 26 SCAs / $32B commitments / >35% revenue through 2030; Samsung July LTA path; SK hynix ~10 × ~5-year LTAs; Aju Press, 1 Oct 2026 — +31% QoQ; no line of sight to balance; RPO ~$150B; 2027 HBM mostly sold at much higher prices; TrendForce 29 Sep HBM ASP +121% YoY; Idaho mid-2027 wafer context. Not investment advice. Do your own research.