$18,517 Million Invoiced: Who Gets Paid While Cisco's AI Line Stays Off the Row
Cisco was paid on networking already invoiced. The $9 billion hyperscaler AI figure is a year-long expectation, and this quarter has no row for it.
Cisco was paid on networking it has already recognised. The stuck step is the AI dollar. The results furnished on 12 November 2026 print a $9 billion hyperscaler AI expectation for the full year, and the quarter just closed has no row for it.
US PULSE · Data as at 17 Nov 2026 · Next update: after a quarter that prints hyperscaler AI infrastructure revenue on its own line
Affects: Hyperscalers — Markets: US · Korea · Taiwan
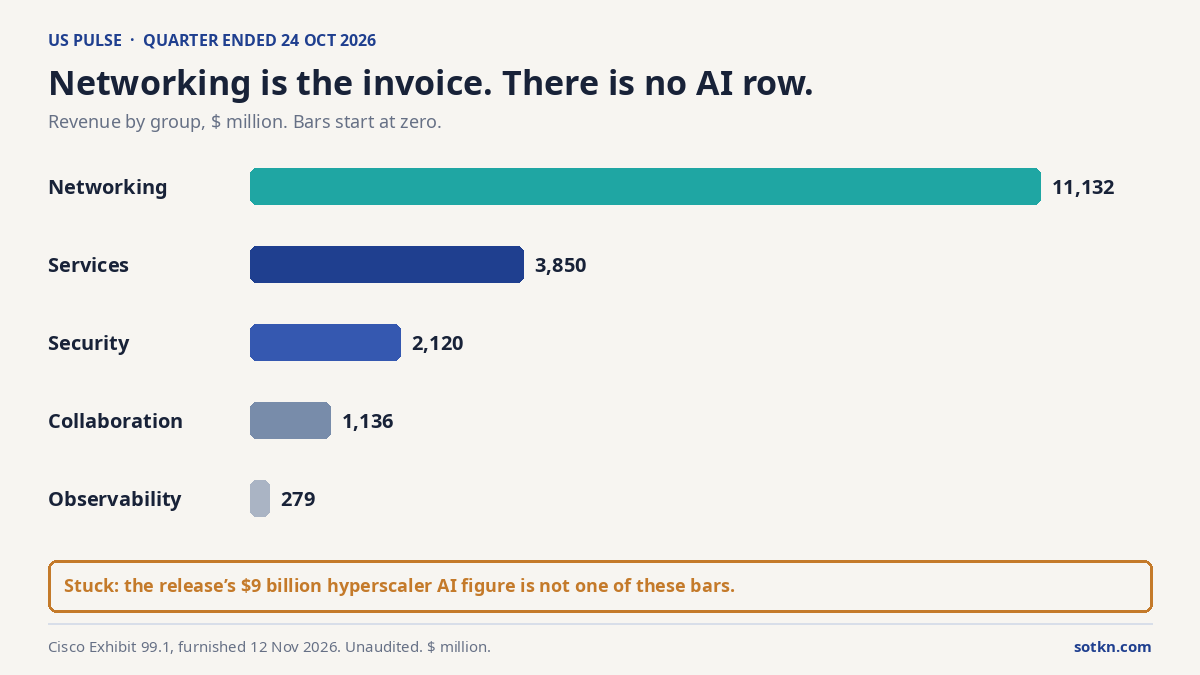
In short: For the quarter ended 24 October 2026, Cisco recognised revenue of $18,517 million. Networking was $11,132 million of that. Who gets paid is Cisco, on switches and the rest of the network already in the books. The $9 billion figure is a full-year expectation. It is not a line in this quarter.
Education only, not advice to buy or sell any security. Figures are from Exhibit 99.1 to the Form 8-K furnished on 12 November 2026, for the quarter ended 24 October 2026. The statements are unaudited. The income statement is in millions of dollars. Any division below is our arithmetic. A rounded billion in the prose is not a substitute for the table cell.
The numbers that matter this month
The release leads with a rounded $18.5 billion. The income statement prints $18,517 million. Use the cell. The same habit applies to net income: the prose says $4.6 billion, and the cell says $4,552 million.
| Line | This quarter | Year-ago quarter | Release’s printed change |
|---|---|---|---|
| Product revenue | 14,667 | 11,077 | 32% |
| Services revenue | 3,850 | 3,806 | 1% |
| Total revenue | 18,517 | 14,883 | 24% |
| Product cost of sales | 5,610 | 3,934 | not printed |
| GAAP operating income | 5,598 | 3,363 | 66% |
| GAAP net income | 4,552 | 2,860 | 59% |
| Cash from operations | 4,357 | 3,212 | 36% |
Networking, inside product, was $11,132 million, printed up 43%. Security was $2,120 million, up 7%. Collaboration was $1,136 million, up 8%. Observability was $279 million, up 2%. Those four product lines plus services add to $18,517 million exactly. The release does not add an AI line beside them.
GAAP diluted earnings were $1.14 a share. Non-GAAP diluted earnings were $1.40. Both are in the reconciliation. The $9 billion expectation is in neither column.
Why does the US matter now?
The United States is where the hyperscalers place the large network orders, and it is where this invoice landed. Americas revenue was $11,506 million, printed up 28%. That is 62.1% of the quarter on our division of $11,506 million by $18,517 million. EMEA was $4,456 million, up 18%. APJC was $2,556 million, up 21%.
Add the three regions and the sum is $18,518 million, one million above total revenue. The release says amounts may not sum. Do not move a million dollars from one region to another to force the total. The shape is still clear: most of the recognised revenue is in the Americas.
The step that sits here is the network after the chip has been packaged. Semiconductors are the die. Hyperscalers are the buyers who then have to connect those chips. Cisco is paid when that connection is recognised as product revenue.
| Step | Who | How they get paid | Status |
|---|---|---|---|
| Networking product | Cisco | Revenue recognised, $11,132 million this quarter | Paid |
| Security, collaboration, observability | Cisco | Three smaller product lines, $3,535 million together | Paid, slow |
| Services | Cisco | $3,850 million, up $44 million on the year | Paid, almost flat |
| Hyperscaler AI infrastructure | Not named as a line | $9 billion printed as a full-year expectation | Off the quarter |
| Product still to deliver | The customer, until delivery | Product remaining performance obligations $23,396 million | Did not grow |
No customer is named. The exhibit has no table of buyers above 10% of revenue. A hyperscaler, a neocloud and an enterprise can all sit inside Networking, and this document will not say how the $11,132 million splits.
What changed
Three things changed in the cells, and one thing did not. Revenue was recognised at a higher level. The undelivered product book did not grow. Inventory did. The AI figure stayed an expectation.
Product revenue rose by $3,590 million, from $11,077 million to $14,667 million. Services rose by $44 million, from $3,806 million to $3,850 million. Almost the entire $3,634 million increase in total revenue is product. The release prints product up 32% and services up 1%. Dividing the cells gives 32.4% and 1.2%. The difference from the printed rates is the rounding the table warns about.
Inside product, the release prints Networking up 43% and does not print last year’s networking dollars in that table. We do not invent them. What the table does print is enough: Networking is $11,132 million of this quarter’s $14,667 million of product, which is 75.9% of product and 60.1% of total revenue. Security, collaboration and observability together are $3,535 million, 19.1% of total revenue. Services are the other 20.8%.
The balance sheet moved the other way on the promise still open. Product remaining performance obligations were $23,396 million on 24 October, against $23,436 million on 25 July. That is a decline of $40 million. Total remaining performance obligations fell from $46,734 million to $46,169 million, a decline of $565 million. A large recognised quarter did not leave a larger undelivered product book behind it.
Deferred revenue, which is billings not yet earned, rose by $277 million in the quarter, from $29,781 million to $30,058 million. Product deferred revenue rose by $195 million. Services deferred revenue rose by $82 million. Those two add to the $277 million. Against $18,517 million recognised, the deferred stock barely moved.
Inventory went the other direction. Inventories were $6,384 million, up from $5,694 million on 25 July, an increase of $690 million. The cash-flow statement prints a $686 million use for inventories. The $4 million between those two lines is not explained. Do not call them the same cell. More hardware sat on the books at the end of the quarter than at the start.
The sentence that did not become a cell is in the news summary. Cisco raised its expectation for AI infrastructure revenue from hyperscalers to $9 billion in fiscal 2027, more than double the total for fiscal 2026. Fiscal 2026’s AI total is not printed. “More than double” is not a number you can subtract.
Our math
The work below is our arithmetic. Cisco prints the dollar cells and the rounded rates. It does not print the margin on the extra product dollar, and it does not print how this quarter sits against a year made of four identical quarters.
Product gross profit was $9,057 million, against $7,143 million a year earlier. The extra gross profit is $1,914 million. The extra product revenue is $3,590 million. Divide 1,914 by 3,590 and the extra product dollar carried a 53.3% gross margin. The release prints last year’s product gross margin at 64.5% and this year’s at 61.8%. Dividing the dollar cells gives 64.5% and 61.8% at one decimal, the same rates the release prints. The 53.3% is not in the release. It sits 11.2 percentage points under last year’s product margin.
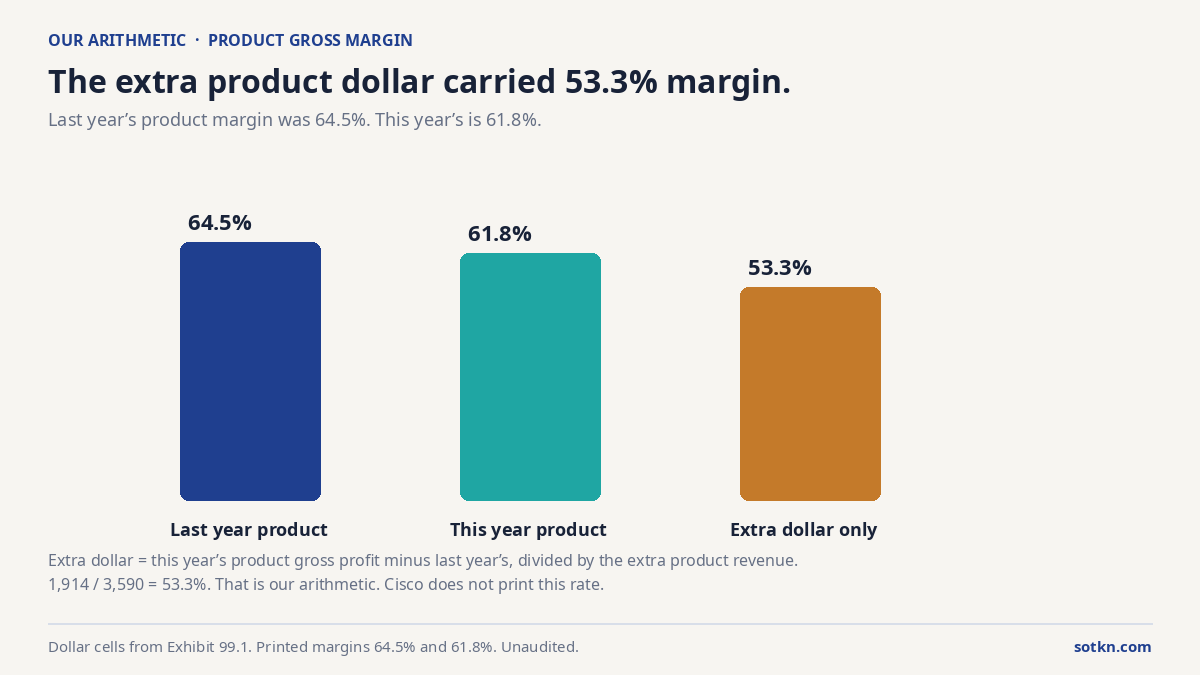
Cisco was paid on a larger product book, and the new slice was less profitable. Product cost of sales rose from $3,934 million to $5,610 million, an increase of 42.6% on our division, against a 32.4% increase in product revenue. Services gross margin is printed at 70.9%, up from 68.4%, on a revenue line that rose only $44 million.
| What we divided | Inputs, $ million | Result |
|---|---|---|
| Margin on the extra product dollar | 1,914 / 3,590 | 53.3% |
| Networking share of this quarter | 11,132 / 18,517 | 60.1% |
| Americas share of this quarter | 11,506 / 18,517 | 62.1% |
| Four copies of this quarter | 18,517 × 4 | 74,068 |
| Gap from that run-rate to the low end of the year guide | 74,800 − 74,068 | 732 |
| This quarter minus the top of the next-quarter guide | 18,517 − 18,200 | 317 |
The year guide is $74,800 million to $75,800 million. Four copies of this quarter are $74,068 million, which is $732 million under the low end. This quarter is 24.6% of the midpoint. A flat year would put 25% in each quarter, so the guide needs later quarters to do more than repeat this one.
The next quarter is guided at $18,000 million to $18,200 million. Even the top is $317 million under the $18,517 million just recognised. The midpoint is $417 million under it. The guide is not a promise. It is the company’s range, and it points down from the quarter that was just paid.
The $9 billion expectation is 12.0% of the midpoint of the year guide if you divide 9,000 by 75,300. That division does not make the $9 billion additive. The release lists the year revenue guide and the AI expectation as two sentences, not as a sum. Adding them would invent an $84.3 billion year. Do not.
One bound, labelled as a bound. If the expectation of $9 billion is more than double last year’s hyperscaler AI infrastructure revenue, then last year’s figure was under $4.5 billion. The exhibit does not print last year’s figure. Under $4.5 billion is the edge of the words “more than double.” It is not a Cisco disclosure of fiscal 2026.
This arithmetic does not say how much of the $11,132 million was hyperscaler AI, and it does not name a customer. The next-quarter non-GAAP gross-margin guide is 65% to 66%, against this quarter’s non-GAAP total gross margin of 65.6%. That is a company range, not a split of the extra product dollar.
Where does the money stick?
The money sticks at recognition, then it sticks again in the unnamed year. Follow one dollar from the customer to the line that is still missing.
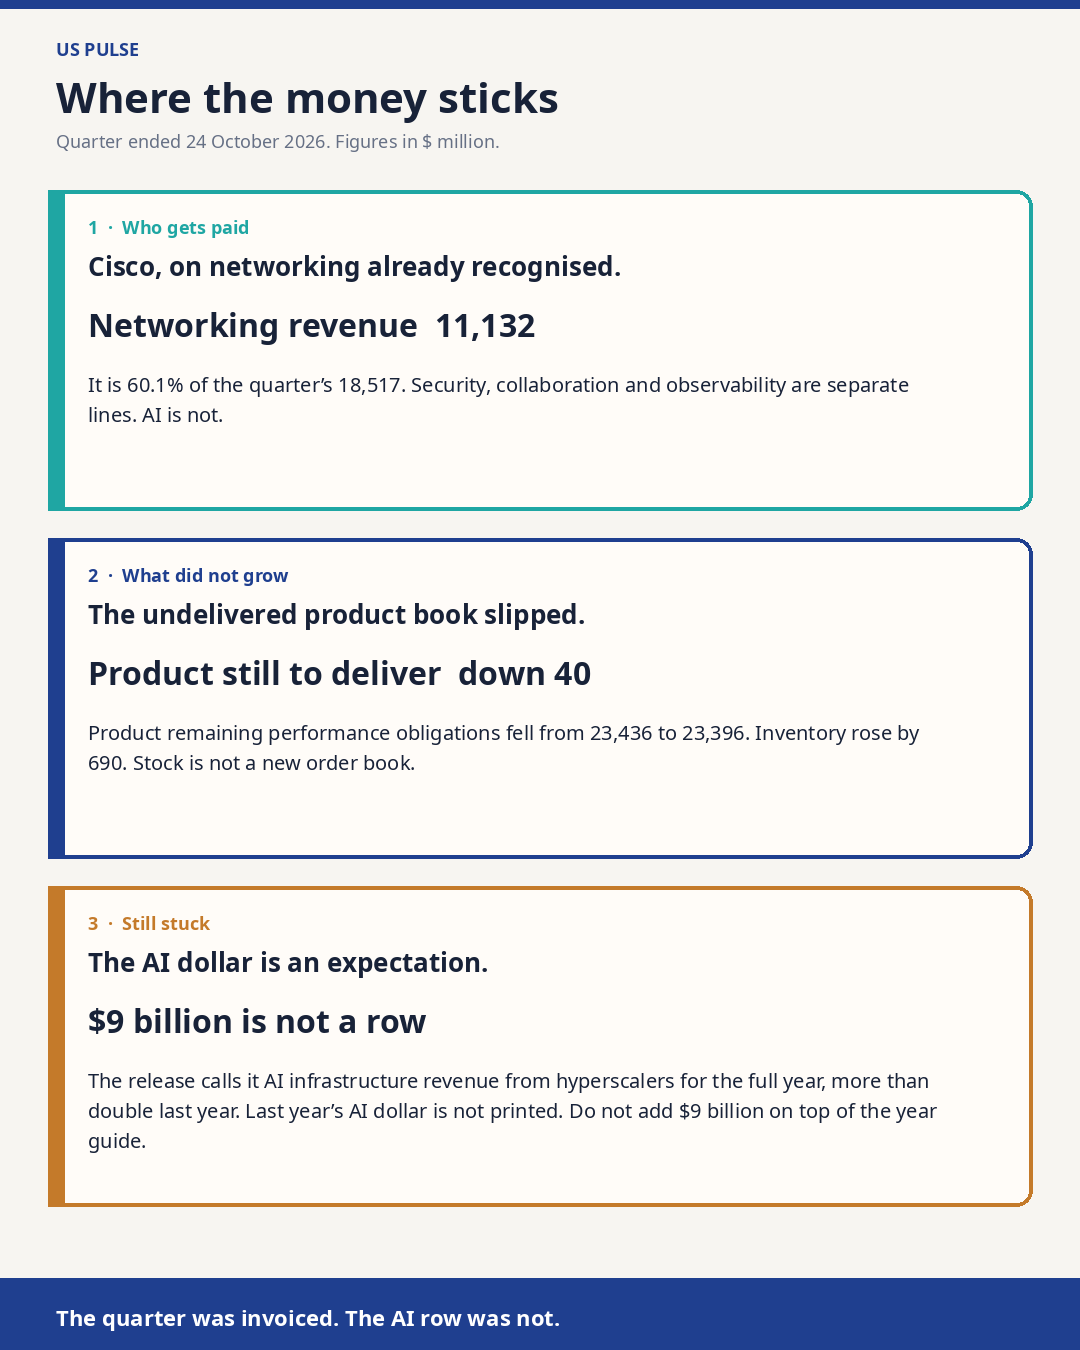
Cisco recognises networking, and stockholders are paid in cash. The networking recognition is the $11,132 million. GAAP operating income was $5,598 million. Net income was $4,552 million. Cash from operations was $4,357 million. Dividends paid were $1,654 million. The repurchase table prints $2,002 million, and the cash-flow line prints $1,997 million. The release says amounts may not sum. Remaining repurchase authority is $6.1 billion, with no end date. That cash return is not the AI row.
A switch in inventory is not an order. Inventories rose by $690 million. Product still to deliver fell by $40 million. Warehouse stock is a cost already incurred. It is not the $9 billion, and it is not a customer name.
The stuck dollar is the expectation. The $9 billion is printed for the fiscal year, not for the thirteen weeks ended 24 October. Until a later exhibit puts a closed-quarter number on that label, the line you can point to is networking.
Is the AI row still off the page?
Yes. Nothing in this exhibit turns the $9 billion into revenue of the quarter ended 24 October 2026. The income statement, the product-group table, the geographic table and the remaining-performance-obligation table all exist. None of them has a hyperscaler AI row.
A small acquisition, WideField Security, closed for net cash of $113 million. That is a security line in the cash-flow statement. It is not an AI infrastructure row.
Two cautions. “More than double” can be true and still leave this quarter unnamed, because a full-year expectation can sit in later quarters. The next-quarter guide, pointed down from this quarter, fits that reading and does not prove it. Non-GAAP net income of $5,567 million is not a hidden AI row either. The reconciliation lists share-based pay, acquisition amortisation, deal costs, a restructuring charge, investment gains and tax. AI is not one of those lines.
The permanent page on how a paid step and a missing step can be true at the same time is where the stuck step moves. This quarter is a network version of that: the switch was recognised, and the AI label was not given a cell.
What dates matter
The exhibit prints four dates you can hold, and it leaves the next results date out.
| Date | What it is | What it is not |
|---|---|---|
| 24 October 2026 | Last day of the quarter | Not the day the results were furnished |
| 12 November 2026 | Form 8-K and Exhibit 99.1 | The 8-K says these results are not “filed” for Section 18 |
| 4 January 2027 | Record date for the $0.42 dividend | Not a revenue date |
| 20 January 2027 | Payment date for that dividend | Still subject to the declaration already made; later dividends need the board |
| Next results | Not printed | Do not invent a February date from habit |
The next quarter’s guide is a range, not a calendar entry. When that quarter is reported, the test in this note is simple: is there a hyperscaler AI infrastructure number for a closed quarter, and did revenue land inside, above, or below $18,000 million to $18,200 million.
How is this different from the Applied Materials quarter?
Applied Materials reported the same evening. That print is already on the US door as a tools-and-rooms note. Applied is paid when a wafer tool is sold into a factory. Cisco is paid when a network product is recognised. One exhibit is equipment going into a clean room. This one is the connection after the chip exists.
Cisco’s own next quarter is guided below the quarter it just recognised, even at the top of the range. That is a fact from this exhibit. It is not a comment on Applied’s guide. It is also not a Korea memory print. This exhibit does not split memory out of the $11,132 million. The column says networking.
What would change this view?
The view is that Cisco has been paid on networking already recognised, and that the hyperscaler AI dollar is still an expectation without a quarter of its own. It changes if any of these show up in a later primary document.
- A closed quarter prints hyperscaler AI infrastructure revenue as its own number, in dollars, not only as a full-year expectation.
- Fiscal 2026’s AI infrastructure revenue is printed as a figure, so “more than double” can be checked instead of bounded.
- The next quarter’s revenue is above $18,200 million or below $18,000 million, outside the guide in this exhibit.
- Product remaining performance obligations turn up by more than a rounding difference, or inventory reverses, in a way the company ties to named AI shipments.
- A customer is named, with a share of revenue, in a filing. This exhibit does not name one.
- The company adds the $9 billion on top of the year revenue guide. It has not. If a later document does, the “do not add” line in our arithmetic comes off.
The view stays intact while Networking remains one line, the $9 billion remains a year-long expectation, and the next quarter is still guided below the one just booked.
Practical takeaways
- Who got paid is Cisco, on $18,517 million recognised, of which networking is $11,132 million.
- The $9 billion is a full-year hyperscaler AI expectation. It is not this quarter’s revenue, and it is not added to the $74.8 billion to $75.8 billion year guide.
- The extra product dollar carried a 53.3% gross margin on our arithmetic, under the 64.5% product margin of the year-ago quarter.
- Product still to deliver fell by $40 million. Inventory rose by $690 million. Stock is not an order book.
- The next quarter is guided at $18.0 billion to $18.2 billion, below this quarter even at the top of the range. The report date for that quarter is not in this exhibit.
FAQ
What did Cisco report for the quarter ended 24 October 2026?
Cisco recognised revenue of $18,517 million, GAAP net income of $4,552 million, and cash from operations of $4,357 million. Networking revenue was $11,132 million. The results were furnished on 12 November 2026 and are unaudited.
Who gets paid on this quarter?
Cisco, on product and services already recognised. Networking is the large product line, at $11,132 million. Stockholders were also paid a dividend of $1,654 million in the quarter. The exhibit does not name the customers inside Networking.
Is the $9 billion in this quarter’s revenue?
No. The release prints $9 billion as AI infrastructure revenue from hyperscalers for the full fiscal year, described as more than double fiscal 2026. It is not a line in the quarter ended 24 October 2026, and fiscal 2026’s AI dollar is not printed.
Did the undelivered product book grow with networking revenue?
No. Product remaining performance obligations fell by $40 million in the quarter, from $23,436 million to $23,396 million. Inventories rose by $690 million. The open product book and the warehouse are different stocks.
What date can move this view?
The exhibit does not print the next results date, so that date is not a fact yet. The dates it does print are the dividend record date of 4 January 2027 and the payment date of 20 January 2027, at $0.42 a share. A later exhibit that gives the AI line its own closed-quarter number would move the view sooner.
Keep reading on the map
The switch was recognised. The AI dollar was not given a row. The map is the steps on either side of that invoice.
- US — the door for the network, the tools and the power rules.
- The Applied Materials quarter — tools into a clean room, the same evening, a different step.
- Hyperscalers — the buyers this expectation points at, without a customer name in the exhibit.
- Semiconductors — the chips the network connects. This filing does not count wafers.
- Where the stuck step moves — why a paid line and a missing line can be true together.
How we check this. Cells are from Exhibit 99.1 furnished with the Form 8-K on 12 November 2026. The income statement is in millions of dollars. Divisions and the margin on the extra product dollar are our arithmetic. This is not a recommendation to buy or sell.
References
- Cisco Systems, Inc., Exhibit 99.1 to the Form 8-K, press release dated 12 November 2026, results for the quarter ended 24 October 2026. Income statement, revenue by geography, revenue by product group, gross margins, balance sheet, cash flow, remaining performance obligations, deferred revenue, dividends and repurchases, GAAP to non-GAAP reconciliation, and the Q2 and full-year guides. The $9 billion hyperscaler AI expectation is in the news summary, not in those tables. Exhibit 99.1 on EDGAR
- Cisco Systems, Inc., Form 8-K, date of report 12 November 2026, signed by Mark Patterson, Executive Vice President and Chief Financial Officer. Item 2.02 furnishes the results and states that the information, including the exhibit, shall not be deemed filed for purposes of Section 18. Exhibit 99.1 is the press release. Form 8-K on EDGAR