Chips Booked: Who Gets Paid While China's Hygon Still Waits on HBM
Hygon on 19 Oct printed nine-month sales of RMB 14.96bn. Foundries are paid in cash; advanced HBM is still the stuck step.

Hygon Information Technology, China's listed x86 CPU and DCU designer, printed unaudited third-quarter figures after the close on 19 October. Nine-month sales were RMB 14.95 billion, up 57.58% from a year earlier. Who gets paid is Hygon on the design sale and the foundries on the cash that left as prepayments and inventory. The stuck step is still advanced HBM: a DCU that ships without a stack is a die waiting for memory.
CHINA PULSE · Data as at 20 Oct 2026 · Next update: after a named HBM volume print or Hygon’s annual report
Affects: Semiconductors · HBM · Hyperscalers — Markets: China · Korea · Taiwan
Education only, not advice to buy or sell any security. Figures: Hygon Q3 report released 19 Oct 2026 (board date 20 Oct), H1 report 14 Aug 2026, Q1 report 7 Apr 2026, buyback announcement 19 Oct. Our own sums are labelled “our arithmetic”.
The numbers that matter this month
9M revenue
RMB 14.95bn
+57.58% vs 9M 2025
PrimaryQ3 revenue
RMB 5.86bn
+45.46% YoY · +15.6% vs Q2 (our arithmetic)
Headline9M attributable profit
RMB 2.85bn
+45.12% · Q3 profit −5.7% vs Q2 (our arithmetic)
Paid on the book9M operating cash
−RMB 2.44bn
Was +RMB 2.25bn a year earlier · stocking named
Cash upstreamBuyback proposal
RMB 5–8bn
Chairman 16 Oct · announced 19 Oct · still a proposal
OverlayAdvanced HBM
Still the bind
No stack named. CXMT HBM3E remains small-batch.
Stuck stepStatus chips are Second Order’s read. Figures come from Hygon’s Q3 report released 19 Oct 2026 (board date 20 Oct) and the 19 Oct buyback announcement.
Why does China matter now?
Because China is building a closed, parallel AI stack, and this week's filing is the design-house receipt: chips are selling, cash is leaving for wafers, and the memory that turns a DCU into a training node is still the bind.
Export rules keep many of the best accelerators and HBM stacks out. The response is domestic designers such as Hygon, foundries such as SMIC, and memory such as CXMT. Our September pulse, China HBM Access, named advanced HBM as the stuck step. This pulse does not move that name. It shows who is already being paid while that step stays stuck.
A different door from this month’s other China prints: SMIC’s margin, CXMT server DRAM, NBS storage and power, and 8-inch AI power chips. Today is the designer above those wafers: Hygon, 688041.SS, parented 27.96% by Sugon.
1 · Design sale
Who: Hygon (CPU + DCU)
Paid: RMB 14.95bn of 9M sales as chips are billed
2 · Wafer and materials cash
Who: Foundries and materials suppliers
Paid: prepayments RMB 5.88bn; inventory RMB 8.92bn
3 · Parent book
Who: Sugon, 27.96%
Paid: as the named parent, not as a foundry
4 · Advanced HBM
Who: Not named in this filing
Paid: Not yet. A DCU without a stack is a die waiting
Labels: Paid on the book = revenue as chips ship. Paid in cash = prepayments and inventory already left Hygon. Stuck step = no named HBM volume.
If you only remember one thing: a 58% sales jump is a P&L print. It is not an HBM print. The cash went upstream.
What changed on 16–20 October
Three papers landed in four days. Two are Hygon’s. One is the peer-group overlay.
On 16 October, chairman Li Jun proposed a RMB 5–8 billion A-share buyback with own cash, for an employee plan, at no more than 150% of the 30-day average once a board scheme exists. Announced 19 October. Not completed. The cninfo filing still needs board approval.
On 16 October, the South China Morning Post reported other domestic chip names printing AI-linked earnings: MetaX profitable on nine-month orders; Yuanjie guiding quarterly net profit of RMB 403–453 million, up 579–660%, on optical laser chips. Overlay, not a Hygon number. Hygon is the STAR-listed CPU-plus-DCU book whose cash statement shows where the money went.
On 19 October after the close, Hygon released the unaudited third-quarter report (board date 20 October). Nine-month revenue RMB 14.95 billion, up 57.58%; attributable profit RMB 2.85 billion, up 45.12%; Q3 sales RMB 5.86 billion, up 45.46%. Operating cash was minus RMB 2.44 billion, against plus RMB 2.25 billion a year earlier, a swing the company attributes to stocking materials to grab slots. Research spend was RMB 4.47 billion, 29.90% of sales. Contract liabilities collapsed from RMB 2.02 billion at end-2025 to RMB 11.9 million. Yicai carried the headlines the same evening.
Context, not this week’s print: the 14 August half-year report said Hygon had adapted more than 400 large models on its DCU stack and listed more than 6,000 Guanghe partners. This week’s print is the cash.

Our math: labelled our arithmetic
Hygon already printed the yuan. What follows is division on those figures, labelled as ours.
- Quarterly sales. Q1 from the 7 April report was RMB 4.034bn. H1 was RMB 9.099bn. That leaves Q2 of RMB 5.065bn (our arithmetic). Q3 at RMB 5.856bn is 15.60% above Q2 (our arithmetic).
- Quarterly profit. Q1 attributable RMB 687m; H1 RMB 1.798bn; implied Q2 RMB 1.111bn (our arithmetic). Q3 at RMB 1.048bn is 5.70% below Q2 (our arithmetic). Sales up, profit down, same quarter.
- Gross margin. 9M cost RMB 6.492bn on sales of RMB 14.955bn is 56.59% (our arithmetic), versus 60.10% a year earlier (our arithmetic) — 3.51 points thinner. Implied Q3 margin 58.73% versus H1 55.21% (our arithmetic). Mix improved in the quarter. It is still thinner than last year.
- Cash versus sales. Cash collected from customers RMB 12.883bn, or 86.15% of revenue (our arithmetic). Cash paid for goods RMB 12.533bn, or 1.93 times cost of sales (our arithmetic). That is the stocking the company named.
- Working-capital soak. Inventory +RMB 2.515bn, prepayments +RMB 3.000bn, receivables +RMB 1.992bn versus end-2025 (our arithmetic). About RMB 7.51bn absorbed against 9M profit of RMB 2.85bn — 2.64 times the profit (our arithmetic).
- Contract liabilities. Customer prepayments fell from RMB 2.019bn to RMB 11.9m, a 99.41% drop (our arithmetic). Buyers are no longer parking cash at Hygon. Hygon is parking cash at its suppliers.
- Third-quarter cash. H1 operating cash −RMB 428m; 9M −RMB 2.443bn. Implied Q3 drain RMB 2.015bn (our arithmetic). Most of the year’s cash hole opened after June.
- Buyback versus cash. Cash equivalents RMB 6.943bn on 30 September. RMB 5bn would be 72.0% of that cash; RMB 8bn would be 115.2% (our arithmetic). Still a proposal. Large against cash not already in inventory.
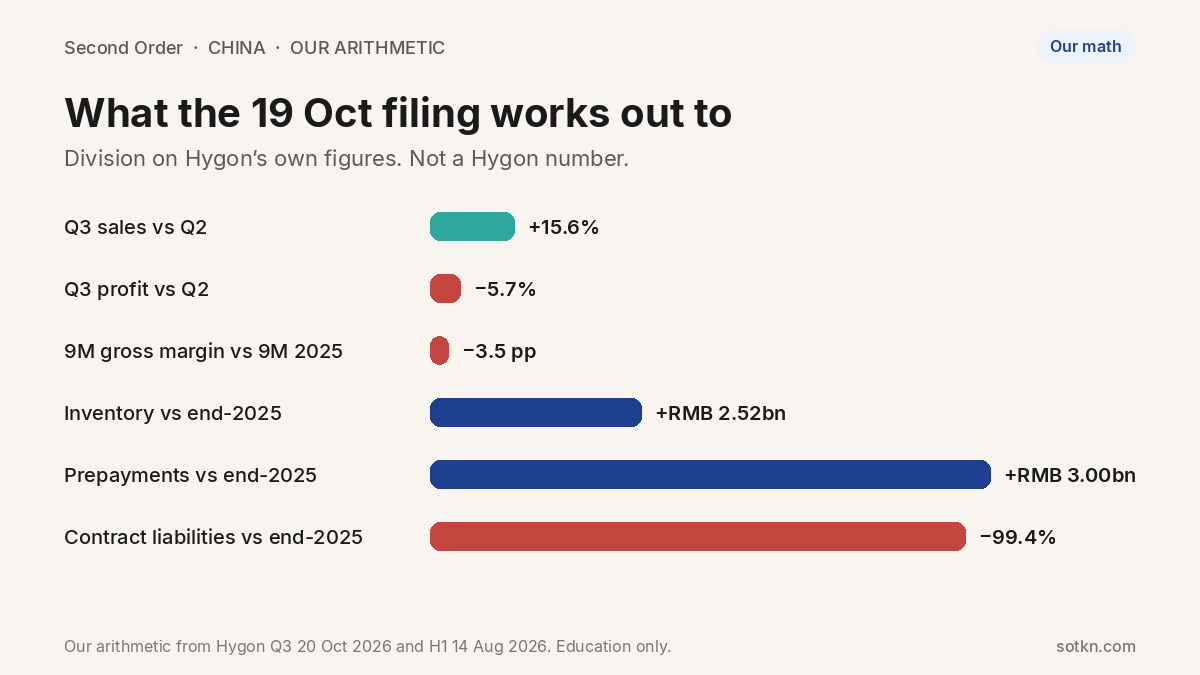
What this tells you: the designer is selling more chips, keeping a thinner margin than a year ago, and sending cash to the wafer step faster than customers send cash back. It does not tell you what a Hygon share is worth. We do not do price calls.
Where does the money stick?
At the step that already has a cash cheque, not at the step that still has empty sockets.

1. Hygon, on the design sale. Nine-month revenue of RMB 14.95 billion is the P&L receipt. Sequential sales of plus 15.6% in Q3 (our arithmetic) say that receipt is still growing. Sugon, holding 27.96%, sits behind that book as the named parent, not as a foundry.
2. Foundries and materials, in cash. Prepayments of RMB 5.88 billion and inventory of RMB 8.92 billion are the cash receipt. The company said it stocked to grab slots. Operating cash of minus RMB 2.44 billion is the evidence. Whoever holds those wafer slots is paid before a finished DCU sits in a hall. Our 16 October pulse had Chinese 8-inch lines full on AI power chips. This print is the designer paying into that tightness, on a different node, in cash.
3. Advanced HBM — not yet. A DCU still needs a stack. CXMT’s HBM3E is small-batch, as our September HBM pulse mapped. Legal advanced HBM into China stays under the December 2024 controls. This Q3 report names no supplier, stack volume, or qualified attach. Empty sockets are the bind.
One-line rule: while this shape holds, the book is Hygon’s, the cash is the foundry’s, and HBM still waits.
Is advanced HBM still stuck?
Yes. A 58% sales print is a designer that can bill. It is not a memory step that can ship at volume.
Three things keep it stuck. First, this filing. Hygon names AI demand as the reason sales rose, and stocking — not HBM volume — as the reason cash fell. No stack count, no take-or-pay, no qualified-attach percentage.
Second, the rest of the China door. CXMT told the 12 October pulse it would launch server DRAM on a denser cell by year-end. That is server memory, not HBM3E volume. The September HBM pulse still had CXMT HBM3E in small-batch, with commercial volume an ambition in secondary reports for 2027. Nothing in the last four days moved that.
Third, the peer overlay. SCMP’s 16 October cluster is the same shape as Hygon’s P&L: domestic silicon is selling. Optical lasers and CPU/DCU dies are not HBM stacks. They confirm demand. They do not clear the socket.
If HBM volume cleared, the stuck step would move. The next candidates on this door are advanced packaging tools and power for the largest domestic clusters. Until a named stack volume prints, read China AI hardware through memory access first. For the global memory clock see HBM, explained.
What dates matter

- 16 October 2026 — Chairman’s buyback proposal, RMB 5–8 billion. Announced 19 October. Still needs a board scheme.
- 16 October 2026 — SCMP cluster of domestic chip nine-month prints. Overlay, not a Hygon number.
- 19 October 2026 — Hygon Q3 report released after the close. Nine-month sales RMB 14.95 billion. Done.
- 20 October 2026 — Board date on the Q3 PDF. Done.
- Fourth quarter of 2026 — Huawei Ascend 950DT public availability timing, from the September HBM pulse. The test: do indicated card prices ease, or stay elevated on memory cost?
- End of 2026 — CXMT’s stated aim to launch server DRAM on a denser cell. The test: a server-memory print, not an HBM print. Do not mix them.
- 2027 — CXMT HBM3E volume ambition in secondary reports. The test: verified shipments into named training clusters, not samples.
- Not set — Hygon’s next full report, with any named HBM or foundry commentary. The test: does a stack supplier appear, or only the sales-and-stocking language again?
The 19 October filing coloured the cash. Only a named HBM volume print, or a foundry utilisation print that shows open slots, can move the stuck step.
How is this different from the September HBM Pulse?
The 19 September pulse was a policy-and-price print: MIIT’s 9,800-EFLOPS target and Reuters’ indicated Ascend card prices above RMB 250,000 on HBM cost. Who got paid was whoever could deliver a qualified stack. The stuck step was advanced HBM access.
Today is a company filing from the domestic CPU-plus-DCU designer. Who gets paid is Hygon on the book and the foundries on the cash. The stuck step is still advanced HBM — the same family, a different receipt. September had card prices. October has a cash-flow statement.
It is also different from CXMT’s server-DRAM pulse (a memory-maker aiming at year-end server chips, stuck on testing), from the 16 October 8-inch pulse (power chips on mature wafers, stuck on 8-inch capacity), and from SMIC’s margin pulse (a foundry guide, stuck on logic folding). Same China door — domestic silicon — different paper.
What would change this view?
- Hygon, in a later report, names an HBM supplier, a qualified-attach volume, or a take-or-pay with CXMT or a peer.
- CXMT, or another domestic maker, posts verified HBM3E shipments into named training clusters, not only samples.
- Operating cash turns positive while inventory and prepayments fall — a sign the stocking cycle is done, not that HBM cleared.
- SMIC or a named foundry reports open slots on the processes Hygon uses, which would move the cash bind even if HBM stayed tight.
- Indicated Ascend and Cambricon card prices fall while unit shipments rise — a sign memory cost eased, from the September overlay.
- A BIS or allied licensing change reopens meaningful legal advanced-HBM channels into China.
The view stays intact while sales climb, cash sits in wafers and inventory, contract liabilities stay near zero, and no named HBM volume prints.
Practical takeaways
- Hygon, 19 Oct: nine-month sales RMB 14.95bn, up 57.58%; Q3 RMB 5.86bn, up 45.46%; attributable profit RMB 2.85bn, up 45.12%
- Operating cash minus RMB 2.44bn, against plus RMB 2.25bn a year ago. The company names stocking to grab slots
- Our arithmetic: Q3 sales +15.6% versus Q2; Q3 profit −5.7%; nine-month gross margin 56.59% versus 60.10% a year ago; working-capital soak about RMB 7.51bn
- Chairman proposed a RMB 5–8bn buyback on 16 Oct, announced 19 Oct. Still a proposal
- Who gets paid: Hygon on the design sale; foundries and materials on the cash; Sugon as the 27.96% parent
- Stuck step: advanced HBM. A booked DCU is not a stacked node. CXMT HBM3E remains small-batch
- Watch a named HBM volume print, CXMT’s end-2026 server-DRAM aim (different product), and Hygon’s next full report
FAQ
What did Hygon print on 19 October 2026?
An unaudited third-quarter report, board-dated 20 October. Nine-month revenue was RMB 14.95 billion, up 57.58%. Attributable profit was RMB 2.85 billion, up 45.12%. Third-quarter revenue was RMB 5.86 billion, up 45.46%. Operating cash for the nine months was minus RMB 2.44 billion. The company said it stocked materials to match the sales plan.
Who gets paid on this print?
Hygon, on the design sale, as chips are billed. Foundries and materials suppliers, in cash, through prepayments of RMB 5.88 billion and inventory of RMB 8.92 billion. Sugon holds 27.96%. This is a map of who gets paid, not a buy list.
Why is HBM still the stuck step if sales rose 58%?
Because a DCU still needs a stack, and this filing does not name one. CXMT’s HBM3E is small-batch. Legal advanced HBM into China stays constrained. Sales are a P&L print. HBM is a socket print. The sockets in this week’s metaphor are empty.
Did operating cash fall because demand is weak?
No. The company said cash fell because it increased stocking and raw-material purchases to match the sales plan and grab market slots. Sales are up 58%. Receivables and inventory are up with them. Weak demand would show up as falling sales, not as a cash hole next to a record book.
Is this investment advice?
No. Education only. It maps who gets paid and which step is stuck. It is not a recommendation to buy or sell any security.
Keep reading on the map
- China Markets hub — country page
- China HBM Access (19 Sep) — the stuck-step name this filing does not move
- CXMT server DRAM (12 Oct) — a different memory product, still not HBM volume
- 8-inch power foundries (16 Oct) — the wafer door this cash is paying into
- SMIC margin pulse (9 Oct) — foundry guide, logic folding
- HBM, explained — the short clock
- Where the stuck step moves — members’ map
- All Markets doors — Taiwan, Korea, US, China
How we check this. P&L, cash and the stocking explanation: Hygon Q3, released 19 October 2026 (board date 20 October). Sequential quarters: our arithmetic from that filing plus the 14 August half-year and 7 April first-quarter reports. Buyback: 19 October announcement. Peer overlay: SCMP, 16 October. HBM still small-batch: our 19 September pulse, not a new CXMT print. Analyst targets left out. Own sums labelled “our arithmetic”. Our editorial standards →
Not investment advice. Do your own research.
References
- Hygon, 2026 third-quarter report, released 19 Oct 2026, board 20 Oct. cninfo PDF — 9M sales, Q3 sales, profit, operating cash, inventory, prepayments, contract liabilities, stocking explanation.
- Yicai, 海光信息:前三季度净利润28.47亿元 同比增长45.12%, 19 Oct 2026. yicai.com — same-evening headline print.
- Hygon, chairman’s buyback proposal, 19 Oct 2026 (proposal 16 Oct). cninfo PDF — RMB 5–8bn, own cash, still needs board approval.
- Hygon, 2026 interim report, 14 Aug 2026. cninfo PDF — H1 sales, profit, cash, cost of sales.
- Hygon, 2026 first-quarter report, 7 Apr 2026. cninfo PDF — Q1 sales and attributable profit.
- Howard Liu, China’s AI boom, self-sufficiency push fuel earnings surge for local chip firms, SCMP, 16 Oct 2026. scmp.com — MetaX; Yuanjie guide.
- National Business Daily, 净利增45%!芯片龙头海光信息,再传利好, 19 Oct 2026. nbd.com.cn — Q3 recap plus buyback overlay.