Ask Isn't ASP: Who Gets Paid When Samsung Opens Mid-$4 HBM4
October 2026 in one line: Maeil Business reported Samsung offered mid-to-high $4/Gb for 2027 HBM4 annual supply versus HBM3E ~$1.50/Gb — who gets paid is Samsung (and peers) if the premium sticks; the stuck step is ask ≠ cleared ASP.
Maeil Business reported exclusively on 2 Oct 2026 that Samsung Electronics opened 2027 HBM4 annual-supply talks at mid-to-high $4 per gigabit — more than three times today’s HBM3E print around $1.50/Gb. Who gets paid if that premium sticks is Samsung (and peers with pricing power) on qualified 2027 invoices; customers pay for the performance step-up. The stuck step is still ask ≠ cleared ASP: volumes are largely negotiated, but October’s price close plus qualification and yield still gate cash. Ready is not paid.
KOREA PULSE · Data as at 3 Oct 2026 · Next update: after any dated 2027 HBM4 ASP close or Samsung/SK HBM4 colour
Affects: Semiconductors · Hyperscalers · Neoclouds — Markets: Korea · Taiwan · US · China
Education only, not advice to buy or sell any security. Opening asks and stack estimates from press are labelled as reported. Prior wafer-mix and yield Pulses are cross-linked, not re-led.
The numbers that matter this month
Maeil exclusive (primary)
2 Oct 2026
Samsung mid-to-high $4/Gb HBM4 2027 annual-supply opening ask
PrimaryHBM3E reference (MK)
~$1.50 / Gb
Current flagship print cited against the HBM4 ask
PrimaryMultiple (MK framing)
>3×
Mid-to-high $4 vs ~$1.50 — more than three times
PrimaryPrice talks (MK)
Final · Oct 2026
Volumes largely set; price close enters final stages this month
ClockAsk ≠ cleared ASP
Still the bind
Opening ask is not a locked annual-contract ASP on qualified volume
Stuck stepSamsung HBM4 speed (via MK)
11.7–13 Gbps
Reliable 11.7 Gbps; up to 13 Gbps — performance-premium framing
PrimaryTrendForce / Micron (in MK)
+121% / “far higher”
Blended ASP + peer colour — context only, not Samsung’s settled ASP
ContextSources: Maeil Business English exclusive, 2 Oct 2026. Status chips are Second Order’s read. Ask ≠ settled contract ASP.
On this page: Why Korea? · What changed · Our math · Where money sticks · Is ask still stuck? · Dates next · How this differs · What would change this · FAQ
Why does Korea matter now?
Because the AI accelerator chain still needs high-bandwidth memory stacks that are mostly made in Korea — and those stacks are sold under annual contracts, not like spot commodity DRAM. When a leading maker prints an opening ask for next year’s flagship, cash cares about whether that ask survives the counter and lands on qualified volume.
That is the same map as HBM, explained and the Korea Markets hub. The fresh question this month is not “does HBM price up in a tight market?” — it is whether Samsung’s mid-to-high $4/Gb opening ask clears into a settled 2027 annual-contract ASP, or stays a negotiation headline.
1 · Opening ask (Maeil 2 Oct)
Who: Samsung Electronics
Paid: Mid-to-high $4/Gb HBM4 2027 annual supply — negotiation print
2 · Ask ≠ cleared ASP
Who: Customer counter + qualification
Paid: October price close still open; ready is not paid
3 · Peer pricing power
Who: SK hynix · Micron
Paid: Same annual-contract room; Micron “mostly sold” is secondary colour
4 · Wafer-pool clock
Who: HBM share of DRAM wafers
Paid: Separate door — see prior Korea capacity-mix Pulse
Chain is Second Order’s map. Neighbours: Semiconductors stack · HBM explained · Korea HBM DRAM capacity-mix Pulse · If HBM takes ~30% wafer share · Wire thin on the same ask.
What changed
The fresh primary print is dated 2 Oct 2026 on Maeil Business English (input 17:34; exclusive). MK says Samsung recently offered prices in the mid-to-high $4 range per gigabit during negotiations with major customers over next year’s HBM4 annual supply — more than three times HBM3E around $1.50/Gb.
What the exclusive actually says, in plain English: HBM is sold mostly under annual long-term contracts so customers lock volume and makers set production plans; a substantial portion of next year’s major HBM volumes is already negotiated on volume; price talks are expected to enter their final stages this month; Samsung ties the ask to HBM4 performance — 11.7 Gbps reliable, up to 13 Gbps — and wants a price premium on quality as the market shifts from volume to performance; TrendForce’s blended HBM ASP +121% YoY and Micron’s “far higher” call comments are carried as industry context.
What the exclusive does not say: a named customer who accepted $4; a filed contract schedule; a settled Samsung 2027 HBM4 ASP; or a matched SK hynix / Micron printed ask at the same level. Those gaps are the stuck step.
- Maeil Business (2 Oct 2026 exclusive): mid-to-high $4/Gb HBM4 2027 opening ask
- Same: HBM3E ~$1.50/Gb; more than 3×; volumes largely set; price final this month
- Same: 11.7 Gbps reliable / up to 13 Gbps performance framing
- Context only in MK: TrendForce blended HBM ASP +121% YoY; Micron “far higher”
- SED (1 Oct, secondary): Micron mostly sold 2027; Counterpoint share; ~$600→~$1,300 stack est.
- Businesskorea (23 Sep, secondary): ~180k→~250k HBM wafers/mo; HBM4 yield ~80%; mix ~80% HBM4-series
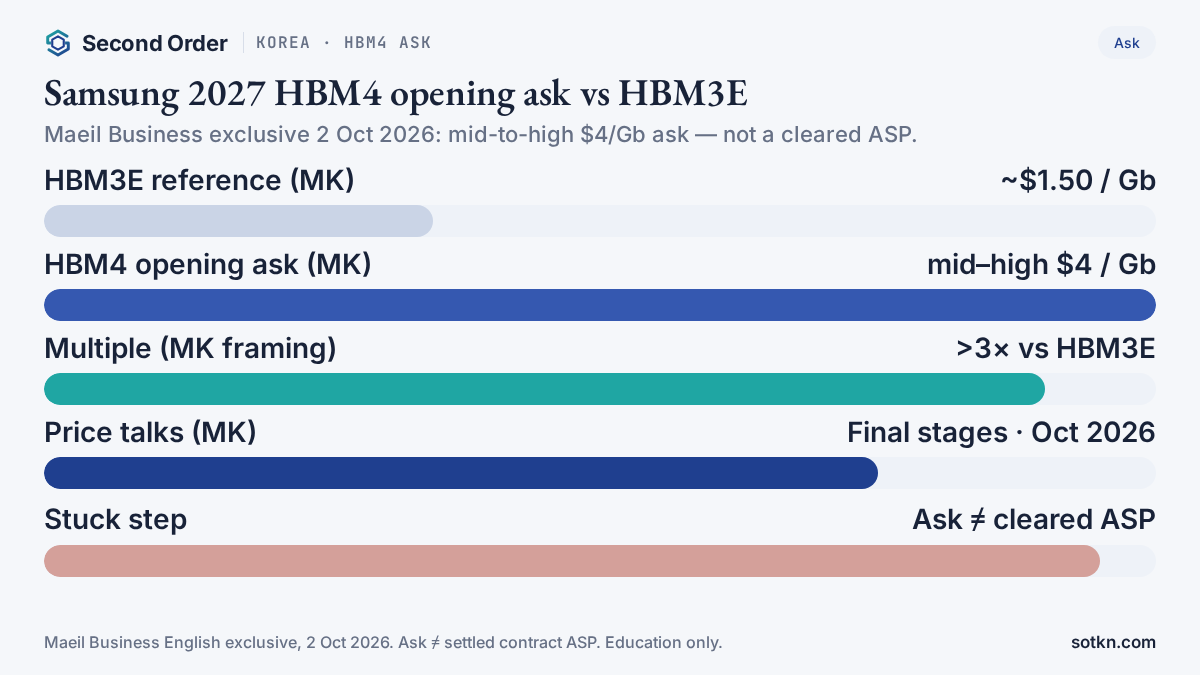
Thin same-day map on sotkn: Samsung asks mid-$4/Gb for 2027 HBM4 (Wire). This Pulse expands the Korea cash map — who gets paid, which clocks still bind, and how the ask sits next to share, yield, and wafer-mix prints you already have.
Secondary same-week colour: Seoul Economic Daily (1 Oct 2026) reported Micron had locked most of its 2027 HBM bit supply at prices above this year, cited Counterpoint HBM revenue shares (Samsung 21%→33% Q1→Q2; SK hynix 58%→50%; Micron 21%→18%), and carried an industry estimate that a 12-high 36GB HBM4 stack could move from about $600 this year toward about $1,300 next year — labelled estimate, not a Samsung contract. Businesskorea (23 Sep) framed Samsung’s push to lift HBM wafer input from about 180,000 to about 250,000 sheets per month (+40%), HBM4 yield near 80% (from below 60%), and HBM4-series toward ~80% of HBM mix — capacity and yield colour, not this ask’s ASP.
Our math — labelled our arithmetic
There is no settled Samsung 2027 HBM4 ASP in the primary print. So the arithmetic here is about ask versus reference and clocks — not inventing a cleared invoice.
Our arithmetic — ask vs HBM3E reference
Inputs: Maeil Business 2 Oct 2026. Mid/high band split and day count are Second Order’s arithmetic / judgment, not official guidance. Do not treat ~$4.5 as a printed figure.
What this tells you: MK’s “more than 3×” framing lines up with a mid-to-high $4 ask against ~$1.50 — the live clock this month is whether that ask survives the customer counter on qualified volume. What it does not tell you: the exact settled ASP, which customer accepted what, or how much of 2027 HBM4 bits clear at the ask.
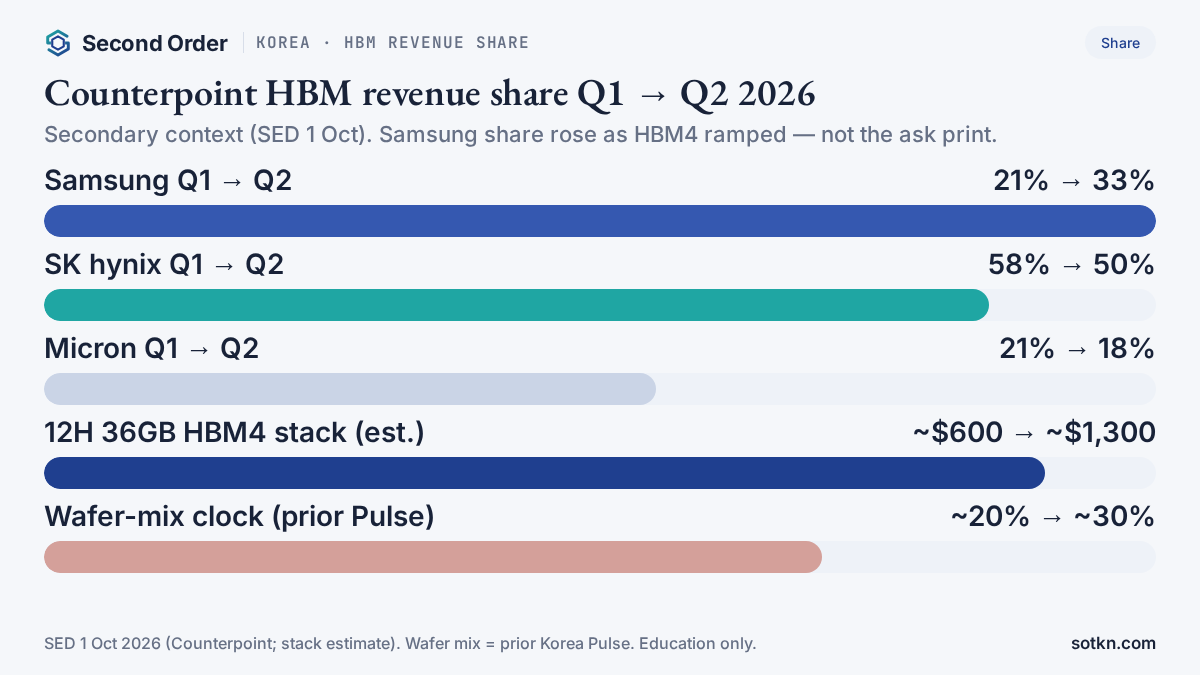
Secondary share / stack colour (label carefully)
Share / stack: SED 1 Oct 2026. Wafer input / yield: Businesskorea 23 Sep. Wafer mix: prior Korea Pulse (30 Sep) — cross-link, do not re-lead.
Where does the money stick?
At the steps with the fewest good substitutes — and only after the stuck step can actually invoice. An opening ask clears a negotiation headline. A locked ASP on qualified volume clears cash.
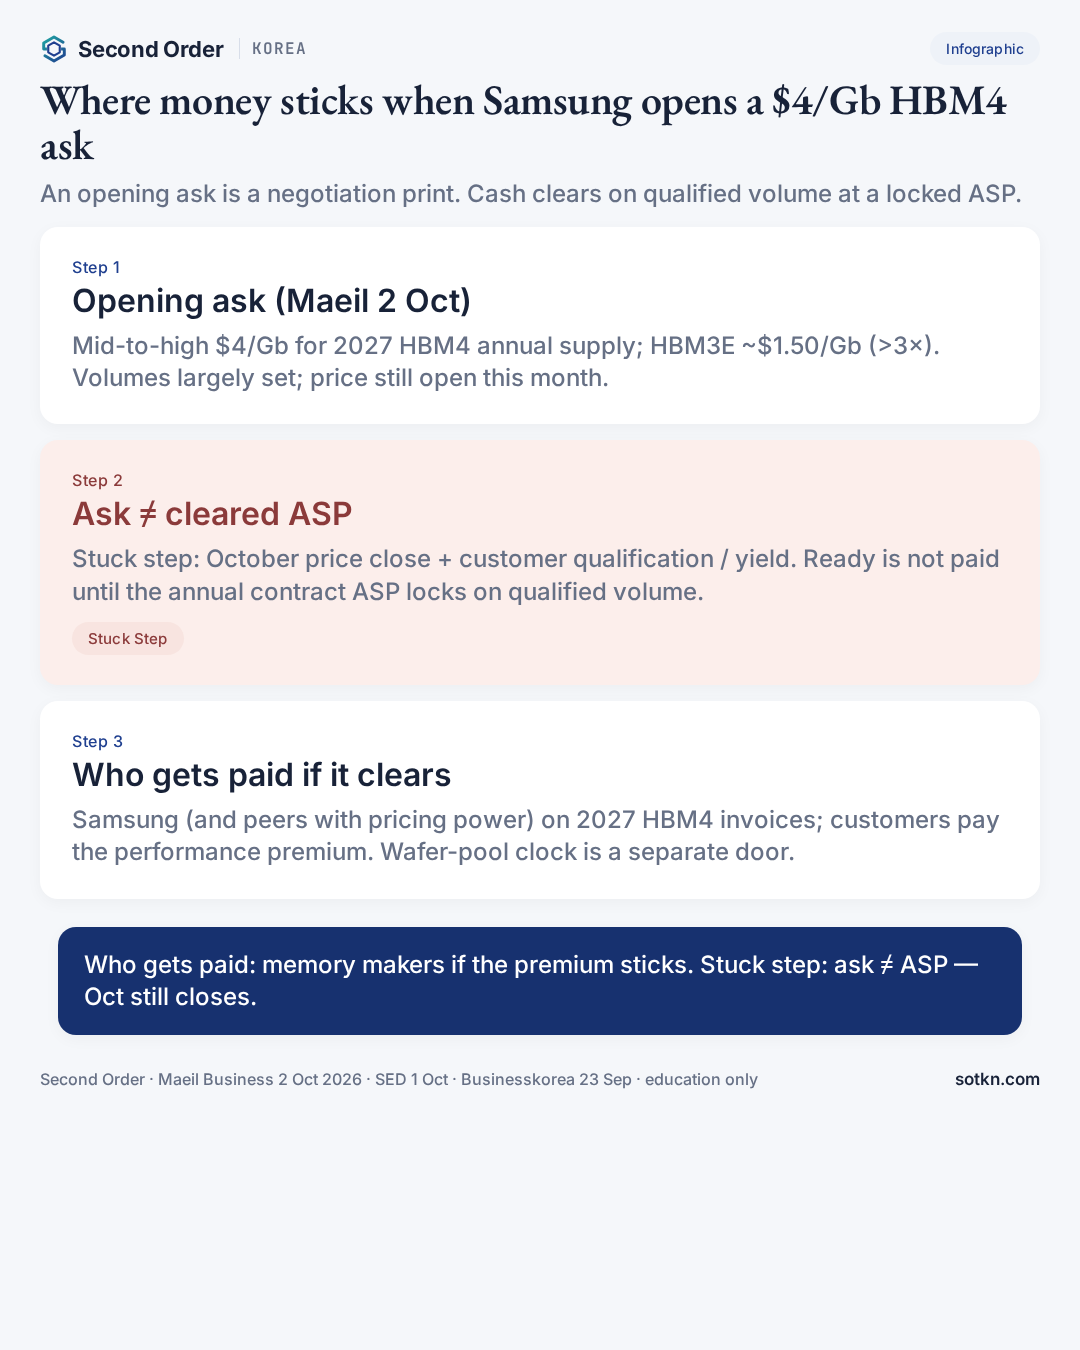
- Memory makers (conditional). If the mid-to-high $4 premium sticks on qualified 2027 HBM4 volume, Samsung gets paid on those invoices first in this print; SK hynix and Micron sit in the same annual-contract room with their own asks.
- Customers pay the performance step-up. AI accelerator buyers who already locked volume still negotiate price; the premium only becomes cash when qualification and the contract ASP land together.
- Not the stuck step alone: the exclusive. A dated Maeil print is useful. It is not a cleared ASP.
Same pattern as the HBM ~30% wafer-share Analysis and the Korea capacity-mix Pulse: money can be discussed for high-ASP HBM without the invoice clearing. The ask is another upstream cheque that still needs a counter.
Is ask ≠ ASP still stuck?
Yes. An exclusive that dates an opening ask does not settle the annual-contract ASP by itself.
Earlier Korea Pulses already mapped neighbour doors: Samsung HBM4 yield near 80% and HBM toward ~30% of industry DRAM wafers. This Pulse adds the price-ask gate — and insists on the gap between mid-$4 in the room and cash on qualified volume.
Two cautions before you read “triple HBM prices” as tomorrow’s invoice:
- Ask is not ASP. Mid-to-high $4/Gb is Samsung’s opening position as reported by Maeil Business. Customers still counter.
- Volume set is not cash cleared. MK says a substantial share of 2027 major HBM volumes is already negotiated — price is what remains this month, and qualification / yield still decide how much premium volume can ship.
If the ask clears and packaging / attach catch up, the stuck step can move. Candidates stay CoWoS-class packaging (mostly Taiwan — see this morning’s Chiayi land Pulse) and power for data centres — see Where does the stuck step move?.
What dates matter
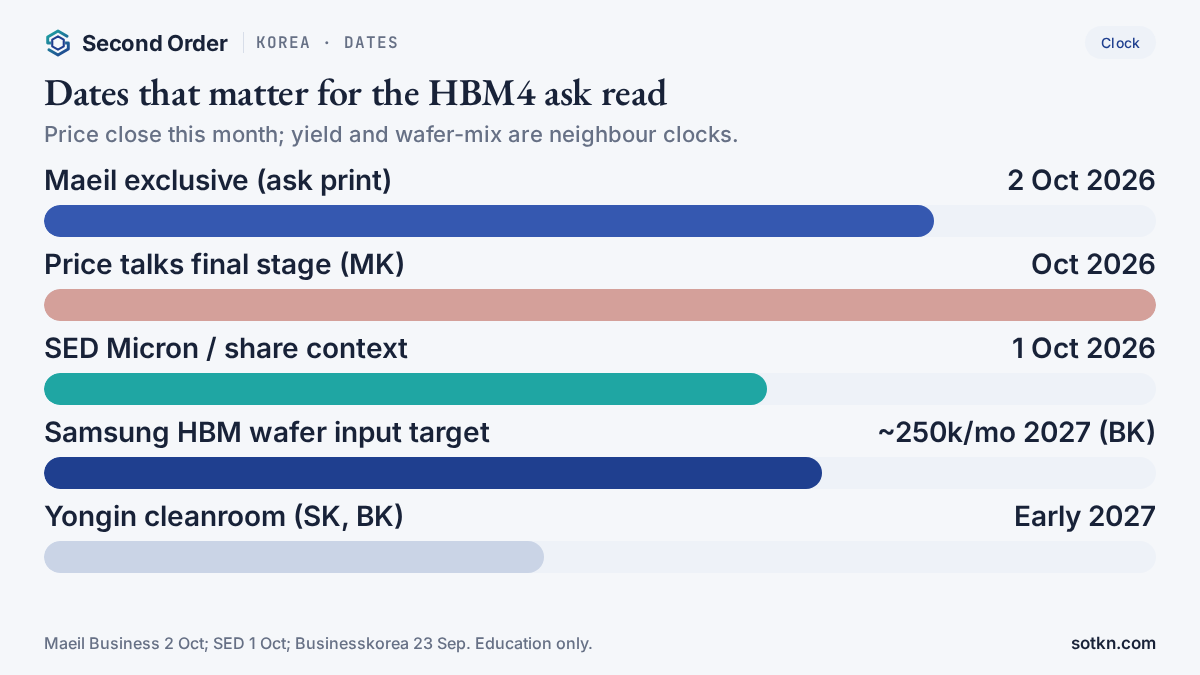
Dates to watch
Maeil Business 2 Oct; SED 1 Oct; Businesskorea 23 Sep. Do not invent a settled ASP date.
How is this different from …
- Wire thin on the same ask (2–3 Oct): That piece is the short daily map. This Pulse is the full Korea who-gets-paid / stuck-step expansion with charts and neighbour clocks.
- Korea HBM DRAM capacity-mix Pulse (30 Sep): That piece led on Kim Taewoo’s ~20%→~30% industry wafer-mix print. This piece does not re-lead wafer share; it links it as a separate clock.
- Korea Samsung HBM4 yield Pulse (21 Sep): That piece centred on yield near 80% and company-level wafer/SF4 shift. This piece centres on the 2 Oct opening-ask print.
- Analysis — If HBM takes ~30% wafer share: Analysis map of where cash sticks on wafer allocation. This Pulse stays on the price-ask gate for 2027 HBM4 annual contracts.
- Taiwan Chiayi packaging-land Pulse (3 Oct morning): Neighbour door on packaging land ≠ CoWoS slots. This Pulse stays on Korea memory ask ≠ ASP.
What would change this view?
The “ask ≠ ASP / Oct still closes” read weakens if:
- A dated customer or filing print shows 2027 HBM4 ASP settled — above, at, or below mid-to-high $4
- Price talks slip past October, or volume already “negotiated” reopens
- A peer (SK hynix / Micron) dated 2027 HBM4 contract ASP anchors the band
- Qualification fails or attach/CoWoS limits cap how much premium volume can ship
- Hyperscaler / neocloud spend cuts show up first in Korea export or maker commentary
- Wafer-pool or packaging, not price, becomes the louder bottleneck in buyer commentary
It stays intact while the only dated primary print is an opening ask, October’s price window is still open, and no named customer acceptance of $4 is on the record.
Practical takeaways
- Maeil Business dated a real Samsung mid-to-high $4/Gb HBM4 2027 opening ask on 2 Oct — that is the primary trigger
- HBM3E ~$1.50/Gb and >3× are MK’s reference framing; treat mid-$4 as ask, not ASP
- Volumes largely negotiated; price close this month is the live clock
- Who gets paid if it clears: Samsung (and peers) on qualified 2027 HBM4 invoices; customers pay the premium
- Stuck step remains ask ≠ cleared ASP — ready is not paid
- TrendForce +121% and Micron “far higher” are context only inside MK
- Cross-link wafer-mix and yield Pulses; do not flatten them into this ask
- Watch any dated ASP close through October, then maker earnings colour on HBM4 mix
FAQ
What did Maeil Business report about Samsung’s HBM4 price?
On 2 Oct 2026, Maeil Business reported exclusively that Samsung Electronics recently offered prices in the mid-to-high $4 range per gigabit for 2027 HBM4 annual supply contracts — more than three times HBM3E at around $1.50/Gb. Volumes for a substantial share of next year’s major HBM are already negotiated; price talks were expected to enter final stages this month.
Is mid-to-high $4/Gb a settled contract ASP?
No. It is Samsung’s opening ask in annual-supply talks, as reported by Maeil Business. Cash clears when customers counter, qualify volume, and lock the annual contract ASP — not when the exclusive hits. Ask ≠ ASP.
Who gets paid in this Korea read?
If the premium sticks on qualified 2027 HBM4 volume: Samsung (and peers with pricing power) on HBM4 invoices; customers pay the performance premium. This is a map of who gets paid — not a buy list.
What is the stuck step?
Ask ≠ cleared ASP. Volumes are largely negotiated; October’s price close plus qualification and yield still gate cash. Ready is not paid.
How is this different from the wafer-mix and yield Pulses?
The 30 Sep Pulse led on Kim Taewoo’s ~20%→~30% HBM share of industry DRAM wafers; the 21 Sep Pulse led on Samsung HBM4 yield near 80%. This Pulse leads on the 2 Oct Maeil opening-ask print. Cross-link those clocks; do not re-lead them.
Is this investment advice?
No. Education only. It maps who gets paid and which step is stuck. It is not a recommendation to buy or sell any security.
Keep reading on the map
- Korea Markets hub — country door
- Wire: Samsung mid-$4/Gb HBM4 ask — thin same lead
- Korea HBM DRAM capacity mix (30 Sep) — wafer-pool clock
- Samsung HBM4 yield Pulse (21 Sep) — yield door
- If HBM takes ~30% wafer share — Analysis
- HBM, explained — primer
- Taiwan Chiayi packaging land (3 Oct) — neighbour packaging
- Semiconductors stack — layer map
How we check this
Figures come from dated Maeil Business exclusive reporting and labelled secondary Korea press (SED, Businesskorea). Opening asks are not treated as settled ASPs. Where we work something out ourselves, the arithmetic is shown in full and labelled our arithmetic.
Last reviewed: 3 Oct 2026 · Next review: after any dated 2027 HBM4 contract-ASP print or Samsung/SK earnings colour on HBM4 mix
Spot an error? Tell us and we will correct it and note the change here.
Not investment advice. Do your own research.
Sources
- Maeil Business English exclusive (2 Oct 2026): mk.co.kr/en
- Maeil Business Korean twin (2 Oct 2026): mk.co.kr
- Seoul Economic Daily (1 Oct 2026): en.sedaily.com
- Businesskorea (23 Sep 2026): businesskorea.co.kr