Wafers Ramp: Who Gets Paid While Taiwan's CoWoS Still Binds
TSMC on 15 Oct printed Q3 sales of US$46.72bn. Who gets paid is TSMC on the wafer; CoWoS is still the stuck step.

TSMC printed third-quarter results on 15 October. Consolidated sales were NT$1,494.24 billion, or US$46.72 billion, above the top of its own guide. Who gets paid is TSMC on the leading-edge wafer — 2-nanometer already 8% of wafer revenue — and on the CoWoS slots buyers still cannot get enough of. The stuck step is still CoWoS: wafers ramped; C.C. Wei said demand is still above supply and the back end is still a little short.
TAIWAN PULSE · Data as at 21 Oct 2026 · Next update: after TSMC October revenue or a named CoWoS volume print
Affects: Semiconductors · CoWoS · Hyperscalers — Markets: Taiwan · US · Korea
Education only, not advice to buy or sell any security. Figures: TSMC 15 Oct 2026 earnings release, management report and call; TSMC 8 Oct September revenue; our 16 Sep Taiwan pulse. Own sums are labelled “our arithmetic”.
The numbers that matter this month
Q3 revenue
US$46.72bn
NT$1,494.24bn · +16.2% QoQ · +41.2% YoY in US$
Above guideQ3 vs own guide
+2.01%
Guide was US$44.6–45.8bn · beat vs high end (our arithmetic)
Headline2nm share of wafer revenue
8%
Was 3% in Q2 · advanced nodes 79%
RampGross margin
66.4%
Q2 67.7% · guided 65–67% · 2nm dilution named
HoldingQ4 revenue guide
US$52.3–54.3bn
+14% sequential at the midpoint, company said
Next clockCoWoS / back end
Still a little short
Wei: CoWoS still #1 choice · GF on interposers
Stuck stepStatus chips are Second Order’s read. Figures come from TSMC’s 15 October 2026 earnings release and call, and the 8 October September revenue print.
Why does Taiwan matter now?
Because the 15 October print is the receipt on the two Taiwan steps that still decide how many AI chips reach a hall: the leading-edge wafer, and the CoWoS package that turns that wafer into something that ships.
Every AI build still starts with the same shopping list: accelerators, memory, and servers. The buyers sit in the US — hyperscalers and neoclouds. A large share of what they spend still clears in Taiwan. Our 16 September gold pulse said the next hard data was TSMC’s Q3. This pulse is that receipt.
Other Taiwan doors this month: Nanya’s DRAM ASP, Taipower’s grid, September exports, and supplier parks in Texas. Today is the foundry book those prints sit next to.
1 · Leading-edge wafers
Who: TSMC
Paid: US$46.72bn of Q3 sales; 2nm 8% of wafer revenue
2 · 2nm ramp
Who: TSMC, Hsinchu and Kaohsiung
Paid: newest wafers; margin thins 1.3 points as the line starts
3 · CoWoS packaging
Who: TSMC; ASE as overflow; GlobalFoundries on interposers
Paid: price per package slot; still booked ahead
4 · Servers and racks
Who: Foxconn, Quanta, Wistron
Paid: volume after the package exists
Labels: Paid on the wafer = revenue as leading-edge chips bill. Ramping = 2nm is now a real mix line, not a footnote. Stuck step = CoWoS still sets who ships on time.
If you only remember one thing: a US$46.72 billion quarter is a wafer print. It is not a CoWoS-volume print. The package is still the bind.
What changed on 8–15 October
Two TSMC papers. One monthly. One quarterly. Together they close the arithmetic we set on 16 September.
On 8 October TSMC printed September revenue of NT$511.86 billion, down 0.6% from August’s NT$514.81 billion and up 54.6% from September 2025. January–September sales were NT$3,898.73 billion, up 41.1%. The same figures sit in the 8 October Form 6-K.
On 15 October TSMC printed the quarter. The earnings release and the 15 October Form 6-K give Q3 revenue of NT$1,494.24 billion and US$46.72 billion, net income of NT$763.06 billion, and diluted EPS of NT$29.43. Sales rose 50.9% year-over-year in NT dollars and 16.2% sequentially in US dollars. Gross margin was 66.4%.
The mix is the new fact. 2-nanometer was 8% of wafer revenue, from 3% in Q2; 3-nanometer 33%; 5-nanometer 28%; 7-nanometer 10%; advanced nodes 79%. HPC rose 22% quarter-on-quarter to 68% of revenue. Wendell Huang named the 2nm ramp as the reason gross margin fell 1.3 points from Q2’s 67.7%.
The outlook is the second new fact. Q4 is guided at US$52.3–54.3 billion, +14% sequential or +58% year-over-year at the midpoint, at NT$31.8. Gross margin 65–67%. C.C. Wei raised full-year 2026 US-dollar growth to around 44%, from “slightly above 40%” on the Q2 call. CapEx stays US$60–64 billion. He said TSMC is building 13 leading-edge and advanced-packaging fabs in Taiwan, plus five to six overseas.
On packaging, Wei did not give a CoWoS wafer-start number. He said CoWoS is still customers’ number-one choice; TSMC is in real-world production of 5× reticle-size packages with “excellent” yield; 9× and 14× are in work; CoPoS is for later cost reduction. He also said TSMC has “a little bit shortage on the back end” and is using a GlobalFoundries interposer deal so customers are not left short. Demand, after TSMC’s own check of US data-centre build-out and power, is still “far above our capability today to supply.”

Our math: labelled our arithmetic
TSMC already printed the dollars. What follows is division on those figures, labelled as ours.
- The 16 September test. Our gold pulse said July plus August were NT$982.4bn. At NT$32, Q3 guidance of US$44.6–45.8bn was NT$1,427.2–1,465.6bn. September needed NT$444.8bn for the low end and NT$483.2bn for the high end. September printed NT$511.86bn — NT$28.66bn, or 5.93%, above the high-end need (our arithmetic).
- The quarter versus the guide. US$46.72bn versus the high end of US$45.8bn is a 2.01% beat. Versus the US$45.2bn midpoint it is 3.36% (our arithmetic). Huang said the US-dollar print sat above the high end.
- Wafers versus dollars. Shipments were 4,476 thousand 12-inch equivalents, up 3.2% from 4,336. Revenue rose 17.6% in NT. Revenue per thousand wafers rose 13.94% (our arithmetic). Mix and price did more work than unit volume.
- HPC and 2nm. HPC at 68% of Q3 sales is about NT$1,016bn versus about NT$838bn in Q2 — +21.2% (our arithmetic) against the stated +22%. 2nm from 3% to 8% is five mix points in one quarter (our arithmetic), the ramp Huang blamed for the 1.3-point margin dip.
- Operating versus net. Operating income rose 14.3% sequentially, to NT$876.45bn. Net income rose only 8.0% because non-operating items fell NT$61.24bn, from NT$95.83bn to NT$34.59bn (our arithmetic). The wafer book is cleaner than the net line.
- Cash and Q4. Operations generated about NT$920bn; CapEx was NT$443bn (US$13.8bn); implied free cash about NT$477bn (our arithmetic). Q4 midpoint US$53.30bn is 14.08% above Q3 (our arithmetic); the company said 14%. At NT$31.8 that midpoint is NT$1,695bn, or about NT$565bn a month if split evenly — above August’s record.


What this tells you: the wafer step billed more than the company told you to expect, the newest node is now large enough to move the mix, and the next quarter is guided still higher. It does not tell you what a TSMC share is worth. We do not do price calls.
Where does the money stick?
At the steps with the fewest good substitutes — the same rule as 16 September, with a Q3 receipt on the wafer.

1. TSMC, on the leading-edge wafer. US$46.72 billion is the P&L receipt. A 66.4% gross margin, inside the 65–67% guide, is the pricing-power receipt. 2nm at 8% of wafer revenue is the mix receipt. When one supplier does most of a step, that supplier keeps more of each dollar. That has not changed.
2. TSMC, and overflow packagers, on CoWoS. Wei said CoWoS is still the number-one choice and that TSMC is the only house he believes is in real production at 5× reticle size. He also said the back end is still a little short, which is why GlobalFoundries is now on interposers. ASE and Amkor remain the overflow names from our packaging-gate piece. A short packaging step keeps the slot price. It also keeps the wait.
3. Toolmakers, on the CapEx cheque. US$13.8 billion of Q3 capital spending, against a reiterated US$60–64 billion year, is cash leaving for tools. Huang said tool prices are rising, but most CapEx is still “related to the long-term demand.”
4. Server builders, on volume — after the package. Foxconn, Quanta and Wistron still ship the boxes. Many firms can build a rack. Fewer can bill a 2nm wafer or a 5× CoWoS package.
One-line rule: while this shape holds, the book is TSMC’s on the wafer, the wait is still CoWoS, and the rack is paid last.
Is CoWoS still stuck?
Yes. A US$46.72 billion wafer print is a foundry that can bill. It is not a packaging step that has caught demand.
Three things keep it stuck. First, this call. Wei did not retire the shortage. He said demand is still far above what TSMC can supply; that CoWoS remains customers’ first choice; that 5× is in production and 9× and 14× are still being built; and that the back end is still a little short, which is why a partner is now cutting interposers. Those are shortage words, not clearance words.
Second, the rest of the Taiwan door. Our 16 September pulse had TrendForce’s mid-year gap at about 20% and about 10% by year-end, with CoWoS capacity reported around 130,000 wafers a month by end-2026. Nothing in the 15 October materials replaced that map with a company number. We do not invent one. The 23 September Baipu mini-loop pulse and the 3 October Chiayi land pulse were capacity-construction prints. Construction is not a cleared slot.
Third, the adjacent clocks. Memory is still Korea’s door — see HBM, explained. Power is still the long clock, as the stuck-step Analysis mapped. Wei said US hall-and-power checks are “so far so good.” He did not cut customer forecasts for lack of power. Power stays a planning input. It does not steal the stuck-step name from CoWoS on this print.
If CoWoS volume cleared, the stuck step would move. The next candidates on this door are HBM attach and power for the halls that take the finished rack. Until a named packaging-volume print lands, read Taiwan AI hardware through CoWoS first. Start with CoWoS, explained if the family is new.
What dates matter
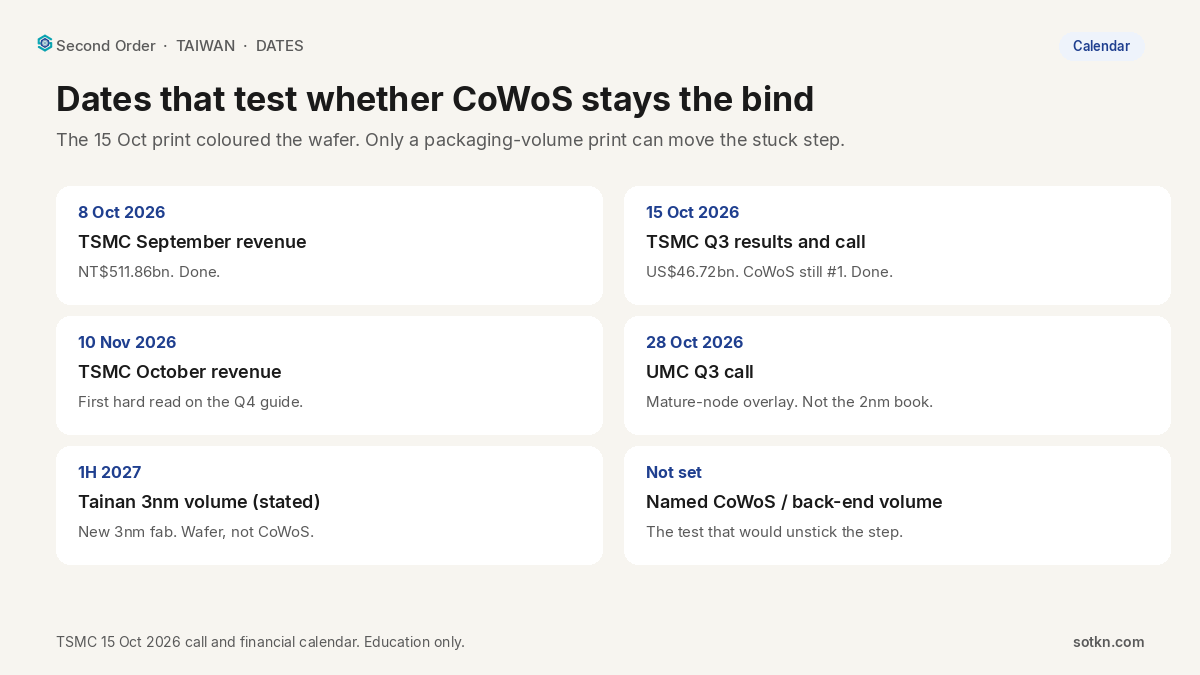
- 8 October 2026 — TSMC September revenue, NT$511.86 billion. Done. Cleared the 16 September high-end test.
- 15 October 2026 — TSMC Q3 results and call. US$46.72 billion. 2nm at 8%. CoWoS still first choice. Done.
- 28 October 2026 — UMC’s Q3 investor call. Mature-node overlay. Do not mix it with the 2nm book.
- 10 November 2026 — TSMC October revenue. The test: does the first Q4 month sit near our even-split NT$565bn?
- First half of 2027 — Tainan’s new 3nm fab, volume, as stated. A wafer date, not a CoWoS date.
- Third quarter of 2027 — Arizona’s second fab, volume, slightly ahead of the prior schedule.
- Not set — a named CoWoS or back-end volume print, or shorter lead times for buyers outside the top tier. That is the test that would move the stuck step.
The 15 October filing coloured the wafer. Only a packaging-volume print, or a lead-time print that shows open slots, can move the stuck step.
How is this different from the September revenue Pulse?
The 16 September gold pulse, TSMC Revenue, CoWoS and What’s Next, was a monthly-sales print plus a Q3 arithmetic problem. Who got paid was TSMC on the wafer and on CoWoS. The stuck step was CoWoS. September needed NT$483.2bn to clear the high end of guidance on our math.
Today is the quarterly receipt that solves that problem. Who gets paid is still TSMC on the wafer — now with 2nm at 8% of mix — and on CoWoS. The stuck step is still CoWoS. September printed NT$511.86bn. Q3 printed US$46.72bn. The gold pulse asked what September had to show. This pulse is what it showed, plus the call that said the back end is still a little short.
It is also different from the 15 October Wire catalyst brief on the same print — a short flag — and from Nanya’s DRAM pulse (stuck on 3D stacks) and Hygon’s China pulse (stuck on advanced HBM). Same earnings week. Different desk, different stuck step.
What would change this view?
- TSMC, on a later call, gives a CoWoS or advanced-packaging wafer-start number that shows supply catching the demand it still calls “far above.”
- Lead times shorten for buyers outside the top tier — the most honest sign the slot is unstuck.
- A second packager qualifies on a leading AI chip, not only announces a capability or an interposer deal.
- Gross margin falls below the guided 65–67% for reasons other than the named 2nm and overseas-fab ramps.
- October monthly sales, due 10 November, break sharply below the Q4 run-rate our arithmetic implies.
- Wei, or a later print, names memory or power — not packaging — as the louder bind, with a number attached.
- A hyperscaler or neocloud cuts 2027 capex before the 13 Taiwan packaging-and-logic fabs Wei described are working.
The view stays intact while monthly sales hold near record, margins stay in the mid-60s for the named reasons, and CoWoS remains the stated first choice.
Practical takeaways
- TSMC, 15 Oct: Q3 sales NT$1,494.24bn / US$46.72bn, +16.2% QoQ in US$, above a US$44.6–45.8bn guide
- Net income NT$763.06bn; EPS NT$29.43; gross margin 66.4% on named 2nm dilution
- 2nm 8% of wafer revenue, from 3% in Q2. HPC 68% of sales. Q4 guided US$52.3–54.3bn; full-year growth now around 44%
- Our arithmetic: September cleared the 16 Sep high-end need by NT$28.66bn; Q3 beat the guide high by 2.01%; revenue per wafer +13.94% on 3.2% more wafers
- Who gets paid: TSMC on the wafer and on CoWoS; toolmakers on US$13.8bn of Q3 CapEx; servers on volume after the package
- Stuck step: CoWoS. Wei: still the first choice; 5× in production; back end still a little short
- Watch 10 November October sales, a named CoWoS volume print, and lead times outside the top tier
FAQ
What did TSMC print on 15 October 2026?
A third-quarter earnings release and call. Consolidated revenue was NT$1,494.24 billion, or US$46.72 billion, above the company’s US$44.6–45.8 billion guide. Net income was NT$763.06 billion. Diluted EPS was NT$29.43. Gross margin was 66.4%. 2-nanometer was 8% of wafer revenue. Q4 revenue was guided at US$52.3–54.3 billion.
Who gets paid on this print?
TSMC, on the leading-edge wafer and on CoWoS slots. Tool suppliers, on US$13.8 billion of third-quarter capital spending. Server builders, on volume after a package exists. This is a map of who gets paid, not a buy list.
Why is CoWoS still the stuck step if wafers ramped?
Because a billed wafer is not a finished accelerator. Wei said CoWoS is still customers’ first choice, that TSMC is in production at 5× reticle size, and that the back end is still a little short. Demand, after TSMC’s own US hall-and-power check, is still above what it can supply. Sales are a wafer print. CoWoS is a slot print.
Did TSMC beat its own Q3 guidance?
Yes, in US dollars. The print was US$46.72 billion. The guide was US$44.6–45.8 billion. That is 2.01% above the high end on our arithmetic. Huang said the US-dollar result sat above the high end.
Is this investment advice?
No. Education only. It maps who gets paid and which step is stuck. It is not a recommendation to buy or sell any security.
Keep reading on the map
- Taiwan Markets hub — country page
- TSMC August revenue pulse (16 Sep) — the Q3 arithmetic this print closes
- TSMC, CoWoS and the packaging gate — why the slot is the finish line
- Wire catalyst on this print — the short flag
- CoWoS, explained — the stuck-step family
- HBM, explained — the short memory clock
- Where the stuck step moves — members’ map, packaging to power
- All Markets doors
How we check this. P&L, mix, guidance and CapEx: TSMC 15 October 2026 earnings release, management report and call, and the 15 October Form 6-K. September sales: TSMC 8 October revenue report and Form 6-K. Sequential tests versus the 16 September gold pulse: our arithmetic. CoWoS still short: Wei’s 15 October remarks, not a new TrendForce capacity number. Analyst targets left out. Own sums labelled “our arithmetic”. Our editorial standards →
Not investment advice. Do your own research.
References
- TSMC, TSMC Reports Third Quarter EPS of NT$29.43, 15 Oct 2026. pr.tsmc.com — Q3 sales, profit, EPS, margins, node mix, Q4 guide.
- TSMC, Form 6-K, 15 Oct 2026. sec.gov — same release plus presentation exhibit.
- TSMC, 3Q26 Management Report, 15 Oct 2026. investor.tsmc.com — sequential P&L, wafer shipments, cash, CapEx.
- TSMC, Q3 2026 earnings-call transcript, 15 Oct 2026. investor.tsmc.com PDF — 2nm dilution, 44% year, CoWoS, GF interposers, demand vs supply.
- TSMC, September 2026 Revenue Report, 8 Oct 2026. pr.tsmc.com — NT$511.86bn, −0.6% MoM, +54.6% YoY.
- TSMC, Form 6-K, 8 Oct 2026. sec.gov — September and January–September sales table.
- Second Order, TSMC Revenue, CoWoS and What’s Next for Taiwan’s AI Chips, 16 Sep 2026. sotkn.com — the Q3 arithmetic this print closes.