
Eighty Won Kept: Who Gets Paid While SK hynix HBM4 Stays Booked
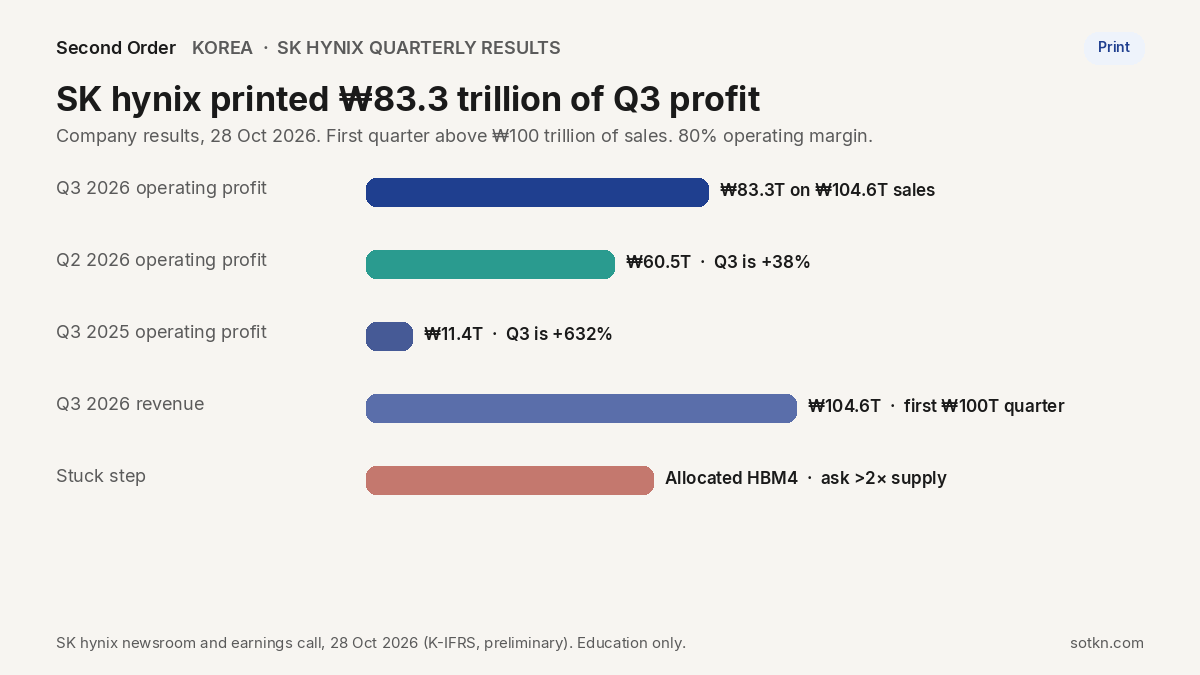
SK hynix on 28 October printed ₩104.6 trillion of third-quarter sales and ₩83.3 trillion of operating profit, an 80% margin. Who gets paid is the memory maker on allocated HBM4. The stuck step is still those stacks.

SK hynix printed its first ₩100 trillion sales quarter on 28 October: ₩104.6155 trillion of revenue, ₩83.3338 trillion of operating profit, an 80% margin on the company’s rounding. Who gets paid is SK hynix, on allocated HBM4 and server DDR5, and the shareholders the board just voted ₩14 trillion of cash. The stuck step is still those stacks. Customer ask is more than twice what it can ship, M15X is not yet at maximum, and long-term agreements already cover more than half of 2027–28 capacity.
KOREA PULSE · Data as at 28 Oct 2026 · Next update: after Samsung’s Q3 call on 29 Oct or a named M15X capacity print
Affects: Semiconductors · HBM · Hyperscalers — Markets: Korea · Taiwan · US
Education only, not advice to buy or sell any security. Company figures: SK hynix newsroom and earnings call, 28 October 2026, preliminary K-IFRS. Consensus from LSEG SmartEstimates as reported by CNBC the same day. Own sums are labelled “our arithmetic”.
The numbers that matter this month
Revenue, Q3 2026
₩104.6155T
+32% QoQ · +328% YoY · first ₩100T sales quarter
HeadlineOperating profit, Q3 2026
₩83.3338T
+38% QoQ · +632% YoY · margin 80%
Paid on the stackProfit per ₩100 of sales
₩80
Our arithmetic 79.7% · company prints 80% · Q2 was ₩76
Our mathNet cash, 30 Sep 2026
₩98.7T
Cash ₩114.5T · borrowings ₩15.8T · cash +₩26.5T on the quarter
Cash, not just profitShareholder returns, FY2026 plan
~₩100T
≥₩30T cash dividends · ≥₩60T buybacks · Q3 dividend ₩14T
Paid to the registerAllocated HBM4
Still the bind
Ask more than 2× supply. LTAs with 14 customers, >50% of 2027–28 capacity. M15X not yet at max.
Stuck stepStatus chips are Second Order’s read. Figures: SK hynix newsroom and earnings call, 28 Oct 2026.
Why does Korea matter now?
Because this morning’s print is the P&L receipt on the memory door. Taiwan packages the accelerator. Korea stacks the high-bandwidth memory beside it. An empty HBM socket on a GPU interposer is not a shipment. The 28 October numbers say who got paid for filling some of those sockets in July to September, and they say the rest of the sockets are still a queue.
Every AI build still starts with accelerators, memory and servers. The buyers sit in the US — hyperscalers and neoclouds. A large share of the memory spend still clears in Korea. The 18 September pulse was Q2: 76% margin, HBM allocated. The 8 October Samsung pulse was the other Korean memory maker’s preliminary. Today is SK hynix’s actual third quarter. Not a Samsung reprint, not an export print, not a fab-power story.
1 · SK hynix, on allocated stacks
Who: SK hynix, selling HBM4 and server DDR5 under contract
Paid: ₩83.3338T operating profit on ₩104.6155T of sales — ₩80 of each ₩100 (our arithmetic)
2 · Shareholders, on the cash
Who: The register, via the 28 Oct board resolutions
Paid: ₩14T Q3 cash dividend (₩20,000 a share) and ₩20T of share purchases; year plan about ₩100T
3 · Buyers, who pay the ASP
Who: Cloud firms and server builders taking DRAM and HBM
Paid: DRAM ASP high-20s percent up on the quarter; they still cannot book a free queue
4 · Allocated HBM4 / M15X
Who: The Cheongju ramp and the 2027–28 contract book
Paid: Not as open supply. Empty amber sockets on this morning’s cover are not a shipment
Labels: Paid first = 80% of sales as operating profit. Stuck step = ask more than twice supply; M15X still ramping.
If you only remember one thing: an 80% margin is a price-and-mix receipt, not a free HBM4 queue. Start with HBM, explained if the stack is new.
What changed on 28 October
One company paper, one call. The paper is the P&L. The call is the mix, the allocation language, and the cheque to shareholders.
The newsroom release put third-quarter revenue at ₩104.6155 trillion, operating profit at ₩83.3338 trillion (80% margin) and net profit at ₩39.7756 trillion. Against the second quarter (₩79.3187 trillion of sales, ₩60.5426 trillion of profit) that is +32% and +38%. Against a year earlier (₩24.4489 trillion and ₩11.3834 trillion) that is +328% and +632%. First quarter above ₩100 trillion of sales; sixth consecutive record. Preliminary K-IFRS, review not finished.
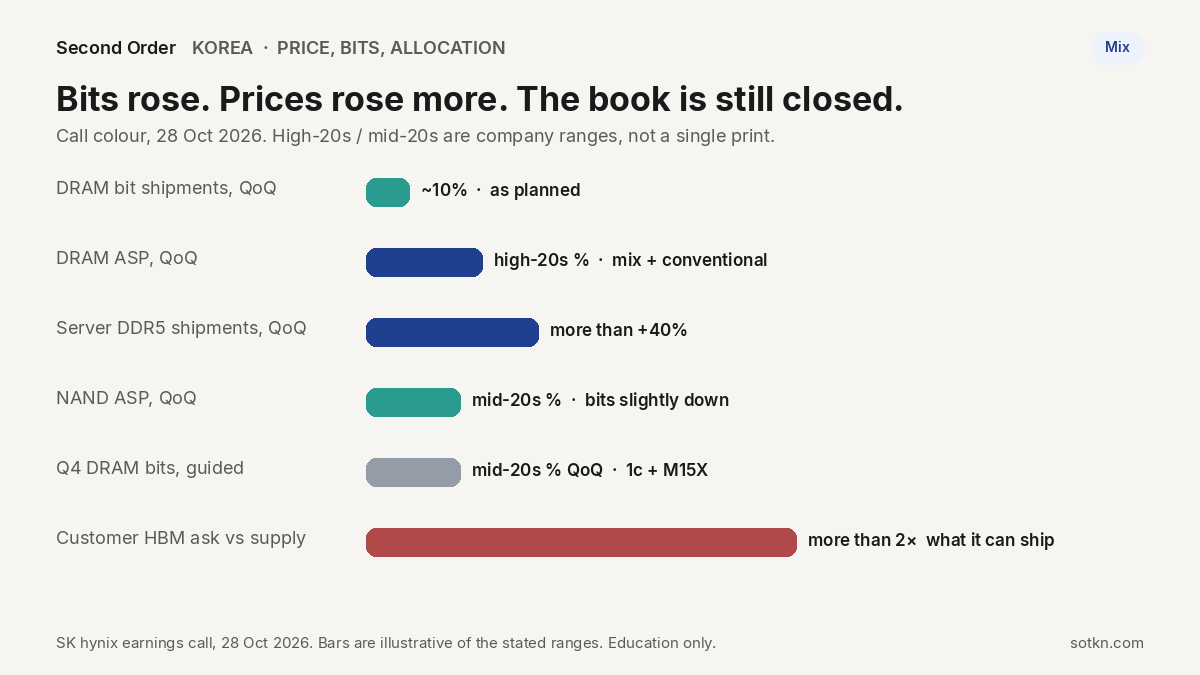
Cash moved with the profit: ₩114.5 trillion of cash, up ₩26.5 trillion; borrowings ₩15.8 trillion, down ₩2.8 trillion; net cash ₩98.7 trillion. DRAM bits rose about 10% “as planned.” HBM4 mass shipments began in earnest. Server DDR5 shipments rose more than 40%. DRAM ASP rose a high-20s percent. NAND bits slipped as the mix moved to 321-layer TLC eSSD; NAND ASP rose a mid-20s percent. EBITDA ₩87.7 trillion, 84% margin, after ₩4.3 trillion of depreciation.
Net did not follow operating profit. The CFO booked ₩11.6 trillion of FX losses and ₩22.9 trillion of investment-asset marks, ₩32.6 trillion of net non-operating expenses. Pretax ₩50.7 trillion. Net ₩39.7756 trillion is 58% below Q2’s ₩93.9226 trillion, which had carried a Kioxia gain. Accounting overlay. Not the stuck step. CNBC put LSEG SmartEstimates at ₩98.34 trillion of sales and ₩76.72 trillion of profit, and converted sales at about US$78.86 billion. Consensus is press, not a company print.
The bind is the allocation language. LTAs with 14 customers, including leading cloud firms, cover more than 50% of 2027–28 capacity. Typical term five years, some extensions under discussion, deposits so plans become orders. Combined with demand still being discussed, the CEO said DRAM and HBM through 2029 are “effectively sold out.” HBM sales said customer ask is more than twice what it can ship. HBM4 twelve-high shipments are on the agreed schedule. M15X in Cheongju is being taken to maximum by year-end; HBM4 should surpass HBM3E in Q4 volume and revenue. Yield is above the planned full back-end target. None of that is a named wafer-start number. We do not invent one.
The cheque: about ₩100 trillion of FY2026 returns — ≥₩30 trillion of cash dividends and ≥₩60 trillion of buybacks, including the ₩40 trillion finished last week. Board: ₩14 trillion Q3 cash dividend (₩20,000 a share, half a Kioxia special) and a ₩20 trillion share purchase, of which ₩10 trillion is cancelled for shareholders and ₩10 trillion is employee compensation, not in the return total. Solidigm’s IPO review was discontinued. Financing overlay. Not this pulse’s stuck step.
Our math: labelled our arithmetic
The company already printed the won. What follows is division on those figures, labelled as ours.
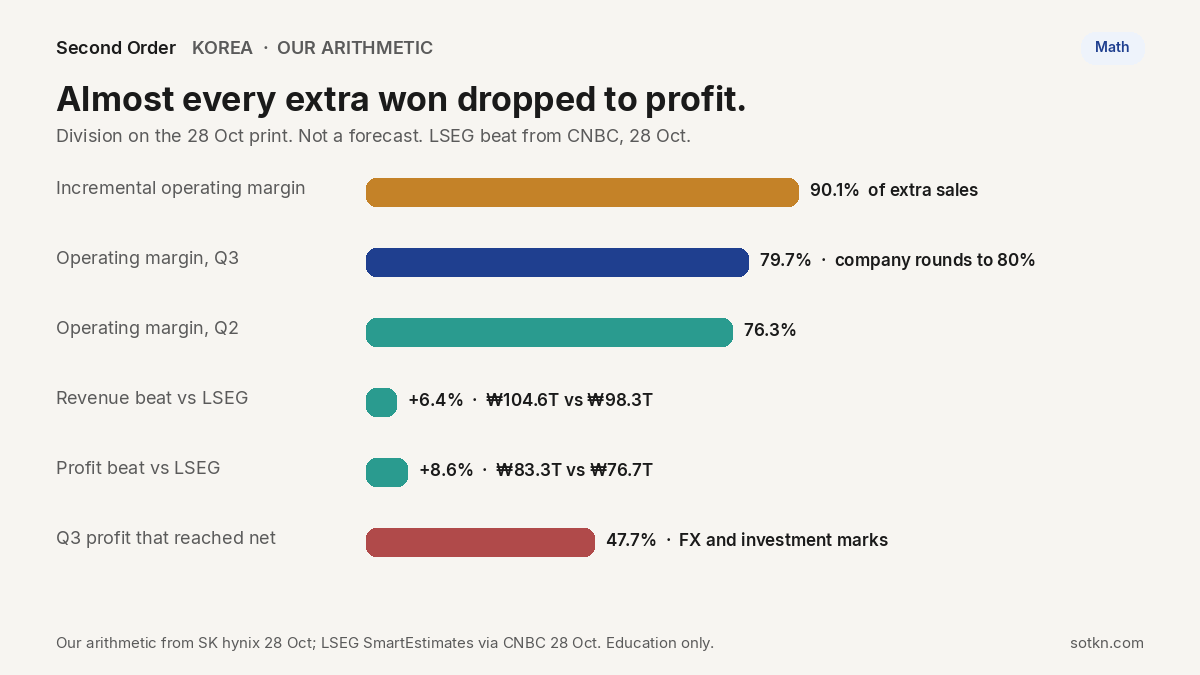
- The margin. 83.3338 ÷ 104.6155 = 79.66% (our arithmetic). We round that to ₩79.7 of each ₩100 of sales. The company prints 80%. Second-quarter 60.5426 ÷ 79.3187 = 76.33%, which it had printed as 76%. Three points of mix and price, not a new factory.
- The extra won. Sales rose ₩25.2968 trillion on the quarter. Operating profit rose ₩22.7912 trillion. That is an incremental operating margin of 90.1% (our arithmetic). Almost every extra won of sales dropped to operating profit. That is the signature of price and mix, not of a sudden jump in wafers.
- The beat. Against CNBC’s LSEG SmartEstimates, ₩104.6155 trillion versus ₩98.34 trillion is 6.4% above; ₩83.3338 trillion versus ₩76.72 trillion is 8.6% above (our arithmetic). Consensus is press. The company does not print a beat.
- What reached net. 39.7756 ÷ 83.3338 = 47.7% of operating profit reached net (our arithmetic). The rest is ₩32.6 trillion of non-operating items and about ₩10.9 trillion of tax on ₩50.7 trillion pretax, 21.5% effective (our arithmetic).
- The dividend against the quarter. ₩14 trillion is 16.8% of quarterly operating profit (our arithmetic). The ₩24 trillion of Q3 return the CFO isolated (dividend plus the cancelled ₩10 trillion) is 28.8% of operating profit. The ₩100 trillion year plan is 95.6% of this quarter’s sales. A cheque against a scarce step is not the step coming unstuck.
What this tells you: the P&L is a price-and-mix print. Bits rose about 10%. ASP rose high-20s. Incremental profit took 90% of extra sales. What it does not tell you: what a share is worth, or how many HBM4 cubes M15X will add in November. We do not do price calls. A margin is not a capacity print.
Where does the money stick?
At the step with the fewest qualified suppliers, on the stacks that are still allocated, not on the sockets that are still empty.
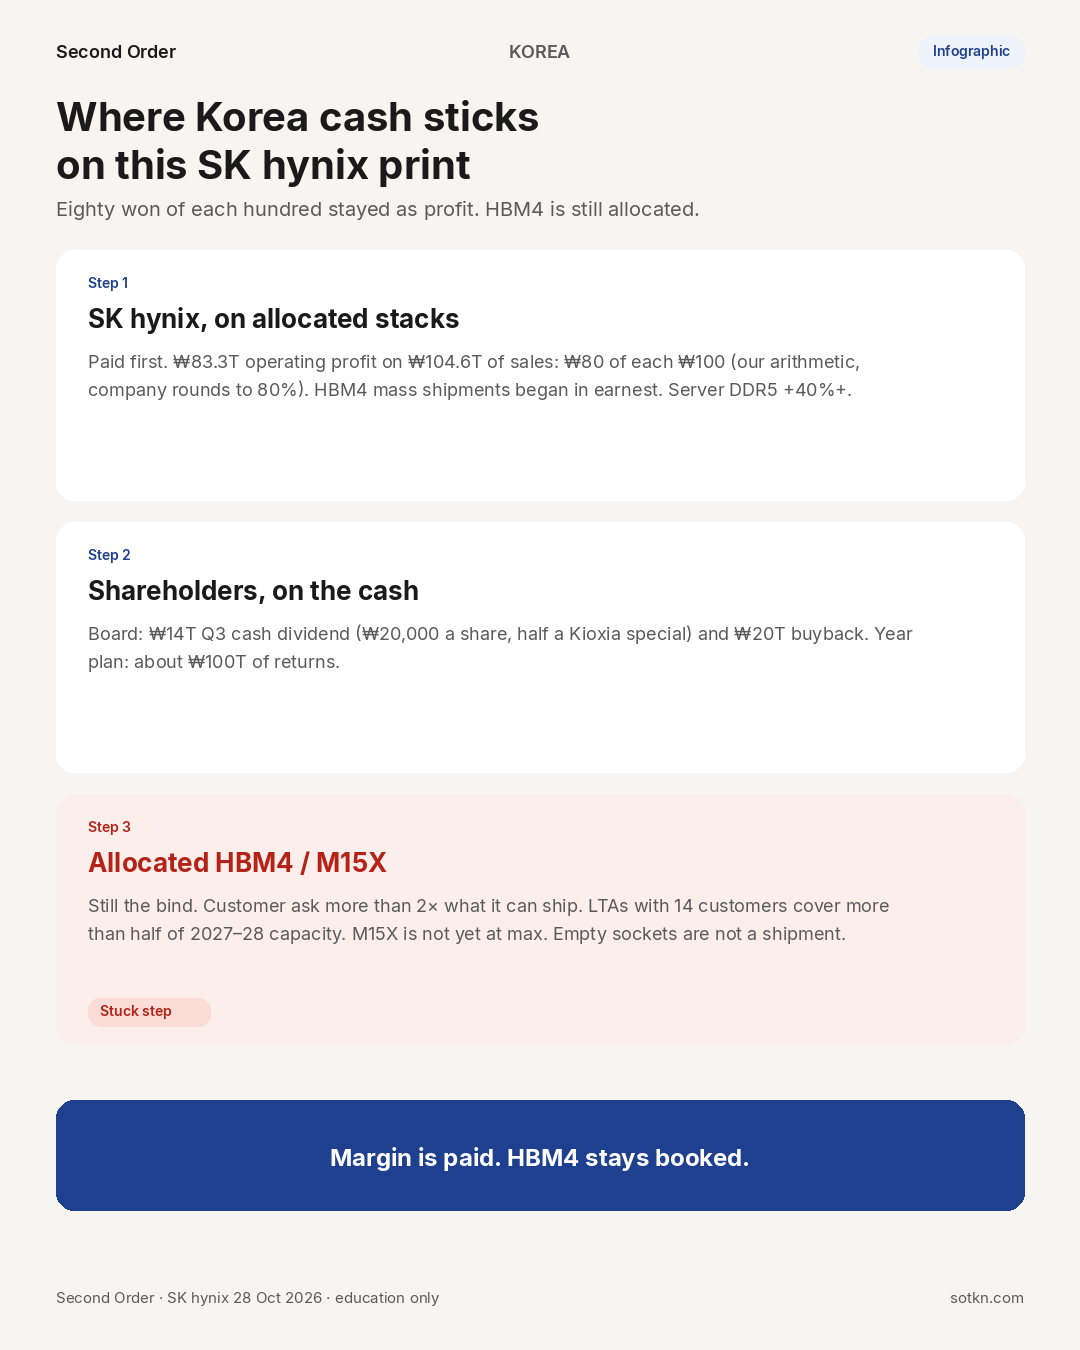
1. SK hynix, on allocated HBM4 and server DDR5. ₩83.3338 trillion of operating profit on ₩104.6155 trillion of sales is the receipt. DRAM did the work: bits +10%, server DDR5 +40%+, ASP high-20s, HBM4 in earnest. When three suppliers do AI-class HBM and one is first on the leading platforms, that supplier keeps more of each dollar. 76% becoming 80% is the evidence. See the HBM layer.
2. Shareholders, on the cash that followed. Net cash ₩98.7 trillion, a ₩14 trillion dividend, a ₩20 trillion buyback and a ₩100 trillion year plan are cash leaving after the scarce step has been paid. The Kioxia special is a one-off overlay. It does not loosen HBM4. Solidigm’s cancelled IPO is the opposite cheque. Financing is not the bind.
3. Buyers, who pay the ASP. Cloud firms and server builders take the bits and sit on the 14 LTAs. DRAM ASP high-20s is their invoice. Paying more is not a free queue. Hyperscaler capex is the demand clock — hyperscalers layer.
4. Toolmakers and the Yongin/M15X build, later. 2027 capex is guided “significantly” above 2026 as Yongin Phase 1 ramps. Tools are paid when a line is built. They are not the stuck step on an 80% quarter. The 8 October Samsung pulse put new cleanroom space on a 2027 clock. That longer clock is still there. It is not this morning’s bind.
One-line rule: while this shape holds, the book on price is the allocated-HBM4 step, the wait is M15X plus the 2027–28 LTA wall, and the register is being paid out of the cash that followed the margin.
Is allocated HBM4 still stuck?
Yes. An 80% operating margin is a factory system that can still bill at scarcity prices. It is not a stack the company can sell to whoever shows up with a purchase order.
Three things keep it stuck. First, this print: ask more than 2× supply; 14 LTAs covering more than half of 2027–28; DRAM and HBM through 2029 “effectively sold out” once demand under discussion is included. That is a booked list. Some customers, the HBM head said, are looking at lower stacks to get more cubes from the same bit pool. Shortage behaviour. Not relief.
Second, the ramp is not yet max. HBM4 mass shipments began in earnest only this quarter. M15X goes to maximum by year-end. Q4 DRAM bits are guided mid-20s percent up, from 1c and that HBM4 ramp together. Mid-20s bit growth on a sold-out book is catch-up, not surplus. Yield above plan is good for the cubes that run. It is not a named extra wafer-start. We do not convert a yield comment into a capacity print.
Third, the rest of the map. The 18 September pulse already had HBM allocated. This morning is the next generation of that list. Taiwan’s packaging clock is a neighbour — CoWoS, explained. If HBM4 loosened while CoWoS stayed tight, the bind would move back to Taiwan. If both loosened, the next candidate is power. Members’ map: Where does the stuck step move?. Until a later call names shorter mid-tier lead times, or a wafer-start that fills the 2× gap, this pulse’s bind stays allocated HBM4. Yongin Y1’s first cleanroom remains a February 2027 company target — the longer clock, not this quarter’s.
What dates matter
The 28 October print coloured the margin. Only a later capacity print, or Samsung’s split tomorrow, can move the read.
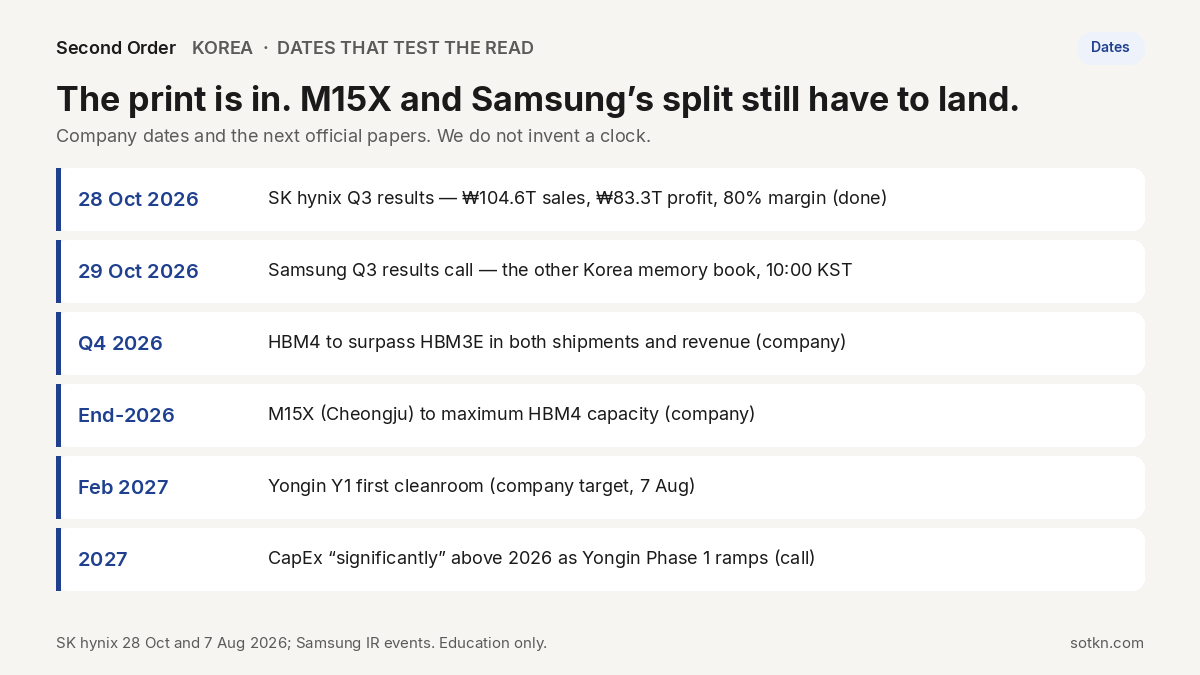
- 28 October 2026 — SK hynix Q3 results and call. ₩104.6155T sales, ₩83.3338T operating profit, 80% margin. Done.
- 29 October 2026, 10:00 KST — Samsung Q3 results call. The other Korea memory book, and the business split the 8 October guidance did not give.
- Q4 2026 — HBM4 to surpass HBM3E in both shipments and revenue (company). The test: does flagship mix arrive without the 2× ask cooling?
- End-2026 — M15X to maximum HBM4 capacity (company). The test: a named wafer or cube number, not only “maximum.”
- February 2027 — SK hynix Yongin Y1 first cleanroom (company target, 7 August). The longer clock, not this quarter’s bind.
- 2027 — CapEx “significantly” above 2026 as Yongin Phase 1 ramps (call). Tools get paid. Stacks still have to qualify.
- Not set — a public HBM4 wafer-start or mid-tier lead-time print. That would move the stuck step.
Only an M15X number, or a later call that retires the 2× ask, can move the stuck step.
How is this different from the Samsung Q3 guidance pulse?
The 8 October Samsung pulse was a preliminary: about ₩195 trillion of sales and ₩107.4 trillion of operating profit, no split, stuck step new cleanroom space on a 2027 clock. The split arrives tomorrow.
Today is a different paper. Who gets paid is SK hynix on allocated HBM4 and server DDR5 that printed an 80% margin, and the shareholders on a ₩100 trillion return plan. The stuck step is allocated HBM4 — M15X still ramping, ask more than 2×, 2027–28 more than half locked — not “new cleanrooms” as a generic. Same Korea door. Different company. Samsung’s 2027 cleanroom clock is still the longer one. This is the near clock: which stack billed, which socket is still empty. Different again from the 18 September HBM pulse (Q2, 76%). Members’ stuck-step map is the longer clock through memory to power.
What would change this view?
- A later call names HBM4 wafer-starts that close the 2× ask, or mid-tier buyers report shorter lead times.
- M15X hits year-end maximum and a customer says HBM4 is no longer the bind on GPU shipments.
- Q4 DRAM bits print well below the mid-20s guide, or ASP language turns flat.
- Samsung’s 29 October split shows memory profit rolling over, or a hyperscaler cuts 2027 capex before Yongin Y1 opens.
- A second supplier qualifies on the same leading HBM4 platform at similar timing.
- Packaging, not memory, becomes the louder bind, with a named CoWoS number attached.
The view stays intact while the operating margin holds in the high-70s to 80%, LTAs cover most near-term HBM, M15X is still described as a ramp rather than a surplus, and customer ask stays ahead of what the company says it can ship.
Practical takeaways
- SK hynix, 28 Oct: Q3 sales ₩104.6155T (+32% QoQ, +328% YoY). Operating profit ₩83.3338T (+38%, +632%), 80% margin
- Net ₩39.7756T after ₩32.6T of non-operating items. Cash ₩114.5T; net cash ₩98.7T
- Our arithmetic: ₩79.7 of each ₩100 (company 80%); incremental operating margin 90.1%; beat vs LSEG 6.4% sales / 8.6% profit
- Mix: DRAM bits ~+10%, ASP high-20s, server DDR5 +40%+. HBM4 in earnest; expected to surpass HBM3E in Q4
- Who gets paid: SK hynix on allocated HBM4 and server DDR5; shareholders on a ~₩100T FY2026 return plan
- Stuck step: allocated HBM4. Ask more than 2×. LTAs with 14 customers, more than half of 2027–28 capacity. M15X not yet at max
- Watch 29 Oct (Samsung Q3 call), Q4 HBM4 crossover, and a named M15X number by year-end
FAQ
What did SK hynix print on 28 October 2026?
Q3 revenue ₩104.6155 trillion (+32% QoQ, +328% YoY), first quarter above ₩100 trillion of sales. Operating profit ₩83.3338 trillion (+38%, +632%), 80% margin. Net profit ₩39.7756 trillion. Preliminary K-IFRS.
Who gets paid on this print?
SK hynix, on allocated HBM4 and server DDR5 — ₩80 of each ₩100 of sales on our arithmetic, 80% on the company’s rounding. Shareholders, on a ₩14 trillion Q3 cash dividend and a roughly ₩100 trillion FY2026 return plan. A map of who gets paid, not a buy list.
Why is allocated HBM4 still the stuck step if the margin is 80%?
A margin is a price-and-mix receipt, not a free queue. Customer HBM ask is more than twice supply, LTAs with 14 customers cover more than half of 2027–28 capacity, and M15X is still ramping. Empty sockets are not a shipment.
How is this different from Samsung’s 8 October guidance?
Samsung’s paper was a preliminary: about ₩195 trillion of sales and ₩107.4 trillion of operating profit, split due 29 October. This is SK hynix’s actual third quarter, with mix, HBM4 crossover language, and a named LTA book. Same door. Different company.
Is this investment advice?
No. Education only. It maps who gets paid and which step is stuck. It is not a recommendation to buy or sell any security.
Keep reading on the map
- Korea Markets hub — country page
- Korea HBM pulse (18 Sep) — the Q2 76% margin this print updates
- Samsung Q3 guidance (8 Oct) — the other Korean memory book
- HBM, explained — the stack
- Who makes HBM — the three-name list
- Where the stuck step moves — members’ map
- All Markets doors — Taiwan, Korea, US, China
How we check this. Third-quarter won, cash, mix comments, LTA coverage, M15X, HBM4 crossover, returns and Solidigm: SK hynix newsroom and earnings call, 28 October 2026. LSEG estimates and the dollar conversion: CNBC, 28 October. Yongin Y1 date: SK hynix, 7 August. Own sums labelled “our arithmetic”. Our editorial standards →
Not investment advice. Do your own research.
References
- SK hynix, 3Q26 Financial Results, 28 Oct 2026. news.skhynix.com
- SK hynix, FY2026 Q3 earnings call, 28 Oct 2026, 09:00 KST. skhynix.com/ir
- Investing.com transcript of the same call, 27–28 Oct 2026. investing.com
- CNBC, SK Hynix third-quarter profit, 28 Oct 2026. cnbc.com
- SK hynix, Form 6-K, Oct 2026. sec.gov
- SK hynix, Yongin Y2 and Cheongju M17 investment, 7 Aug 2026. news.skhynix.com
- Samsung Electronics, Q3 2026 earnings guidance, 8 Oct 2026. news.samsung.com
- Second Order, Korea HBM pulse, 18 Sep 2026. sotkn.com
- Second Order, Samsung Q3 guidance pulse, 8 Oct 2026. sotkn.com


