$29.4bn Split: Who Gets Paid When TSMC's August Check Is Not CoWoS Slots
September 2026 in one line: TSMC’s 24 Sep 6-K splits the August board check into $16.0bn advanced tools, $4.8bn packaging/mature, and $8.6bn property. Who gets paid is the toolmakers. The stuck step is still CoWoS — a check is not slots.
TSMC’s August board check is now a dated split, not a lump. On 24 September 2026 the company filed a Form 6-K for the month of August: US$16.035 billion of machinery for advanced-technology capacity, US$4.791 billion of machinery for advanced packaging, mature and/or specialty capacity, and US$8.616 billion of real estate and capitalized leased assets. Who gets paid is whoever sells those tools and those buildings. The stuck step is still CoWoS packaging: a board appropriation is not a yielded slot.
TAIWAN PULSE · Data as at 29 Sep 2026 · Next update: after TSMC September revenue (8 Oct) and Q3 results (15 Oct)
Affects: Semiconductors · Hyperscalers · Neoclouds — Markets: Taiwan · Korea · US
Education only, not advice to buy or sell any security. Figures are from company filings and government releases dated as shown.
The numbers that matter this month
August board check (6-K, 24 Sep 2026)
US$29.442bn
Matches the 11 Aug lump of US$29,442.50m
Fresh printAdvanced-technology machinery
US$16.035bn
54.5% of the August check · our arithmetic
Who gets paidPackaging, mature and/or specialty machinery
US$4.791bn
Bundled line · does not isolate CoWoS
Stuck step funded, not clearedReal estate and capitalized leases
US$8.616bn
29.3% of the check · shells and leased assets
Construction clockTaiwan export orders (Aug 2026)
US$102.96bn · +71.4% YoY
MOEA 22 Sep · first month above US$100bn
RecordIndustrial production index (Aug 2026)
145.97 · +23.47% YoY
MOEA 23 Sep · manufacturing 148.42, +24.61%
30th up monthSources: TSMC Form 6-K, 24 Sep 2026; TSMC board 6-K, 11 Aug 2026; MOEA export orders, 22 Sep 2026; MOEA industrial production, 23 Sep 2026. Status chips are Second Order’s read.
On this page: Why Taiwan? · What changed · Our math · Where money sticks · Is CoWoS still stuck? · Dates · vs Revenue / Baipu · What would change · FAQ
Why does Taiwan matter now?
Because the country that still finishes most leading AI accelerators just printed the line-item split of a US$29.4 billion August board check — in the same week that official orders and factory output set records. The question is who gets paid on which line, and whether the packaging line unsticks CoWoS.
Advanced tools
Who: TSMC’s leading-edge equipment vendors
Paid: US$16.035bn of August machinery appropriations
CoWoS packaging
Who: TSMC; ASE (incl. SPIL) as overflow
Paid: only when a die is joined to HBM and ships. The 6-K funds tools; it does not print slots.
Packaging / mature / specialty tools
Who: Tool vendors on the bundled US$4.791bn line
Paid: when TSMC takes equipment — mix unknown
Servers and orders
Who: Foxconn, Quanta, Wistron and the ICT chain
Paid: volume on MOEA’s ICT orders (+100.5%) and computer/opto production (+95.72%)
If you only remember one thing: the August check pays for tools and shells; CoWoS still sets who ships on time. New to the join step? Start with CoWoS, explained. The packaging gate sits on Taiwan’s CoWoS capacity Pulse. Memory stays on the Korea door.
What changed — the 24 Sep 6-K split, not another revenue month
The dated print is TSMC’s month-end Form 6-K, signed 24 September 2026, covering the month of August. Item 4 lists three capital appropriations:
- Machinery for advanced technology capacity: US$16,035 million.
- Machinery for advanced packaging, mature and/or specialty capacity: US$4,791 million.
- Real estate and capitalized leased assets: US$8,616 million.
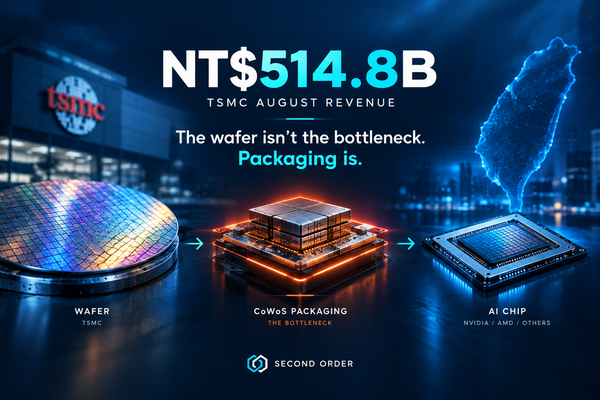
That is the trigger. August sales (NT$514.81 billion, 10 September) and the 21 September Baipu groundbreaking already have Pulses. This filing is the split of the August check.
The 11 August board 6-K had already disclosed a lump of approximately US$29,442.50 million. The 24 September report is the same vote with line items.
Same-week official statistics, not the lead but the demand clock. MOEA on 22 September: August export orders US$102.96 billion, +5.1% month-on-month, +71.4% year-on-year, first month above US$100 billion; January–August US$704.99 billion, +55.0%. Focus Taiwan, citing the same release, put electronics at US$45.75 billion (+83.9%) and ICT at US$34.21 billion (+100.5%); the US was the largest source at US$42.13 billion. MOEA’s September order forecast is US$106.0–109.1 billion.
MOEA on 23 September: industrial production 145.97, +23.47%; manufacturing 148.42, +24.61% — records, 30th up month. Computer and optoelectronics +95.72%; ICs +24.24%; machinery +18.65% on semiconductor equipment. September manufacturing is guided +22.5–25.8%.
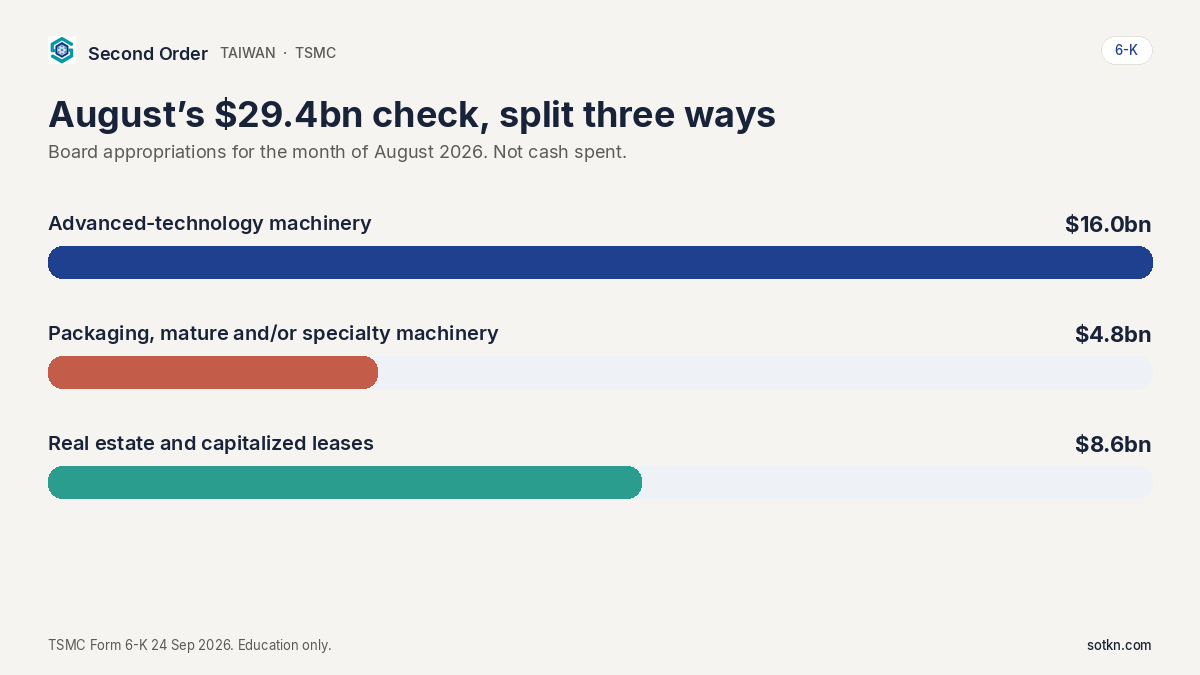
August’s US$29.4bn check, split three ways. Source: TSMC Form 6-K, 24 Sep 2026. Education only.
Two cautions before anyone treats US$4.791 billion as “the CoWoS number.” First, the line is bundled. Advanced packaging sits with mature and specialty tools. The filing does not say how much is CoWoS-S, CoWoS-L, SoIC, or a 28-nanometre specialty tool. Second, appropriation is not cash spent, and cash spent is not yielded wafers. TSMC’s full-year 2026 cash budget, raised on the 16 July Q2 call, is US$60–64 billion. Board checks through the year authorise tools with long lead times. They are allowed to exceed one year’s cash spend. We show that arithmetic next rather than dividing US$29.442 billion by US$62 billion and calling it “half the year in one month.” That would be the wrong object.
Our math — labelled our arithmetic
Second Order calculation from the dated 6-K line items. This is our arithmetic, not TSMC guidance and not a forecast of September cash capex.
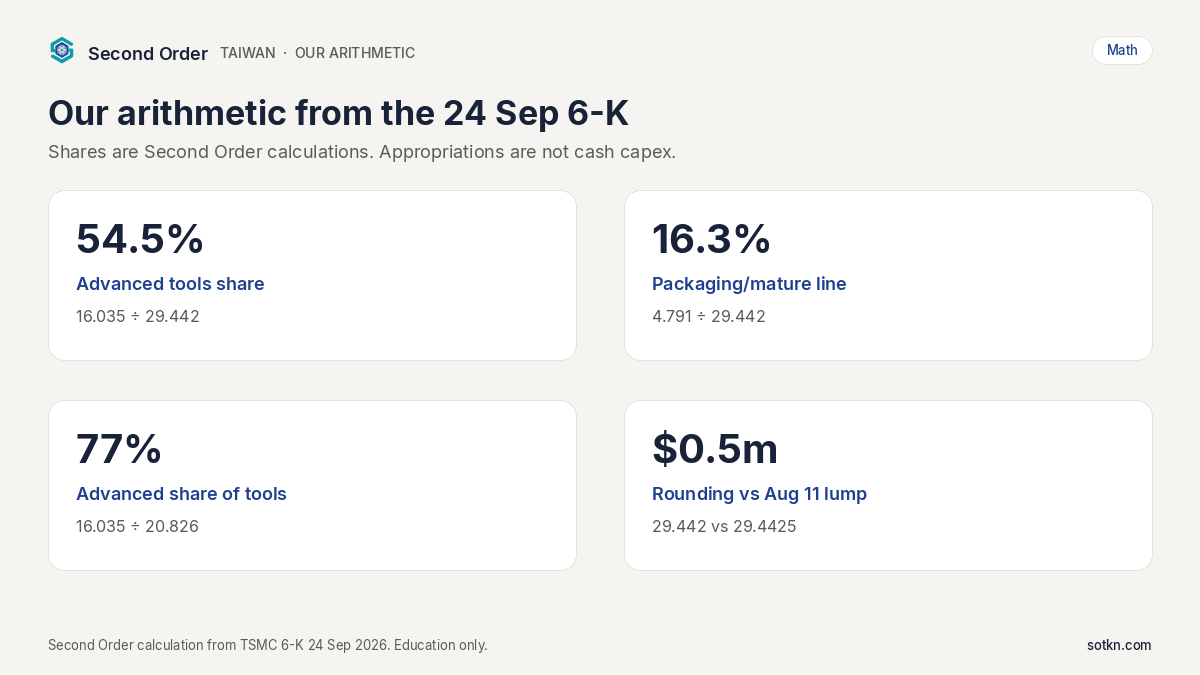
Our arithmetic from the 24 Sep 6-K. Appropriations are not cash capex. Education only.
Check the lump. 16.035 + 4.791 + 8.616 = 29.442. The 11 August board figure is US$29,442.50 million, or 29.4425. Difference: US$0.5 million. We treat the 24 September 6-K as the line-item split of that August vote, not as a second US$29 billion on top of it.
Shares of the August check. 16.035 ÷ 29.442 = 0.5446 → 54.5% advanced tools. 4.791 ÷ 29.442 = 0.1627 → 16.3% packaging/mature/specialty tools. 8.616 ÷ 29.442 = 0.2926 → 29.3% real estate and capitalized leases.
Tools only. Machinery is 16.035 + 4.791 = 20.826. Advanced share of tools: 16.035 ÷ 20.826 = 0.7699 → 77%. Packaging/mature share of tools: 4.791 ÷ 20.826 = 0.2300 → 23%. Useful as a mix of this month’s authorised tools. Not a clean CoWoS share, because of the bundle.
Do not add board lumps to the cash guide. TSMC’s 10 February board 6-K authorised about US$44,962 million; 12 May about US$31,284.30 million; August US$29,442.50 million. Sum: US$105.7 billion across three meetings — already larger than the US$60–64 billion cash budget. Authorisations can cover later years. Adding them is the wrong object.
Cash spent is the other clock. Q2 2026 management report: US$11.10 billion in Q1, US$15.70 billion in Q2, US$26.80 billion year-to-date. Midpoint of the cash guide is US$62 billion. 26.80 ÷ 62 = 43.2% spent in the first half. Remaining to midpoint: US$35.2 billion. That remaining cash is not August’s US$29.442 billion authorisation.
Orders mix, our subtraction. Electronics US$45.75 billion plus ICT US$34.21 billion = US$79.96 billion. 79.96 ÷ 102.96 = 0.7766 → 78% of August export orders. US orders US$42.13 billion ÷ 102.96 = 0.4092 → 41%. Those shares are Focus Taiwan’s breakdown of the MOEA print; the ministry’s own English summary on the news page is the US$102.96 billion / +71.4% headline.
What this tells you. The August check is real, large, and now split. Toolmakers are the cash step on the appropriation. Packaging is being funded on a bundled 16% line. It is not being cleared as a slot print.
What it does not tell you. How many CoWoS wafers per month this US$4.791 billion buys, which variant, or when those tools qualify. Price is a different question. We do not do price calls.
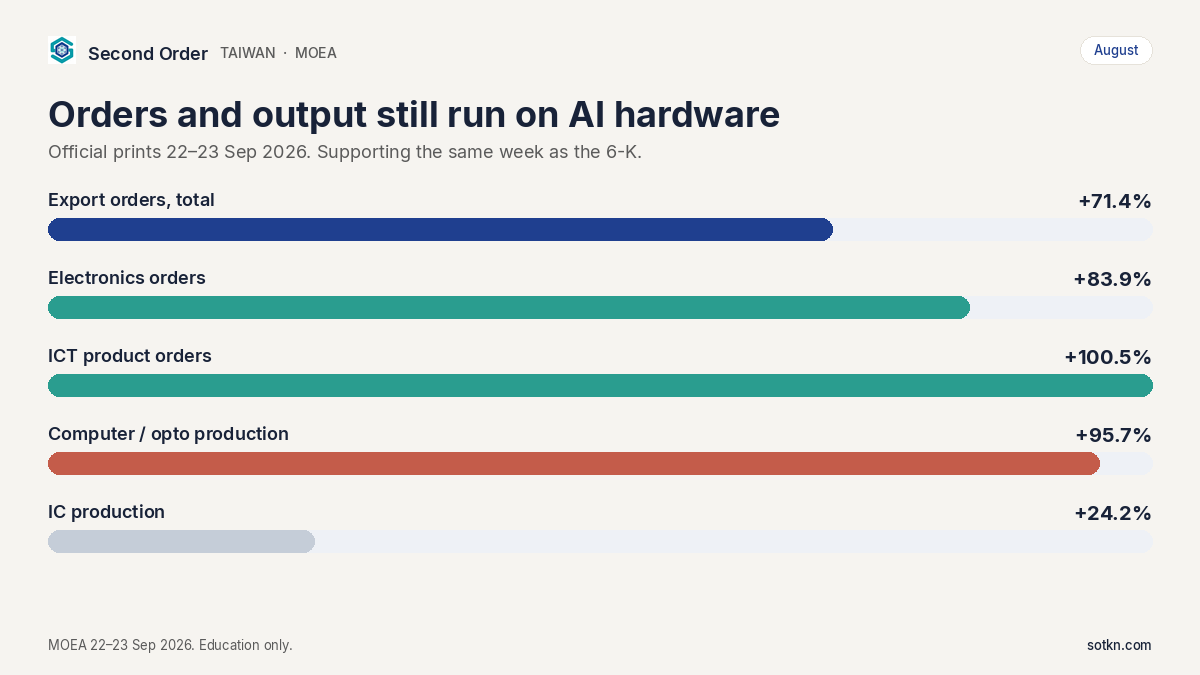
Orders and factory output are still an AI-hardware mix. Sources: MOEA 22–23 Sep 2026. Education only.
Where does the money stick?
At the steps that turn a board check into installed tools — and at the join that still rations finished accelerators.
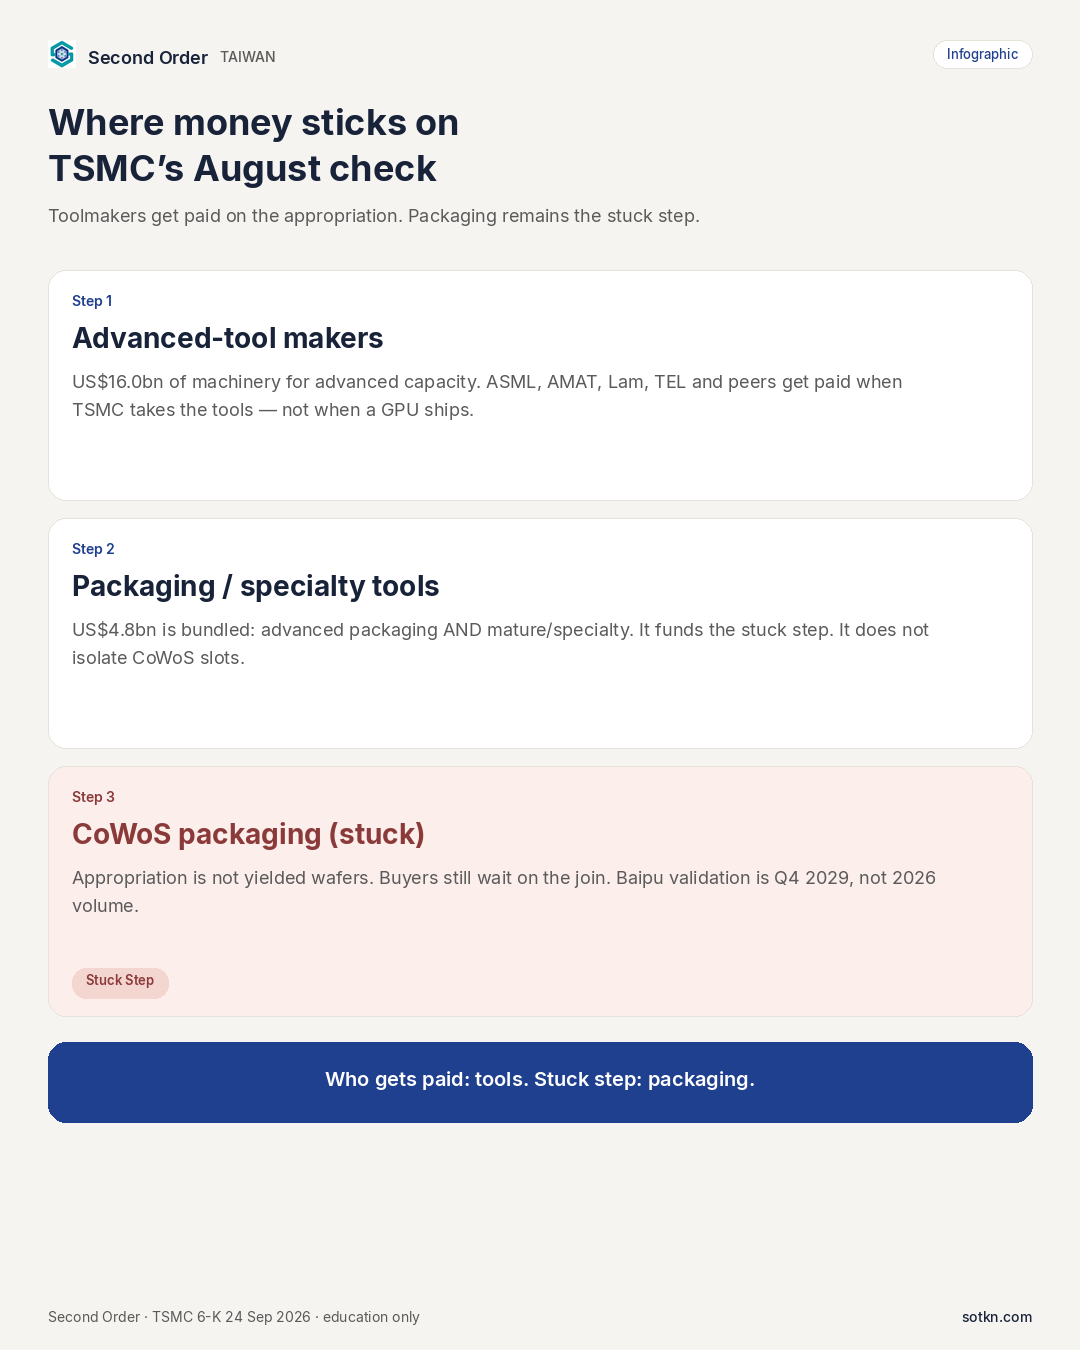
Where money sticks on TSMC’s August check. Source: TSMC 6-K 24 Sep 2026. Education only.
-
Advanced-tool makers. US$16.035 billion is the loud cash line. Whoever TSMC is taking lithography, deposition, etch and metrology from gets paid when the tool is accepted — years of lead time, not a GPU quarter. That is the foundry-equipment step, not the packaging gate.
-
Packaging and specialty-tool makers. US$4.791 billion is smaller and mixed. It is still a payment. It is not a CoWoS capacity table. Treat it as “the stuck step is being capitalised,” not as “the stuck step moved.”
-
Shells and leases. US$8.616 billion is buildings and capitalized leased assets. Construction firms and landlords get paid on a slower clock than a monthly sales print. The 21 September Baipu Mini-Loop Pulse is the extreme of that clock: a validation hub aimed at Q4 2029, not 2026 volume.
-
Not the server assemblers, on this filing. Foxconn, Quanta and Wistron show up in MOEA’s ICT lines — volume. Many firms can bolt a rack. This 6-K is a scarce-step document.
One-line rule: the money sticks where the tool is accepted; the accelerator still sticks where the package is yielded.
Is CoWoS still stuck?
Yes. A bundled packaging-and-specialty appropriation is evidence TSMC is still buying the gate. It is not evidence the gate has opened.
What the 24 Sep 6-K settles — and what it does not
The 16 September revenue Pulse still owns the CoWoS shortage as a demand-versus-capacity read. This Pulse owns the capital twin: TSMC is writing a packaging-and-specialty cheque without a wafers-per-month number. Built is not working. Working is not allocated to second-tier buyers. Watch those lead times.
If packaging catches up, the stuck step moves. Candidates stay HBM and speed-to-power.
What dates matter
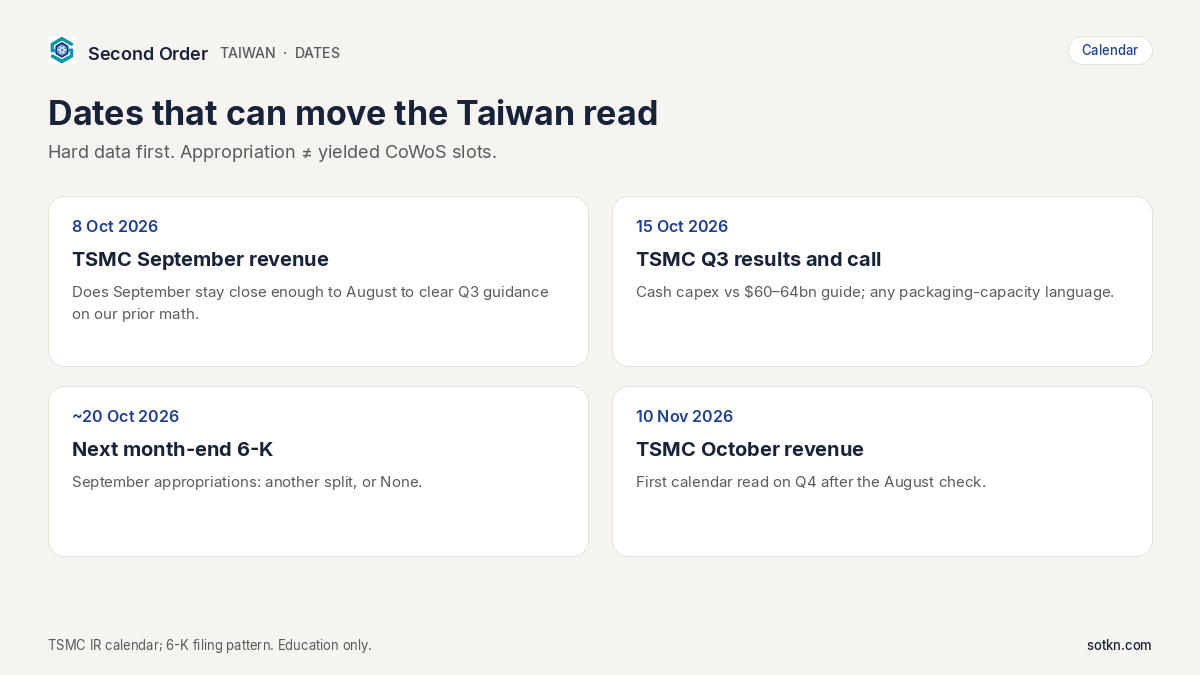
Dates to watch for the split-check read. Education only.
-
8 Oct 2026 — TSMC September revenue. On the 16 September Pulse’s arithmetic, July plus August already covered most of the US$44.6–45.8 billion Q3 sales guide. A sharp drop would be the news; a print near August would not be a new capex fact.
-
15 Oct 2026 — TSMC Q3 results and call (14:00 Taiwan time; quiet period 5–14 October). Cash capex versus the US$60–64 billion band, and any packaging-capacity language that names a variant.
-
Around 20–25 Oct 2026 — next month-end 6-K. Another split, a smaller number, or None (July’s month-end 6-K on 25 August printed None).
-
10 Nov 2026 — TSMC October revenue. First calendar-month read on Q4 after the August check.
-
Open — US chip tariff framework. Still being written. Carve-outs change where later real-estate lines land; they do not turn this 6-K into slots.
How is this different from the Revenue Pulse — and from Baipu?
As a capital split, not a sales reprint.
The TSMC revenue Pulse owns August’s NT$514.8 billion and the Q3 sales bridge. This Pulse owns the 24 September 6-K line items: what TSMC sold versus what the board authorised.
The Baipu Mini-Loop Pulse owns a 21 September groundbreaking for a CoWoS validation hub (25–50% efficiency aim, operations expected Q4 2029). This filing is 2026 authorisation, not 2029 qualification. Do not collapse Baipu into the US$4.791 billion line.
Korea still owns HBM. The US door still owns interconnection. China still owns the 28 September power-mix meter.
- Hyperscalers / neoclouds: a packaging cheque does not shorten lead time until slots qualify.
- Tool vendors: paid on acceptance of the machinery lines.
- OSATs: overflow only if TSMC still cannot do the join — the 6-K does not settle that.
What would change this view?
The “check is not slots / CoWoS still stuck” read weakens if:
- TSMC prints a dated CoWoS (or CoWoS-L / SoIC) wafers-per-month figure that shows the gap closing for buyers outside the top of the book
- A second packager qualifies on a leading AI accelerator — qualification, not a capability slide
- Q3 cash capex collapses versus the US$60–64 billion band for reasons other than timing of tool deliveries
- Lead times for non-top-tier CoWoS customers shorten in a dated way
- The next month-end 6-K shows the packaging/mature line at zero while TSMC says packaging is no longer limiting
- Memory, not packaging, becomes the louder bind — then re-weight to the Korea HBM door
- Power for finished racks, not the Taiwan join, becomes the louder bind — then re-weight to the US and China power Pulses
The view stays intact while the packaging line stays bundled, lead times stay long, and monthly sales keep climbing on a stuck join.
Practical takeaways
- Name the stuck step: CoWoS packaging. The 24 Sep 6-K funds a bundled packaging/mature/specialty line. It does not print slots.
- Dated print: US$16.035bn advanced tools, US$4.791bn packaging/mature/specialty tools, US$8.616bn property — US$29.442bn, matching the 11 Aug lump
- Our arithmetic: 54.5% / 16.3% / 29.3% split; 77% of tools are advanced; three 2026 board lumps sum to ~US$105.7bn against a US$60–64bn cash guide — different objects
- Who gets paid: toolmakers and construction. Server assemblers show up on MOEA’s volume lines, not on this 6-K
- Keep the 16 Sep revenue Pulse for the Q3 sales bridge and Baipu for the 2029 validation clock
- Next hard data: 8 Oct September sales, 15 Oct Q3 cash capex and any packaging language
FAQ
What did TSMC’s 24 September 2026 6-K print?
For the month of August, the board approved US$16.035 billion of machinery for advanced-technology capacity, US$4.791 billion of machinery for advanced packaging, mature and/or specialty capacity, and US$8.616 billion of real estate and capitalized leased assets. The three lines sum to US$29.442 billion.
Who gets paid on that August check?
Equipment vendors on the two machinery lines, and whoever TSMC is paying for buildings and capitalized leases on the third. TSMC itself still gets paid on scarce leading-edge wafers and packaging slots. The 6-K is an authorisation, not a customer invoice.
Is CoWoS still the stuck step?
Yes. The packaging figure is bundled with mature and specialty tools, and an appropriation is not a yielded wafer. Baipu is a validation hub aimed at Q4 2029. Watch lead times, not the existence of a cheque.
Is US$29.4 billion half of TSMC’s 2026 capex?
No. That would mix a board appropriation with the US$60–64 billion cash budget. TSMC spent US$26.80 billion of cash capex in the first half. Board lumps in February, May and August already sum to about US$105.7 billion on our arithmetic because authorisations can cover later years.
How is this Pulse different from the August revenue Pulse and from Baipu?
Revenue (16 Sep) maps what TSMC sold. Baipu (23 Sep) maps a 2029 validation campus. This Pulse maps the 24 Sep line-item split of the August board check.
Is this a buy list of TSMC or of toolmakers?
No. This Pulse maps who gets paid and which step is stuck. It is education only, not a recommendation to buy or sell any security.
Keep reading on the map
- CoWoS, explained · HBM, explained · Speed-to-power explained
- TSMC revenue Pulse · Baipu Mini-Loop Pulse · Taiwan packaging gate · Korea Markets hub · Taiwan Markets hub
- Semiconductors stack · The Stack · Analysis · Wire
How we check this
Figures come from company filings and government releases, each dated in the list below. Focus Taiwan breakdowns of MOEA tables are labelled as such. Where we work something out ourselves, the arithmetic is shown in full and marked “our arithmetic.”
Last reviewed: 29 Sep 2026 · Next review: after TSMC September revenue (8 Oct) or Q3 results (15 Oct)
Spot an error? Tell us and we will correct it and note the change here.
Sources
- TSMC Form 6-K — month-end capital appropriations (August 2026) (24 Sep 2026)
- TSMC Form 6-K — board resolutions, US$29,442.50 million lump (11 Aug 2026)
- TSMC Form 6-K — board, ~US$44,962 million (10 Feb 2026)
- TSMC Form 6-K — board, ~US$31,284.30 million (12 May 2026)
- TSMC Q2 2026 quarterly results (cash capex US$11.10bn / US$15.70bn / YTD US$26.80bn; FY cash budget US$60–64bn)
- TSMC financial calendar (8 Oct monthly sales; 15 Oct Q3 call)
- TSMC August 2026 revenue report (10 Sep 2026)
- MOEA — August 2026 export orders (22 Sep 2026)
- Focus Taiwan — export orders record (MOEA tables) (22 Sep 2026)
- MOEA — August 2026 industrial production (23 Sep 2026)
- Focus Taiwan — industrial production record (23 Sep 2026)
- Second Order — TSMC revenue Pulse (sibling · sales clock)
- Second Order — Baipu Mini-Loop Pulse (sibling · 2029 validation clock)
Education only. Not investment advice. Do your own research. Second Order may correct figures if primary sources revise them — next planned refresh after TSMC’s 8 October monthly sales or 15 October Q3 results.