Signed, Not Delivered: Who Gets Paid While Microsoft's Rented GPUs Wait
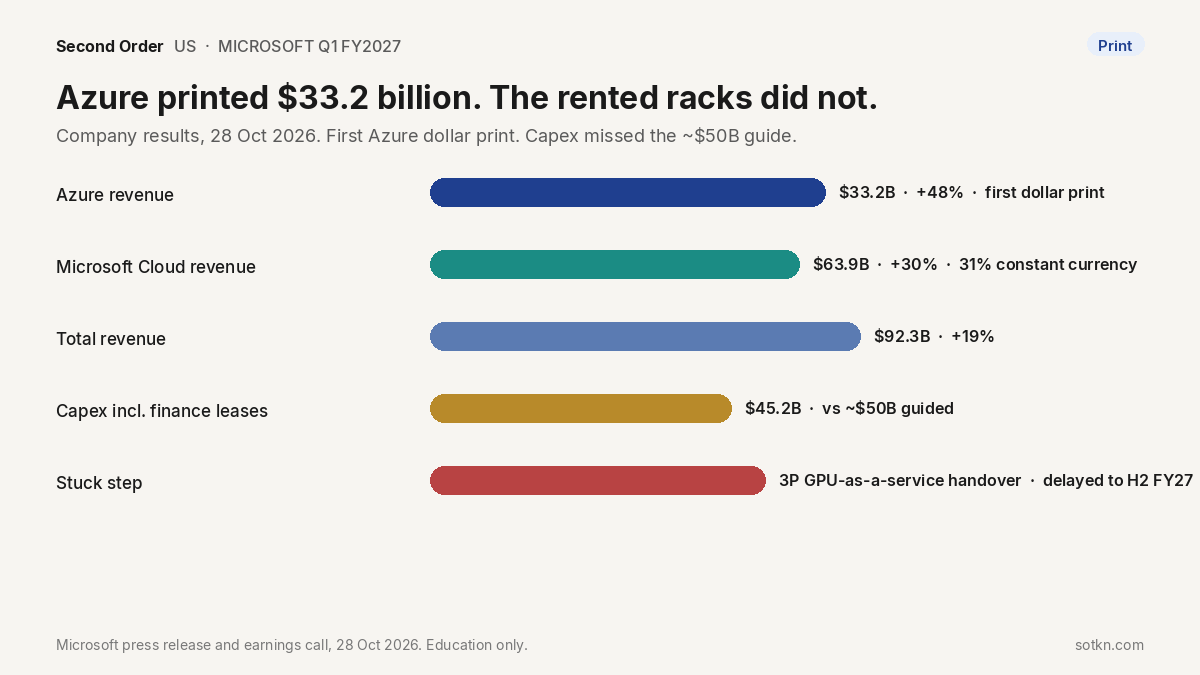
Microsoft on 28 October printed Azure at $33.2 billion, up 48%, and $45.2 billion of capex, short of a ~$50 billion guide. Who gets paid is Microsoft on Azure that billed. The stuck step is still handover of rented GPU-as-a-service racks.
Microsoft printed Azure in dollars for the first time on 28 October: $33.165 billion, up 48%, on $92.279 billion of sales. Who gets paid is Microsoft, on Azure that billed from the fleet it already had, and the shareholders who took $10.2 billion of dividends and buybacks. The stuck step is still handover of third-party GPU-as-a-service capacity. Some of those contracts slipped to January–June 2027. Capex including finance leases came in at $45.2 billion, short of the roughly $50 billion the company had pointed to, because a finance lease books when the racks go live, not when the paper is signed.
US PULSE · Data as at 29 Oct 2026 · Next update: after Amazon’s Q3 print or a named 3P GPU handover
Affects: Hyperscalers · GPU-as-a-service · Neoclouds — Markets: US · Korea · Taiwan
Education only, not advice to buy or sell any security. Company figures: Microsoft press release, cash-flow statement and earnings call, 28 October 2026. Consensus from StreetAccount and LSEG as reported by CNBC and Investing.com. Nine-month calendar capex tally from Reuters. Own sums are labelled “our arithmetic”.
The numbers that matter this month
Azure revenue, Q1 FY2027
$33.165B
+48% YoY · first time Microsoft has printed Azure in dollars
HeadlineMicrosoft Cloud revenue
$63.9B
+30% YoY · +31% constant currency · sequential dollars added nearly doubled
Paid on AzureCapex including finance leases
$45.2B
Against a ~$50B company guide · cash PP&E $39.367B · finance leases $7.4B
Timing, not thriftFree cash flow
$18.6B
Operating cash $58.0B · cash PP&E $39.367B · our arithmetic $18.633B
Cash, not just profitCommercial remaining performance obligation
$677B
+73% YoY · ~30% in the next 12 months · duration 2.3 years
Signed book3P GPU-as-a-service handover
Still the bind
Some Q1 deliveries delayed to January–June 2027. Demand still exceeds supply. A signed lease is not a live rack.
Stuck stepStatus chips are Second Order’s read. Figures: Microsoft press release, cash-flow statement and earnings call, 28 Oct 2026.
Why does the US matter now?
Because this print is the P&L receipt on the buyer that signs the GPU, the hall and the offtake. Taiwan packages the accelerator. Korea stacks the high-bandwidth memory beside it. The US writes the cheque that starts those two clocks — and, on this paper, it also writes the GPU-as-a-service leases that did not commence.
Every AI build still starts with accelerators, memory and servers. The buyers sit here: hyperscalers and neoclouds. The 23 October Meta pulse was capex that outran cash. The 19 October NiSource pulse was 1,100 MW of interconnect still waiting on a pad. Today is Microsoft’s first quarter of fiscal 2027: Azure in dollars, a capex miss from late third-party racks, and contracted revenue up 73%. Not a Meta reprint, not a grid-queue story.
1 · Microsoft, on Azure that billed
Who: Microsoft Cloud / Azure, selling from the fleet already live
Paid: $33.165B of Azure, +48%; Cloud $63.9B, +30%; operating income $45.915B, 50% margin
2 · Shareholders, on the cash
Who: The register, via dividends and buybacks
Paid: $18.6B free cash flow and $10.2B returned this quarter
3 · Chip and memory suppliers, later
Who: CPU, GPU, HBM and storage vendors on the H2 restock
Paid: Not this quarter’s delayed 3P racks. Hood said the fiscal-second-half rise comes from CPUs (including higher memory and storage costs), GPUs, and the slipped deliveries
4 · 3P GPU-as-a-service handover
Who: Outside providers whose GPU-as-a-service contracts did not commence
Paid: Not until lease start. Empty amber bays on this morning’s cover are not a live rack
Labels: Paid first = Azure billed +48% without the delayed racks. Stuck step = 3P GPU-as-a-service contracts that book at commencement.
If you only remember one thing: a 48% Azure print is a fleet that can still bill, not a third-party hall that has been handed over. Start with GPU-as-a-service, explained if the lease clock is new.
What changed on 28 October
One company paper, one call. The paper is the P&L and the cash-flow statement. The call is the delay, the Azure dollar print, and the calendar-year capex path.
The press release and SEC exhibit 99.1 put first-quarter revenue at $92.279 billion, up 19%, operating income at $45.915 billion, up 21%, and diluted EPS at $4.92 GAAP / $4.89 non-GAAP after the OpenAI mark. Microsoft Cloud was $63.9 billion, up 30% (31% constant currency). Azure was $33.165 billion, up 48% — the first dollar print. Commercial remaining performance obligation rose 73% to $677 billion. Microsoft returned $10.2 billion to shareholders. Agents and Infra, the new segment, did $76.795 billion of sales and $40.558 billion of operating income. Devices and Consumer did $15.484 billion, down 3%.
Cash followed the cloud billings: $58.0 billion from operations, up 29%; cash paid for property and equipment $39.367 billion, against $19.394 billion a year earlier; free cash flow $18.6 billion on the company’s rounding. Hood said capital expenditures were $45.2 billion “as some third party capacity deliveries we expected in Q1 were delayed.” Roughly three-quarters of that capex was short-lived assets, mainly CPUs and GPUs, including higher memory and storage costs. Finance leases were $7.4 billion. The company recognises the full principal of a finance lease in capex at commencement. A late hall is a late line. Operating-lease right-of-use assets, which do not sit in capex, still rose $6.001 billion to $30.178 billion.
Azure still beat. Hood said 48% was ahead of expectations even with the 3P delays, driven by Foundry (revenue more than tripled) and CPU work that sold underused fleet. The company added 24 data centres across five continents and cut GB300 dock-to-live time about 20% in its biggest regions. Demand, she said, still exceeds supply. Q2 guide: revenue $96.0–$97.1 billion; Azure +49–50% constant currency, with fleet efficiency “helping to offset some 3P GPU as-a-service contracts that have been delayed to H2”; capex “over $50 billion”; calendar-year spend “approximately $170 billion due to the 3P capacity delays.” Fiscal-second-half capex is expected to accelerate from CPUs, GPUs, higher memory and storage costs, and those slipped deliveries. CNBC put StreetAccount capex consensus at $50.67 billion for the quarter just printed. Consensus is press. Hood did not name the providers or give a dollar size for the delayed contracts. We do not invent a named neocloud.
Our math: labelled our arithmetic
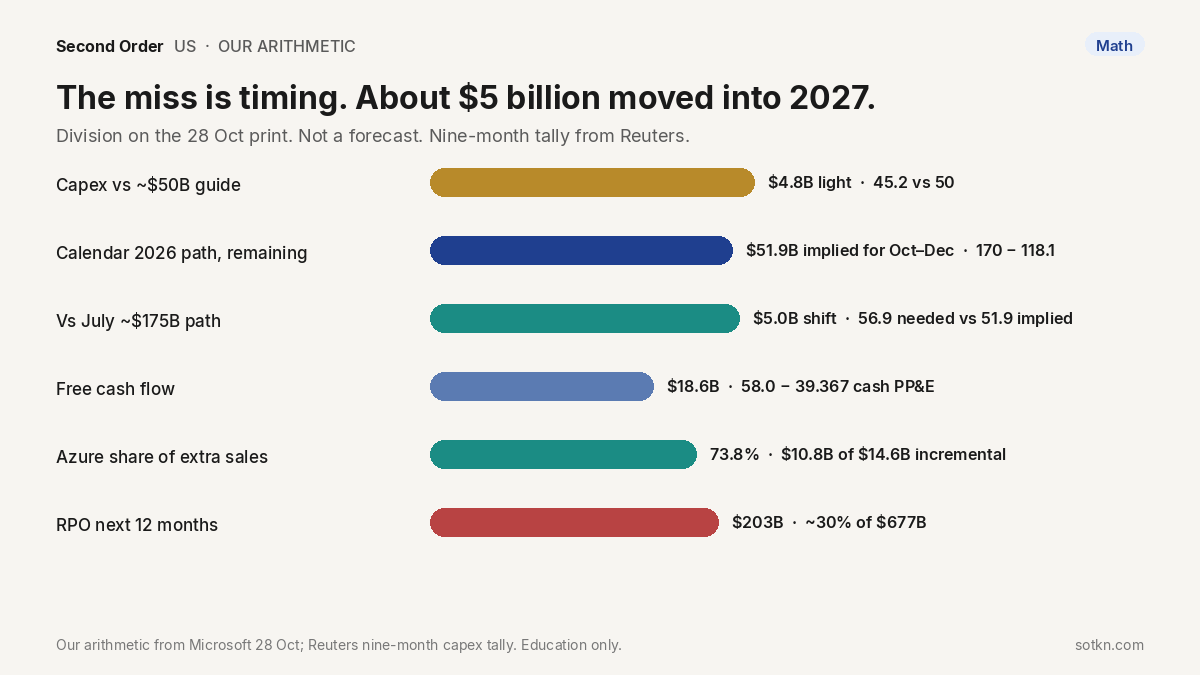
The company already printed the dollars. What follows is division on those figures, labelled as ours.
- The miss. Against a roughly $50 billion company guide, $45.2 billion is $4.8 billion light (our arithmetic). Against CNBC’s StreetAccount $50.67 billion, it is 10.8% below consensus (our arithmetic). The company does not print a miss size. Hood’s reason is the delayed 3P deliveries, not a cut.
- The calendar path. Reuters put calendar-2026 capex at $118.1 billion after this quarter. Hood’s “approximately $170 billion” therefore implies about $51.9 billion for October to December (170 − 118.1, our arithmetic). Hitting the ~$175 billion Microsoft pointed to in July would have needed about $56.9 billion. The difference, about $5.0 billion, is spending moved into 2027, not cancelled. A caution, as on last night’s Wire: CNBC reported the $170 billion as calendar 2027. Hood’s wording and Reuters’ tally both fit calendar 2026, which is how we read it.
- The cash. 58.000 − 39.367 = $18.633 billion of free cash flow (our arithmetic). The company prints $18.6 billion. Cash paid for PP&E was 2.03× the year-ago $19.394 billion (our arithmetic). Alphabet, the same evening, printed $51.4 billion of capex and burned $9.1 billion of free cash. Meta burned $2.1 billion a week earlier. Those are their papers.
- Azure’s share of the extra dollar. Sales rose $14.606 billion year on year. Azure rose $10.781 billion — 73.8% of incremental sales (our arithmetic). Azure is 35.9% of the print. Operating margin is 45.915 ÷ 92.279 = 49.8% (our arithmetic); the company prints 50%. Gross margin is 67.8%; the company prints 68%. Incremental operating margin on extra sales is 54.5%. Mix toward Azure is why Cloud gross margin fell to 66% and is guided at about 65% in Q2.
- The book, and the cheque. Roughly 30% of $677 billion of commercial RPO is about $203 billion in the next 12 months (our arithmetic). Duration 2.3 years; the portion beyond twelve months increased 98%. Commercial bookings fell 12% on large Azure commitments a year earlier. $10.2 billion returned is 54.8% of the $18.6 billion free-cash print (our arithmetic). A signed book, and a cheque, are not a live rack.
What this tells you: Azure billed without the delayed 3P capacity, and the capex line moved with the lease clock, not with demand. What it does not tell you: what a share is worth, or which provider is late. We do not do price calls. We do not invent a named hall.
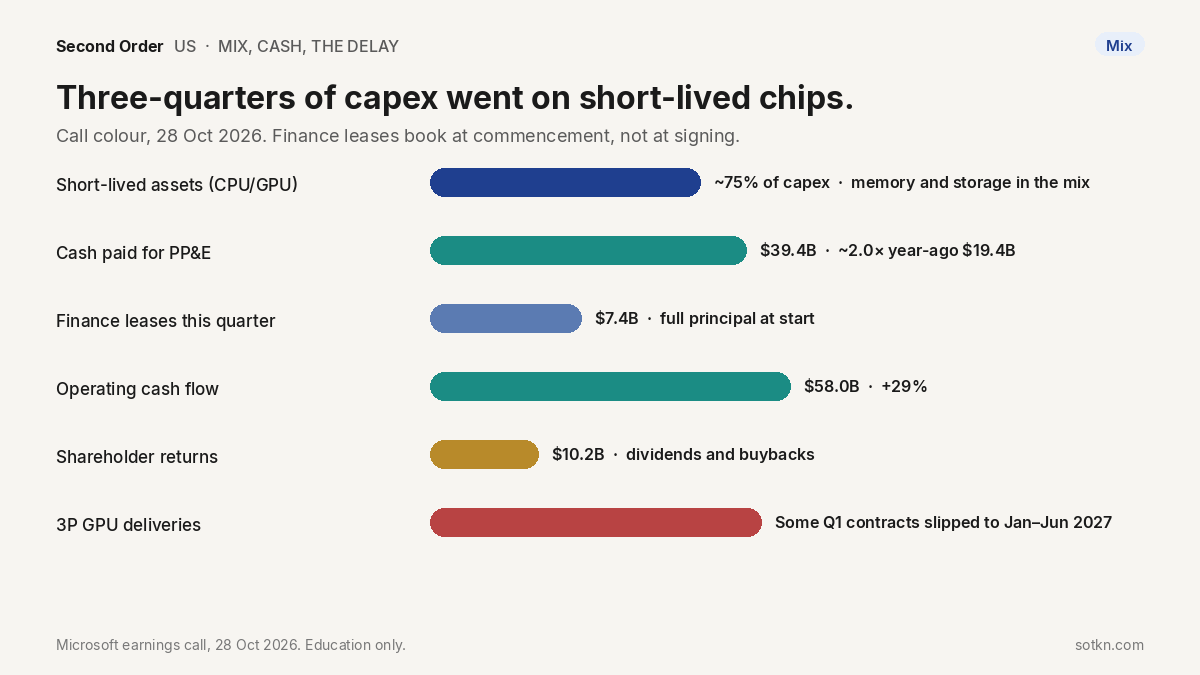
Where does the money stick?
At the step that billed, and at the step that has not yet commenced. Scarce live capacity keeps the Azure dollar. Unsigned commencement keeps the 3P dollar in the future.
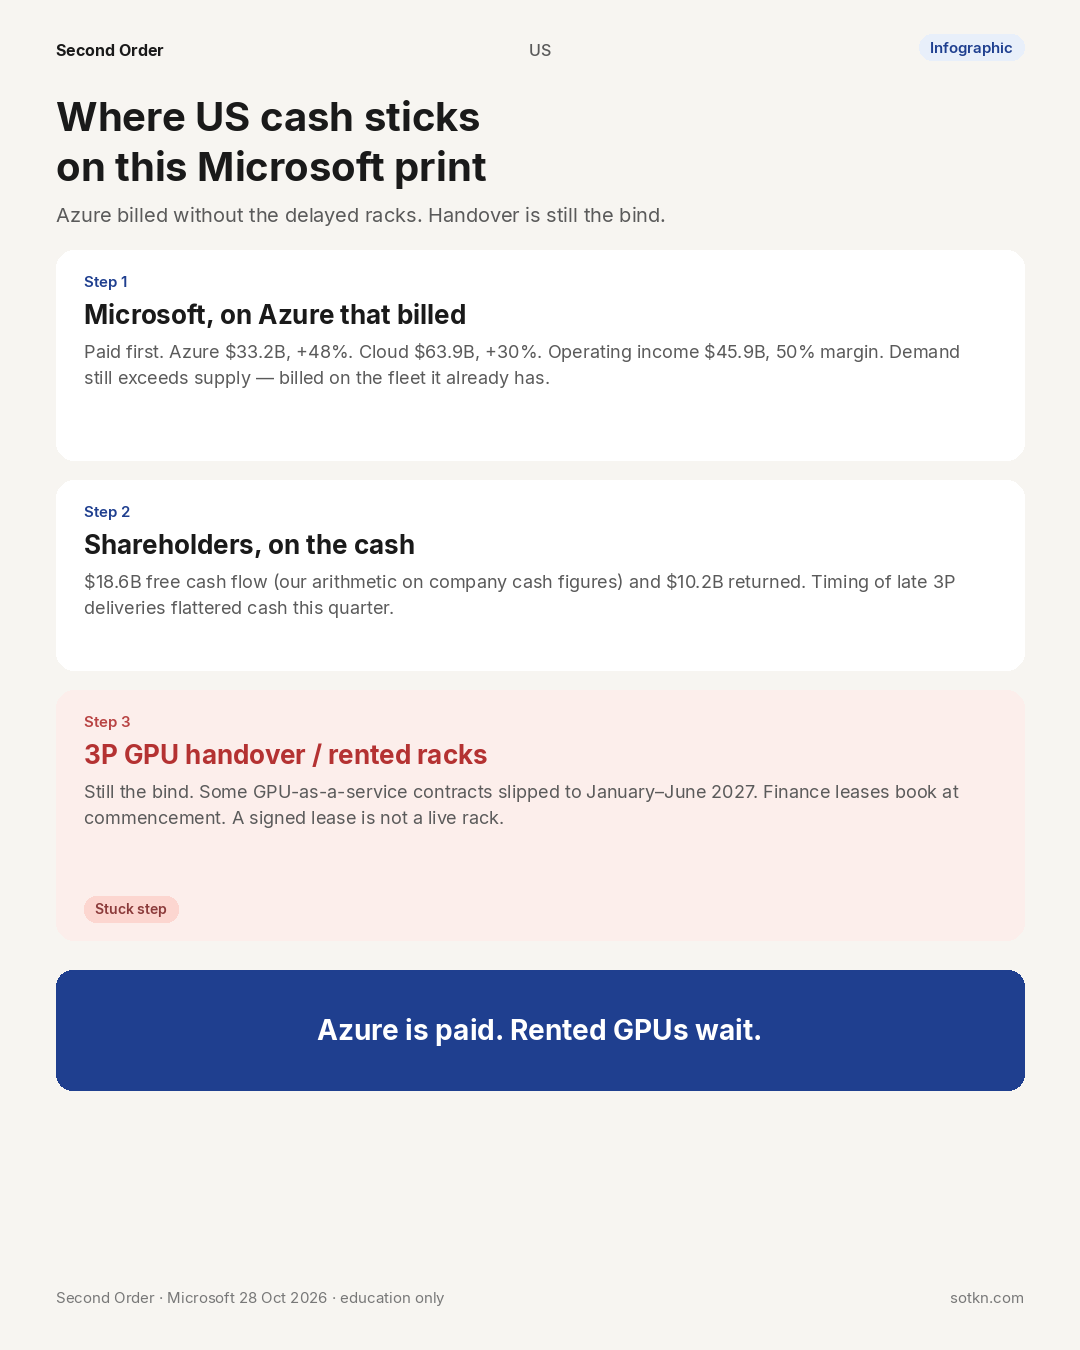
1. Microsoft, on Azure and Cloud that billed. $33.165 billion of Azure, +48%, and $63.9 billion of Cloud, +30%, are the receipt. Foundry more than tripled. CPU efficiency sold idle fleet. When one hyperscaler can still bill at 48% without the delayed third-party racks, that hyperscaler keeps this quarter’s dollar. See the hyperscalers layer.
2. Shareholders, on the cash that followed. $18.6 billion of free cash flow and $10.2 billion of dividends and buybacks are cash leaving after Azure billed. The late 3P deliveries flattered that cash: finance leases that did not commence did not hit capex. Timing, not thrift. Cash PP&E still doubled. The register is paid. The empty bays are not.
3. Chip, memory and storage suppliers, later. Hood said the fiscal-second-half rise comes from CPUs (including higher memory and storage costs), GPUs, and the delayed 3P deliveries. Three-quarters of this quarter’s capex was already short-lived silicon. Korea’s neighbour clock is yesterday’s SK hynix pulse: allocated HBM4. We do not convert a delayed rack into a named cube number.
4. The 3P GPU-as-a-service providers, waiting. Under a finance lease, the clock starts at handover. A late hall is a late invoice. Microsoft did not name them. The neocloud door is where those names usually sit. Until a November print names a delayed hyperscaler handover, this bind stays a category, not a ticker.
One-line rule: while this shape holds, the book on price is Azure that billed, the wait is 3P GPU handover, and the register is being paid out of cash that the delay flattered.
Is 3P GPU handover still stuck?
Yes. A 48% Azure print is a fleet that can still bill from what it already has. It is not a third-party cage whose lease has started.
Three things keep it stuck. First, this print: some Q1 3P deliveries delayed to January–June 2027; the Q2 Azure guide of 49–50% constant currency still needs efficiency gains because “some supply we were counting on Q2 move out into H2.” Hood: “we still have demand that exceeds supply.”
Second, the accounting is the tell. Finance leases enter capex at commencement. Operating leases do not enter capex — and right-of-use assets still rose $6.0 billion. Lower reported capex is not lower building. Cash PP&E doubled. The $4.8 billion gap is the lease clock, not a cancelled hall.
Third, the rest of the map. The 19 October NiSource pulse still has 1,100 MW of interconnect on a longer clock. That is power. This morning is handover of rented GPU capacity — a nearer clock. Packaging in Taiwan and allocated HBM4 in Korea remain neighbours. Members’ map: Where does the stuck step move?. Until a later call names the providers, this pulse’s bind stays 3P GPU-as-a-service commencement.
What dates matter
The 28 October print coloured Azure and the capex miss. Only a later handover print can move the read.
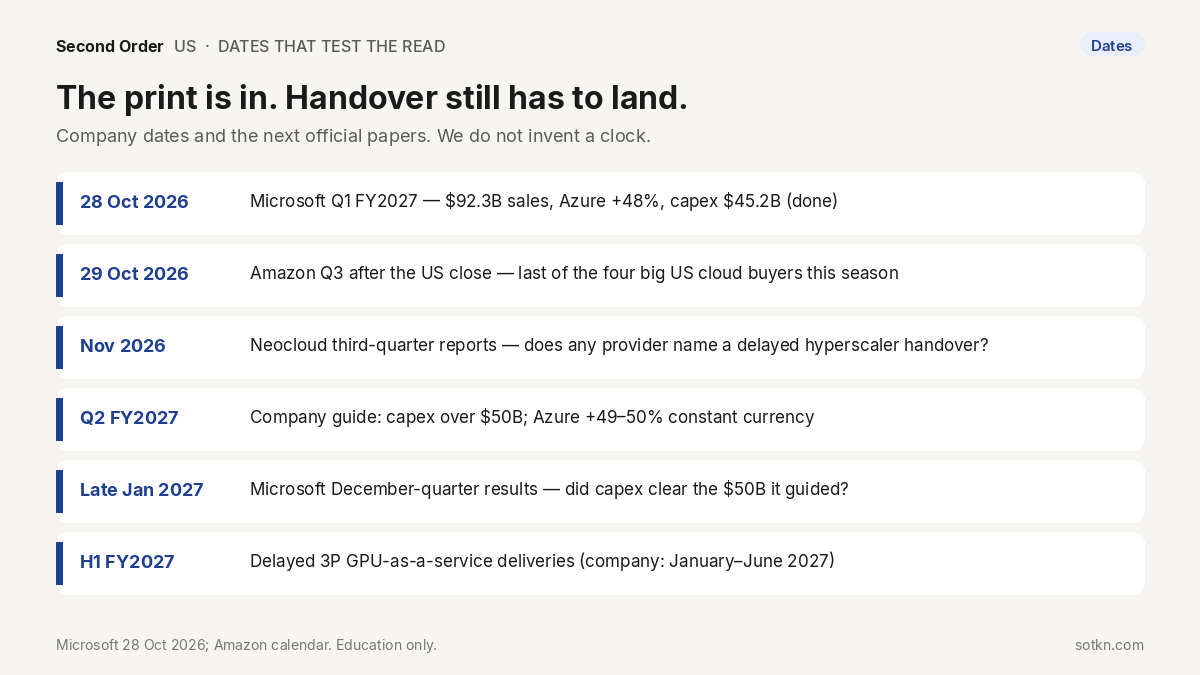
- 28 October 2026 — Microsoft Q1 FY2027 results and call. $92.279B sales, Azure $33.165B (+48%), capex $45.2B. Done.
- 29 October 2026, after the US close — Amazon Q3, last of the four big US cloud buyers this season.
- November 2026 — neocloud third-quarter reports: does any provider name a delayed hyperscaler handover?
- Q2 FY2027 — company guide: capex over $50B; Azure +49–50% constant currency.
- Late January 2027 — Microsoft’s December-quarter results: did capex clear $50 billion, and did any 3P commencement show up?
- H1 FY2027 (January–June 2027) — delayed 3P GPU-as-a-service deliveries (company).
- Not set — a public list of which GPU-as-a-service contracts slipped. That would move the stuck step from a category to a name.
Only a named handover can move the stuck step.
How is this different from the NiSource 1,100 MW pulse?
The 19 October NiSource pulse was interconnect: 1,100 MW signed, the pad still empty, power as the long clock. The 23 October Meta pulse was capex that outran free cash.
Today is a different paper. Who gets paid is Microsoft on Azure that billed — $33.165 billion, +48% — and the shareholders on $18.6 billion of free cash. The stuck step is 3P GPU-as-a-service handover, a finance-lease clock measured in months, not a 1,100 MW interconnect measured in years. Same US door. Different step. Last night’s Wire is the same print in brief. Members’ stuck-step map is the longer clock through memory to power.
What would change this view?
- A later call names the 3P GPU-as-a-service providers, or a neocloud print names a delayed Microsoft handover with a dollar or a megawatt attached.
- Q2 capex prints well below the “over $50 billion” guide without a new delay story — that would look like a cut, not a slip.
- Azure growth prints well below the 49–50% constant-currency guide, or Hood retires “demand exceeds supply.”
- Amazon tonight, or a hyperscaler, cuts 2027 capex before the slipped racks land.
- Finance-lease commencements jump in Q2 while cash PP&E falls — handover arriving, bind moving.
- Power, not GPU handover, becomes the louder US bind, with a named interconnect or generation print attached.
The view stays intact while Azure holds in the high-40s to 50% growth band, capex is described as delayed 3P rather than cancelled, demand is still said to exceed supply, and no provider has named the slipped contracts.
Practical takeaways
- Microsoft, 28 Oct: Q1 FY2027 sales $92.279B (+19%). Operating income $45.915B (+21%), 50% margin. Azure $33.165B (+48%), first dollar print
- Cloud $63.9B (+30%). Commercial RPO $677B (+73%). Bookings −12% on a tough Azure-commitment compare
- Capex including finance leases $45.2B against a ~$50B guide. Cash PP&E $39.367B. Finance leases $7.4B. Free cash flow $18.6B
- Our arithmetic: $4.8B light vs ~$50B; $51.9B implied for Oct–Dec on a $170B calendar path; Azure took 73.8% of extra sales; ~$203B of RPO in the next 12 months
- Who gets paid: Microsoft on Azure that billed; shareholders on the cash the delay flattered
- Stuck step: 3P GPU-as-a-service handover. Some Q1 contracts slipped to January–June 2027. Demand still exceeds supply
- Watch 29 Oct (Amazon Q3), November neocloud prints, Q2 capex over $50B, and a named handover by H1 FY2027
FAQ
What did Microsoft print on 28 October 2026?
First-quarter FY2027 revenue $92.279 billion (+19%), operating income $45.915 billion (+21%), Azure $33.165 billion (+48%) — the first Azure dollar print — and Microsoft Cloud $63.9 billion (+30%). Capex including finance leases was $45.2 billion. Free cash flow was $18.6 billion.
Who gets paid on this print?
Microsoft, on Azure and Cloud that billed from the fleet already live. Shareholders, on $18.6 billion of free cash flow and $10.2 billion of dividends and buybacks. Chip and memory suppliers, later, when the delayed 3P deliveries and the fiscal-second-half restock land. A map of who gets paid, not a buy list.
Why is 3P GPU handover still the stuck step if Azure grew 48%?
A growth rate is a fleet that can still bill. It is not a third-party hall whose finance lease has commenced. Some GPU-as-a-service contracts slipped to January–June 2027. Hood said demand still exceeds supply. Empty bays are not a shipment.
How is this different from the 19 October NiSource pulse?
NiSource was 1,100 MW of interconnect, a years-long power clock. This is Microsoft’s Q1 paper: Azure in dollars, a capex miss caused by late 3P GPU-as-a-service commencement, a months-long lease clock. Same US door. Different step.
Is this investment advice?
No. Education only. It maps who gets paid and which step is stuck. It is not a recommendation to buy or sell any security.
Keep reading on the map
- US Markets hub — country page
- Microsoft capex Wire (28 Oct) — the same print in brief
- NiSource 1,100 MW (19 Oct) — the power clock this pulse is not
- Meta Q3 capex (23 Oct) — the hyperscaler that burned cash
- GPU-as-a-service, explained — the lease
- Finance lease vs operating lease — why commencement moves capex
- Where the stuck step moves — members’ map
- All Markets doors — Taiwan, Korea, US, China
How we check this. First-quarter dollars, Azure, Cloud, RPO, cash flow, PP&E, finance leases, capex, Q2 guide and 3P delay language: Microsoft press release, SEC exhibit 99.1, cash-flow statement and earnings call, 28 October 2026. StreetAccount and LSEG consensus: CNBC and Investing.com, 28 October. Calendar-2026 nine-month capex tally: Reuters, 29 October. Alphabet capex and free cash: Alphabet exhibit 99.1, 28 October. Meta free cash: Meta, 21 October. Own sums labelled “our arithmetic”. Our editorial standards →
Not investment advice. Do your own research.
References
- Microsoft, “Microsoft Announces First Quarter Results,” 28 Oct 2026. microsoft.com/investor
- Microsoft, EX-99.1, 28 Oct 2026. sec.gov
- Microsoft Source, same release, 28 Oct 2026. news.microsoft.com
- Investing.com transcript of the FY2027 Q1 call, 28 Oct 2026. investing.com
- Benzinga, Microsoft Q1 2027 earnings call transcript, 28 Oct 2026. benzinga.com
- CNBC, Microsoft Q1 earnings report 2027, 28 Oct 2026. cnbc.com
- Reuters via CNA, “Microsoft’s cloud growth, cash flow offer respite from AI spending fears,” 29 Oct 2026. channelnewsasia.com
- Alphabet, third-quarter 2026 results, EX-99.1, 28 Oct 2026. sec.gov
- Meta, “Meta Reports Third Quarter 2026 Results,” 21 Oct 2026. investor.atmeta.com
- Second Order, Microsoft capex Wire, 28 Oct 2026. sotkn.com
- Second Order, NiSource–Microsoft 1,100 MW pulse, 19 Oct 2026. sotkn.com
- Second Order, Meta Q3 capex pulse, 23 Oct 2026. sotkn.com